

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: MRI Market to Reach USD 11.73B by 2032 at 6.52% CAGR

MRI Market 2026: Strategic Imperatives and What Leading Health Systems Must Know — A PW Consulting Preview
As healthcare systems, device manufacturers, and investors prepare capital plans for 2026, Magnetic Resonance Imaging (MRI) remains central to diagnostic and therapeutic pathways — yet the decision landscape is shifting faster than many expect. This preview summarizes the strategic value of PW Consulting’s full MRI Market study (base year 2025, historical window 2020–2025, forecast window 2026–2032). Our aim is to demonstrate the depth of analysis you need to make high‑confidence capital, product and partnership decisions in 2026, while reserving the granular segment matrices and proprietary vendor scorecards for the full report.
MRI (Magnetic Resonance Imaging System) Market
Market Snapshot — Macros that Matter
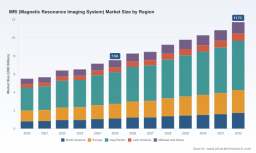
The global MRI market has expanded steadily during the historical window and is projected to maintain mid‑single‑digit growth through our forecast. From a base market of roughly USD 7.5 billion in 2025, PW Consulting’s models project the market growing at a compound annual growth rate (CAGR) of approximately 6.52% across 2026–2032, reaching an overall size north of USD 11 billion by 2032. This trajectory reflects a confluence of factors: technological innovation (including AI acceleration and helium‑independent cooling), demand resilience for neuro‑oncologic and cardiac imaging, and differentiated investment patterns across hospital systems, outpatient imaging providers and emerging point‑of‑care modalities.
MRI (Magnetic Resonance Imaging System) Market
Market concentration is material and should influence strategy: the top three vendors account for a substantive portion of global revenues, and the top five capture nearly four‑fifths of the market. That degree of concentration creates both risks and opportunities for buyers, channel partners and new entrants — from pricing leverage and service availability to collaboration and M&A dynamics.
MRI (Magnetic Resonance Imaging System) Market
Why This Study Matters for 2026 Decision Makers
- Capital allocation precision: With hospital budgets under pressure and average plant age trending upward, boards and CFOs need rigorous total cost of ownership (TCO) frameworks for MRI investments that go beyond sticker price — incorporating service economics, energy consumption, helium usage risk, and expected utilization curves.
- Procurement timing and RPM (revenue‑per‑module) sensitivity: Shifts in reimbursement and evolving outpatient migration patterns mean that timing purchases (and trade‑ins) can materially change ROI outcomes. Our scenario models show breakpoints where delayed or accelerated procurement changes payback timelines.
- Competitive positioning for OEMs and partners: For manufacturers and channel partners, clear differentiation today comes from integrated software–hardware ecosystems, AI workflow acceleration, and manufacturing control over critical components. The commercial playbooks embedded in our report help prioritize R&D and go‑to‑market investments for 2026.
- Risk mitigation for operators: Regulatory clearances, device lifecycle issues, and supply chain fragility (magnified by specialized components such as magnets and cryogens) require contingency plans. The study enumerates practical mitigations and contract constructs to reduce operational disruption risk.
What the Full Report Contains — Practical, Actionable, Confidential Insights
PW Consulting’s MRI Market study combines proprietary and public data with client interviews and advanced scenario modeling. Highlights you will find in the complete report include:
- Market sizing and validated demand curves: historical reconciliation (2020–2025) and a base‑case, upside and downside forecast (2026–2032) with sensitivity to key variables such as reimbursement, service capacity and portable MRI adoption.
- Vendor and technology benchmarking: comparative scorecards covering product portfolios, service footprints, technology roadmaps, and competitive strengths and weaknesses — enabling quick-read supplier shortlists for different buyer archetypes (academic centers, community hospitals, outpatient networks).
- TCO and utilization calculators: configurable models to test acquisition vs. lease, upgrade cadence, service contracts, and phased fleet renewal strategies that translate to executive‑level CapEx/OpEx tradeoffs.
- Go‑to‑market and partnership playbooks: tactical guidance for OEMs and ISVs on channel strategies, OEM‑ISV alliances, and enterprise sales motions that accelerate adoption of AI and workflow modules.
- Regulatory and reimbursement impact scenarios: mapping of recent regulatory wins and proposals to market access outcomes, with playbooks for securing payer coverage and mitigating negative reimbursement trajectories.
- M&A and investment thesis: identification of acquisition targets and capability gaps, informed by market concentration dynamics and service ecosystem opportunities.
We purposefully withhold granular market splits and proprietary vendor shares in this preview. Those detailed matrices — including regional, architecture and application breakdowns, and our full CR‑by‑vendor tables — are available only in the full study and client deliverables.
Competitive Landscape — Who Moves the Needle in 2026
- GE Healthcare (Chicago, IL): A long‑standing portfolio leader with its SIGNA family across multiple field strengths and high‑end applications. GE’s strength is deep installed base and broad service networks — critical when considering mid‑life upgrades and enterprise‑wide refresh programs.
- Siemens Healthineers (Munich, Germany): The MAGNETOM line continues to push innovation at the high‑end, with recent regulatory milestones underscoring their engineering edge. Siemens’ investments in helium‑independent cooling and larger bore platforms influence hospital procurement strategies where patient throughput and site constraints matter.
- Koninklijke Philips N.V. (Eindhoven, NL): The Ingenia series emphasizes patient comfort and workflow efficiency — differentiators for outpatient imaging centers and pediatric programs. Philips’ software and workflow integration remain a decisive factor for buyers focused on throughput and patient experience.
- Canon Medical Systems (Tustin, CA): Notable for vertical integration and AI‑enabled workflow enhancements. Canon’s manufacturing control over magnets and RF components provides resilience against some supply chain pressures and supports competitive service economics.
- Fujifilm Healthcare Solutions (Stamford, CT): Competes across closed and open architectures with flexible solutions for diverse facility types, emphasizing service adaptability and mid‑market penetration.
- United Imaging Healthcare (Shanghai, China): Rapid product development and aggressive AI acceleration features characterize its uMR series — an important entrant for price‑performance dynamics, especially in markets prioritizing throughput and affordability.
- Esaote (Genoa, Italy) and Fonar Corporation (Melville, NY): Niche innovators in open MRI and multi‑position MRI respectively; these players create differentiated options for orthopedics, weight‑bearing imaging and unique clinical workflows.
Recent regulatory and product milestones underscore how quickly the competitive landscape can shift: new FDA clearances for helium‑independent cooling platforms and next‑generation portable systems introduce distribution and service considerations that will reshape procurement discussions in 2026.
Key Dynamics & Near‑term Risks
- Regulatory momentum: FDA clearances for helium‑independent and novel portable MRI systems lower operating costs and expand site feasibility, but they also raise adoption pressure on legacy fleets and service supply chains.
- Reimbursement pressure: Proposed adjustments in reimbursement schedules signal differing trajectories for diagnostic vs. interventional modalities; imaging providers must model downstream revenue exposure, particularly for high‑volume diagnostic workflows.
- CapEx constraints and aging infrastructure: Hospital capital budgets remain strained as operating costs rise and average plant age climbs. That environment favors decision frameworks emphasizing modular upgrades, asset redeployment and refurbishment economics.
- Technology diffusion: AI end‑to‑end workflows, faster sequences, and portable MRI are not merely product upgrades — they alter utilization and staffing models, requiring training, governance and new clinical pathways.
- Concentration and supply risk: High market concentration amplifies the impact of OEM supply decisions, and vertical integration strategies by key players can produce supply advantages or bottlenecks depending on scale.
Practical Strategic Playbook for 2026
- Adopt TCO‑first procurement: Move beyond capital price to model 5–7 year service, energy and utilization scenarios. Use the full report’s calculators to stress‑test acquisition structures.
- Prioritize modular upgrades where possible: Phased investments in AI, coils and software licences can defer large CapEx decisions while capturing near‑term efficiency gains.
- Negotiate service and spare parts guarantees tied to performance: Given concentration and criticality, contract terms that align payments to uptime and throughput reduce downstream financial exposure.
- Build interoperability and data governance into acquisitions: Devices that lock you into proprietary workflows can erode long‑term value; demand open APIs and robust integration plans.
- Target selective strategic partnerships: For OEMs and ISVs, prioritize alliances that expand software ecosystems (AI, scheduling, reconstruction) and accelerate enterprise penetration through channel partners.
- Prepare for reimbursement variability: Model worst‑case reimbursement scenarios in capital plans and stress test utilization assumptions for diagnostic volumes.
- Explore opportunistic M&A: For growth‑oriented investors and OEMs, M&A can accelerate access to specialty niches (portable, open, multi‑position systems) and service networks in markets with under‑penetrated fleets.
Next Steps — How to Use the Full PW Consulting Study
If you are finalizing capital budgets or defining product strategy for 2026, the complete MRI Market study provides the operational models, regional and application breakouts, and vendor scorecards you need to move from strategy to procurement. The report is designed to be actionable within 30–90 days: plug our TCO outputs into your CapEx process, use vendor shortlists to run RFIs/RFPs, and apply our scenario playbooks to board‑level decision memos.
Contact PW Consulting for access to the full study and confidential workshops tailored to your role — whether you are a hospital CFO optimizing fleet renewal, an OEM prioritizing R&D investment, or an investor assessing consolidation targets. The preview above outlines the strategic contours; the full study delivers the segment‑level, evidence‑backed intelligence required to execute in 2026.
For detailed analysis of this topic, please visit the official page: MRI (Magnetic Resonance Imaging System) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com