

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Tunnel & Metro Market to Reach USD 344.83 Million by 2032 at 6.98% CAGR

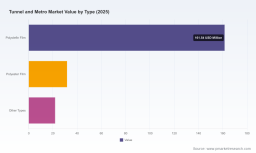
Tunnel and Metro Market 2026 — Strategic Preview from PW Consulting
PW Consulting’s latest Tunnel and Metro Market study (base year 2025; historical analysis 2020–2025; forecast 2026–2032) reframes how infrastructure decision‑makers should approach tunnelling capital allocation, procurement and technology strategy in 2026. The study quantifies an industry that, on a consolidated basis, is forecast to grow at a compound annual growth rate (CAGR) of 6.98% over the 2026–2032 window — rising from an estimated USD 215.0 million (2025, USD Million revenue unit) to a projected market approaching USD 345 million by 2032. This preview explains why that topline trajectory matters, what practical intelligence the full report delivers, and how stakeholders can convert insights into defensible commercial moves — while intentionally holding back the granular splits that you will find in the full research package.
Tunnel and Metro Market
Why this report is mission‑critical for 2026 decisions
-
Timing of capital deployment: The market’s mid‑single digit CAGR masks pockets of accelerated demand and seasonal project clustering. Knowing where those pockets will appear in 2026 is essential to time TBM procurement, spare‑parts inventory and financing.
Tunnel and Metro Market -
Supplier and contract negotiation: With lead times for bespoke TBMs stretching, procurement teams must align contracting windows with manufacturing capacity and supply‑chain exposures. Our analysis surfaces the risk points and negotiation levers you can use at bid stage.
Tunnel and Metro Market -
Technology pathway decisions: Choices between tried‑and‑tested large‑diameter slurry/EPB machines and emerging rapid‑boring systems have multi‑year capex and O&M consequences. The report models scenarios that translate machine selection into lifecycle cost and schedule outcomes.
-
Regulatory and ESG compliance: 2026 tendering increasingly penalizes carbon intensity and energy inefficiency. We map how “green TBM” innovations and energy metrics will influence project scoring and cost of capital.
-
Investor underwriting and M&A: Investors require forward‑looking revenue and margin assumptions that reflect raw‑material volatility, labour automation trends and competitive fragmentation; our forecast provides those assumptions and sensitivity tables.
What the report delivers — practical, transaction‑grade intelligence
-
Market sizing and repeatable methodology: Transparent topline market series (2020–2025) and an explicit forecasting architecture for 2026–2032, with scenario toggles for commodity shock, demand surge and technology adoption curves.
-
Vendor capability maps: Comparative assessments of technical scope, manufacturing footprint, product families (slurry, EPB, gripper, hard‑rock), and aftermarket service models — presented as decision matrices to guide OEM selection.
-
Supply‑chain heatmaps: Identification of single‑point dependencies (steel, bearings, electrical controls), supplier lead times and hedging strategies for 2026 procurement cycles.
-
Project pipeline and risk scoring: A prioritized project list and an executable risk scoring model for early‑stage bids and long‑lead procurement planning.
-
Contract and financing playbooks: Negotiation checklists, contract clauses and financing structures tailored to capital‑intensive TBM deliveries and sustained metro programs.
-
Operational playbooks: Deployment, digital‑twin integration, automation and human‑capital strategies to mitigate skilled‑labour shortages and reduce schedule risk.
Market dynamics shaping 2026 strategy
-
Raw‑material pressure and margin stress: Structural steel — a core input for TBM shields and frames — experienced an abrupt price increase in recent cycles. That pressure has meaningful implications for OEM margins, pricing strategies and tender design; we model the pass‑through and hedging options.
-
Technology diffusion: Gripper TBM systems have matured to deliver precise steering with reduced surface vibration, making them increasingly attractive for dense urban metro alignments. Concurrently, automation and digital‑twin systems are being deployed to address skilled‑labour shortages and to shorten machine commissioning timelines.
-
Green engineering as a procurement filter: High‑profile showcases at trade venues highlighted energy‑efficient TBM configurations and emissions‑reducing systems. For 2026 tenders, energy consumption and lifecycle carbon measures are likely to be meaningful selection criteria.
-
Commercial innovation at the edges: New entrants and design innovations — notably rapid TBM concepts aimed at order‑of‑magnitude cycle reductions — are reshaping owner expectations for schedule and cost; our scenarios quantify the practical window in which such disruptive benefits can be realized.
-
Project momentum and timing: Major program milestones (factory testing, site assembly and launch schedules) for headline megaprojects will concentrate demand and aftermarket service needs during discrete 2026 windows. Our project‑level timing model helps owners and suppliers avoid costly bottlenecks.
Competitive landscape — who matters and why
The vendor field combines deep‑engineering incumbents, scaled national OEMs and technology disruptors. Leading mechanised‑tunnelling incumbents bring decades of global experience supplying slurry, EPB and shield TBMs; some specialise in large‑diameter and under‑water machines for metro and rail tunnels. National OEMs from major construction markets have rapidly scaled manufacturing and can offer competitive lead times for large program wins. Meanwhile, new‑tech entrants are pushing the performance envelope on cycle speed and modularity.
-
Strengths of established European and Japanese OEMs: engineering pedigree, service networks, and demonstrable reliability on long‑haul and high‑risk contracts.
-
Chinese OEM dynamics: rapid capacity expansion, growing capability in large single‑shield and mixed‑face TBMs, and an increasing role on internationally financed metro projects.
-
New entrants and niche suppliers: focus on specialized EPB/gripper designs, rapid‑deployment systems and digitization packages — creating asymmetric negotiating leverage for agile contractors and owners.
-
Fragmentation and opportunity: the market remains sufficiently fragmented to permit strategic partnerships, captive manufacturing arrangements and targeted M&A. Top suppliers do not yet dominate the market to the point of crowding out new entry, leaving room for differentiated strategies.
2026 strategic playbook — concrete moves for four stakeholder groups
-
OEMs: lock raw‑material hedges for high‑value components; invest in modular design to shorten lead time; formalize service contracts tied to digital‑twin outputs to capture aftermarket margins.
-
Contractors: build pre‑qualified supplier pools, negotiate flexible delivery windows, and co‑invest in commissioning rigs to accelerate start‑up and reduce schedule risk on multi‑TBM projects.
-
Investors and financiers: apply scenario stress‑testing on commodity shocks and schedule slippage; prefer projects with performance‑linked revenue waterfalls and strong ESG compliance clauses.
-
Public owners and regulators: mandate lifecycle energy metrics in procurement, incentivize local supply participation for job creation, and require robust contingency plans for long‑lead equipment.
How PW Consulting’s modelling supports executable decisions
Our study combines a bottom‑up project consolidation (historical 2020–2025) with a configurable forecasting engine for 2026–2032. The model exposes sensitivity to critical variables — steel cost trajectories, adoption rates of automation, project start‑date slippage and vendor market share shifts — allowing users to produce tailored scenarios for procurement and investment committees. Importantly, the public summary here is intentionally selective: detailed regional and application breakdowns, machine‑type revenue splits, and vendor‑level financial profiles are withheld from this preview so that readers must access the full dataset for actionable granularity.
What’s new in the market — 2025–2026 highlights that matter for 2026
-
Manufacturing milestones for major megaprojects will concentrate demand and require coordinated logistics and onshore assembly planning in early 2026.
-
Trade shows in 2025 showcased energy‑efficient TBM designs and commercialized digital solutions; expect procurement scorecards that reward demonstrable CO2 and energy reductions.
-
Rapid‑boring concepts have moved from prototype to commercial demonstrations, creating a bifurcated market — traditional heavy‑lift TBMs for complex geology, and rapid systems for utility and short‑span metro works.
-
Steel price volatility and labour dynamics are the two most immediate cost risks for 2026 project budgets; the full report quantifies potential budget overruns under alternative shock scenarios.
Next steps — how to use this preview
If your 2026 plans include TBM procurement, contractor selection, financing of tunnel programs, or positioning for aftermarket growth, treat this article as a strategic briefing. The full PW Consulting Tunnel and Metro Market report contains the transaction‑grade datasets and vendor scorecards required to convert high‑level strategy into executable tenders, RFQs and investment memoranda. To preserve the structure and competitive value of our work, granular regional/application splits and vendor revenue schedules are accessible only in the full report and accompanying model — designed to be integrated into client decision workflows.
For executives preparing bids, procurement directors planning 2026 deliveries, and investors underwriting metro pipelines: PW Consulting’s full deliverable provides the calibrated inputs and playbooks to move from hypothesis to decision. Contact PW Consulting to unlock the complete dataset, scenario models, and bespoke advisory support that will make your 2026 initiatives resilient, timely and cost‑effective.
For detailed analysis of this topic, please visit the official page: Tunnel and Metro Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com