

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Triclosan Market - USD 134.55M by 2032 at 6.66% CAGR

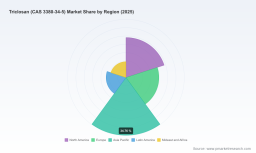
Triclosan (CAS 3380-34-5) Market Outlook 2026: Strategic Imperatives for Decision Makers
Executive teaser
Between 2020 and 2025 the global Triclosan market transitioned from a niche specialty-chemicals segment into a strategically contested arena. Our base-year assessment (2025) identifies a market that rose from roughly USD 52 million in 2020 to USD 86.42 million in 2025, and that is forecast to continue expanding — reaching an estimated USD 91.73 million in 2026 and USD 134.55 million by 2032 at a compound annual growth rate of 6.66% across the 2026–2032 forecast window. These headline numbers frame a clear reality: Triclosan remains commercially relevant, but the next 24 months will determine which suppliers and end-users convert incremental demand into durable advantage.
Triclosan (CAS 3380-34-5) Market
Why this research matters for 2026 corporate decisions
-
Timing procurement and hedging: short-term input-cost shocks (notably phenol, a key feedstock) and regulatory changes mean purchase timing and contracting strategy can materially affect margins.
Triclosan (CAS 3380-34-5) Market -
Regulatory compliance and go-to-market risk: product availability on critical markets is now conditional on compliance with newly enforced restrictions — firms must reconcile product portfolios and market access strategies with evolving compliance costs.
Triclosan (CAS 3380-34-5) Market -
Supply-chain resilience and supplier selection: concentration dynamics and the geographic distribution of production capacity imply counterparty risk that must be actively managed through diversification, strategic stockpiles, or vertical integration.
-
M&A, JV, and investment prioritization: a measured view of market scale and growth trajectory enables executives to calibrate inorganic moves (buying capability or market access) against organic investment in formulation or regulatory compliance.
What PW Consulting’s full report delivers (practical content highlights)
Our study is designed as an operational playbook for commercial, procurement, regulatory, and corporate development teams. Key deliverables include:
-
Validated market sizing and forward-looking revenue model (historical 2020–2025, base year 2025, forecast 2026–2032) with scenario-based outputs tied to regulatory and input-cost permutations.
-
End-use demand driver mapping that links drivers (e.g., personal care reformulation cycles, textile treatments, healthcare usage) to timing windows for procurement and product launches.
-
Supplier and capability dossiers: operational profiles, quality credentials (e.g., USP/cGMP capability), capacity constraints, and go-to-market footprints for active manufacturers, exporters, and distributors.
-
Regulatory tracker and compliance roadmap that translates jurisdictional policy shifts into time-bound actions for product reformulation, labelling, and market withdrawal/entry decisions.
-
Price and margin sensitivity models incorporating feedstock dynamics and differential cost structures by supplier type.
-
Deal and partnership playbooks: M&A screening criteria, JV structures for de-risked capacity expansion, and licensing models for technology/market access.
-
Fast-action checklists for 90-, 180-, and 360-day decision cycles focused on procurement, manufacturing validation, and regulatory certification.
Market structure and competitive implications
The Triclosan market displays clear concentration: the leading three suppliers account for a dominant share of available supply, with the top five further consolidating market access. That concentration creates both opportunities and risks — incumbents enjoy scale advantages in compliance investment and global logistics, while smaller players can compete on specialty service, speed-to-market, or regional proximity.
Key participant archetypes we profile include: established multinational chemical manufacturers with branded grades and broad distribution channels; regional specialty manufacturers and exporters with cost-competitive volumes; and distributors/importers that bridge regulatory and customer-specific requirements for pharmaceutical and food-industry clients. The competitive map in the full report includes granular supplier scorecards and a capability heatmap to support sourcing and alliance decisions.
Selected company profiles and strategic takeaways
-
Regional Indian manufacturers and exporters play a central role in global sourcing. Their strengths are cost-competitiveness and export-driven capacity — attractive to buyers seeking volume and price flexibility. Strategic implication: buyers should balance cost advantages with contractual guarantees for quality and supply continuity.
-
US-based distributors and suppliers focus on regulated-grade offerings and service-intensive channels (pharmaceutical, research, and specialty food applications). Strategic implication: for innovation-led or compliance-sensitive products, partnering with USP/cGMP-qualified suppliers reduces launch risk.
-
Large multi-national chemical groups retain strategic assets in branded formulations and established global channels. Strategic implication: incumbents can accelerate withdrawal or retainment in markets via reformulation or regulatory engagement, affecting new entrants’ access.
Regulatory and raw material shock drivers — immediate relevance for 2026
Two dynamics are especially material for 2026 plans:
-
Regulatory enforcement: As of 31 October 2025, products containing Triclosan that do not meet the relevant restrictions cannot be made available in certain jurisdictions. This alters market access overnight for some formulations and elevates the cost of non-compliance. Firms must prioritize regulatory certification or controlled market exits as tactical responses.
-
Feedstock volatility: Phenol pricing has shown renewed volatility; recent observations documented an increase to roughly USD 1.01/kg in Northeast Asia with an 8.6% uptick from December 2025. Such input-cost movements directly compress margins and can rapidly change the ranking of cost-competitive suppliers.
Strategic playbook for 2026 — recommended actions
-
Immediate compliance triage: classify SKUs by jurisdictional risk and prioritize re-testing/reformulation where required to maintain market access. Time-box regulatory investments against near-term revenue exposure.
-
Short-term procurement hedges: implement layered contracts (spot, deferred, and option-based) to mitigate feedstock-driven price spikes; consider supplier-backed inventory programs for critical grades.
-
Supplier segmentation and continuity planning: map existing suppliers into a risk matrix (quality/regulatory, capacity, logistical exposure) and develop alternates for single-source dependencies.
-
Portfolio rationalization and innovation: for players facing restricted-market displacement, accelerate evaluation of alternative antimicrobials or preservation technologies, and quantify NPV of reformulation vs. market exit.
-
Commercial repositioning: emphasize certification, traceability, and service (technical support for reformulation) as differentiators in commercial negotiations.
-
Strategic M&A and partnerships: target assets that provide either regulatory-ready capacity in low-risk jurisdictions or R&D capabilities for next-generation preservatives; apply a value-preserving integration plan that protects customer-facing certifications.
Decision-focused analytics included in the report
We do not merely document trends; our models translate them into decision-ready outputs: scenarios that quantify the P&L impact of price shocks, regulatory-driven market exclusions, and supplier disruptions; supplier selection matrices weighted to client priorities (cost, timeliness, certification); and tabulated investment cases for alternative antimicrobial development. These components are provided with sensitivity toggles so executive teams can stress-test strategies before committing capital.
Why PW Consulting — credibility and approach
Our methodology triangulates primary supplier interviews, proprietary trade-flow datasets, and regulatory sources to produce an actionable narrative. We emphasize pragmatic advice: procurement playbooks, compliance roadmaps, and M&A screening tools — not just descriptive charts. The full report expands each of the summarized company profiles into operational dossiers (manufacturing footprint, quality credentials, export footprints and sales channels) and combines these with our demand models for scenario testing.
Next steps and call to action
This introduction is designed to equip leadership with the strategic context necessary for 2026 planning. For teams that require the executable layer — granular supplier scorecards, application-by-application risk matrices, and the downloadable model behind the forecast — access to the full PW Consulting Triclosan Market Report provides the complete evidence base and decision tools. The full report also includes recommended contractual templates, a compliance checklist tailored to affected jurisdictions, and a short-list of tactical suppliers for emergency sourcing.
Contact PW Consulting to schedule a briefing and to obtain the proprietary dataset and model that underpinned the forecasts and recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Triclosan (CAS 3380-34-5) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com