

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ammonium Chloride Market to Hit USD 3,270.49M by 2032 at 4.2% CAGR

Ammonium Chloride Market 2026: Strategic Insights for Decision-Makers
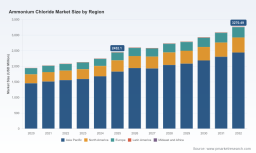
As corporations prepare their strategies for 2026, the ammonium chloride market has moved from a niche commodity narrative to a strategic input that touches agrochemicals, metal finishing, pharma intermediates, and specialty industrial chemistries. PW Consulting’s new market study, anchored on 2025 as the base year, synthesizes five years of historical signals (2020–2025) with a robust forecast to 2032. The headline: the market expanded from under USD 2.0 billion in 2020 to roughly USD 2.45 billion in 2025 and is projected to grow to more than USD 3.2 billion by 2032 at a steady 4.2% CAGR. For C-suite teams, procurement leads, and corporate strategists, this trajectory reframes ammonium chloride from a transactional input to a managed strategic exposure.
Ammonium Chloride Market
Why this study matters for 2026 decision cycles
- Market momentum is measurable and actionable. The compound annual growth rate of approximately 4.2% across the forecast window provides a reliable planning envelope for capex timelines, contract durations, and inventory policies. That stability enables firms to model scenarios with higher confidence compared with other more volatile chemical feedstocks.
- Concentration dynamics create strategic leverage and risk. The market shows mid-level concentration among leading producers, creating opportunities for both incumbent advantage and focused disruption. Buyers negotiating long-term supply or off-take agreements must account for supplier bargaining power and the uneven distribution of capacity.
- Input-cost swings remain the dominant near-term arbitrator of pricing. Recent movements in ammonia and hydrochloric acid—two principal upstream feeds—have driven both margin compression and temporary price dislocations, underscoring the value of integrated sourcing strategies and hedging playbooks.
What the full study delivers (practical, execution-ready content)
PW Consulting’s report is not an academic survey. It is a toolbox for executives who must act in 2026. Key deliverables include:
Ammonium Chloride Market
- Transparent market sizing and a reproducible methodology that traces the market from primary demand drivers to product form (solid vs. solution) and grade (agricultural, industrial, specialty).
- Detailed scenario models (base, upside, downside) that stress-test volume, price, and margin impacts under differing raw material cost paths, regulatory shifts, and demand shocks.
- Supplier landscape mapping and a tactical negotiation playbook: supplier tiering, win-sets for long-term contracts, make-or-buy thresholds, and sample RFP language to capture hidden cost drivers.
- Network & capacity optimisation frameworks, including site-level throughput economics, utilization thresholds that justify debottlenecking, and guidance for small-scale versus brownfield expansions.
- Regulatory and standards impact assessment with compliance checklists for feed, food, and industrial grades—helpful for product labeling, certification, and cross-border trade planning.
- M&A and JV decision support: acquisition target screening criteria, valuation multiples observed in related specialty salts, and integration risk matrices for bolt-on versus greenfield plays.
- Commercial playbooks for product differentiation—how to move from a price-only offering to value capture through formulation services, guaranteed quality grades, and integrated logistics solutions.
Competitive landscape — players to watch and what they signal
The supply side is a mix of global chemical majors, regional conglomerates, and specialized niche manufacturers. Understanding the strategic posture of these players is indispensable for crafting counterparty strategies.
Ammonium Chloride Market
- BASF SE (Ludwigshafen, Germany) — Recently completed a material capacity expansion at its Ludwigshafen site, increasing production capacity by about half and emphasizing enhanced product quality and certified food/feed safety grades. For downstream buyers, BASF’s move signals an intent to defend higher-value segments (certified feed/food grades) while exerting pressure on mid-tier merchants through scale and quality differentiation.
- Tuticorin Alkali Chemicals & Fertilizers Ltd. (Thoothukudi, India) — Operating inside a circular soda ash process and pursuing sizeable capex, this firm illustrates the integrated producer model: co-produced ammonium chloride as part of a broader chemicals slate, enabling cost advantages and flexible product allocation between fertilizer and industrial grades. Their recent audited financials point to robust demand in fertilizer channels and a willingness to invest behind growth.
- Zaclon LLC (Cleveland, USA) — A provider of high-purity solid and solution forms targeted at galvanizing flux and specialty industrial applications. Zaclon represents the smaller, quality-focused competitor that can capture premium margins through product form and service specialization.
- China-based producers and regional exporters — Several large manufacturers employ combined alkali or related processes and participate in standards formulation. Their involvement in national standards and high-volume production positions them as both scale suppliers and standards influencers.
- Mid-sized Indian exporters and specialty manufacturers — Firms focused on pharmaceutical, food, and metalfinishing markets demonstrate the export-led capacity of South Asian producers and the modular, trade-driven nature of the market.
Collectively, these players create a market that is neither atomized nor monopolistic—concentration metrics indicate meaningful clustering among top suppliers while leaving space for regional specialists and value-focused entrants.
Recent developments and their strategic implications
- Capacity additions at major sites and announced greenfield investments have increased supply flexibility. While this supports end-user availability, it also increases the probability of temporary oversupply in specific product grades or geographies—requiring dynamic inventory and pricing strategies.
- Upstream feedstock volatility continues to bifurcate regional cost structures. In Europe, natural gas-driven ammonia cost spikes caused sharp price adjustments; conversely, periods of feedstock price softening have offered relief and prompted competitive pricing tactics. Procurement strategies that incorporate feedstock exposure analytics will materially improve margin protection.
- Regulatory and standards engagement by major producers creates both compliance obligations and opportunities for premium positioning. Certification and validated quality control (especially for food/feed grades) open routes to higher-margin segments but require investment in testing and traceability systems.
Implications for 2026 corporate strategy
For executives drafting 2026 plans, the ammonium chloride market presents several priority action areas:
- Sourcing and contracting: Shorten decision cycles for multi-year supply agreements, include indexation clauses tied to upstream feedstock movements, and build optionality (flex volumes) to navigate cyclical swings.
- Cost and margin management: Implement feedstock-sensitivity analyses at the product line level. Where feasible, pursue vertical integration or closer collaboration with ammonia/HCl suppliers to capture upstream cost benefits.
- Portfolio optimization: Re-assess product-grade mix against margin curves—not all volume is strategic. Allocate investment to grades and forms where your firm can capture value beyond commodity pricing (e.g., certified food/feed grades, specialty galvanizing fluxes).
- Capacity and network play: Prioritize brownfield debottlenecking or modular capacity near key demand hubs to reduce freight intensity and improve responsiveness; consider tolling or captive production for high-variability demand streams.
- M&A and partnerships: With top-tier concentration and regional specialists offering technical differentiation, targeted acquisitions or JVs can deliver rapid access to new grades, certificates, and customer channels.
- Risk management: Build scenario-triggered response plans for raw material dislocations and regulatory shifts. Stress-test balance sheets for price shocks similar to recent ammonia-driven spikes observed in Europe.
Decision frameworks and next steps
PW Consulting recommends that teams use the following pragmatic framework to translate market insight into 2026 actions:
- Stage 1 — Diagnostic (Q1 2026): Run a 48–72 hour rapid market stress test using our scenario templates to quantify P&L exposure under ±20% feedstock swings and two demand-shock scenarios.
- Stage 2 — Tactical (Q2 2026): Rebase procurement strategies and launch targeted RFPs with alternative suppliers, incorporating quality certification and freight-cost pass-through clauses.
- Stage 3 — Strategic (H2 2026): Decide on capacity moves—debottlenecking, brownfield expansions, or M&A—guided by our valuation and integration playbooks. Align capex timelines to the 4.2% CAGR horizon and your firm’s risk tolerance.
About the intelligence edge—and how to use it
This article is a curated preview of PW Consulting’s full ammonium chloride market study. It highlights the contours of growth, the competitive landscape, and the practical actions that matter in 2026. To preserve the strategic value of the full dataset—and to ensure decision-makers benefit from the complete modeling, region-grade split analyses, price decks, supplier scorecards, and financial templates—we intentionally limit the disclosure of granular segment-level figures in this overview.
If your leadership team needs a rapid brief, an execution-ready supplier playbook, or a tailored scenario analysis calibrated to your cost base and sales mix, PW Consulting provides bespoke workshops and live model delivery. Access the full study page to obtain the detailed tables, interactive models, and supplier benchmarking that will enable confident, well-timed decisions in 2026.
For detailed analysis of this topic, please visit the official page: Ammonium Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com