

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Lipstick Market to Hit USD 17.14B by 2032, Rising at 5.5% CAGR

Lipstick Market: Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor, I present a focused preview of our comprehensive Lipstick Market study — the definitive guide for executives making decisive investments, portfolio moves, and regulatory-compliance choices in 2026. This market is no longer a category of mere color and glamour; it is a barometer for consumer sentiment, supply-chain resilience, and regulatory complexity. Our full report (base year 2025, historical window 2020–2025, forecast horizon 2026–2032) synthesizes quantitative forecast models with practical playbooks. Below we surface the strategic takeaways you need now, while preserving the granular segmentation and proprietary datasets for subscribers and direct clients.
Lipstick Market
Why this report matters to 2026 corporate strategy
- Actionable foresight: Our model projects a clear expansion trajectory through 2032 driven by product premiumization, digital channels, and ingredient-driven reformulations. The market expands from approximately USD 11.8 Billion in 2025 to an expected USD 12.8 Billion in 2026, and continues on to just over USD 17 Billion by 2032 under a base-case CAGR of 5.5%.
- Investment signal: The growth rate and absolute expansion validate both organic innovation and bolt-on M&A as viable routes to scale — but only when informed by category-level demand drivers and margin dynamics embedded in our full dataset.
- Risk calibration: Regulatory shifts, tariff regimes, and changing duty classifications are increasing the cost of market entry and cross-border sourcing. Understanding their timing and incidence is essential to avoid margin erosion and inventory write-downs.
High-level market dynamics shaping strategic choices
Three structural forces will dominate executive agendas in 2026:
Lipstick Market
- Regulatory tightening and compliance costs. Recent regulatory actions in major markets — notably the European Commission’s updated cosmetics regulation enacted in 2026 and national-level reform in China — are tightening ingredient lists and claims, creating near-term reformulation costs and mid-term differentiation opportunities for compliant brands. Transitional periods extend into 2028, creating a staging window for product re-engineering and certification strategies.
- Trade friction and input-cost volatility. Geopolitical measures implemented in 2025–2026 — including tariff actions affecting beauty preparations and high-ad valorem duties in some jurisdictions — have materially raised landed costs for certain cross-border product flows. Brands with exposed import-dependent sourcing must reassess their pricing architecture and nearshoring plans now.
- Channel and consumer shifts. Premiumization coexists with value-seeking mass trends; omnichannel performance is increasingly decisive. Luxury launches and beauty-house renewals signal resilient high-end demand, while digital-first players continue to rewrite distribution economics. The resulting polarization requires disciplined SKU and channel investment decisions.
Competitive landscape — what leading players reveal
The category remains semi-consolidated. Our concentration metrics show that the top three brands account for a meaningful share of the market (CR3 ≈ 45%), and the top five increase concentration further (CR5 ≈ 58%). That structure yields both barriers and opportunities:
Lipstick Market
- Incumbent scale and innovation: Large multinational manufacturers continue to dominate through scale manufacturing, brand equity, and distribution networks. Firms with strong global portfolios retain the capability to amortize reformulation costs and to push premium launches into selective channels.
- Luxury differentiation: High-end houses are proving that design, packaging, and storytelling sustain price premiums. Recent ultra-luxury launches reinforce that the top-end remains a strategic growth corridor, particularly for companies willing to invest in bespoke formulations and vertical brand experiences.
- Mid-market and niche plays: Agile players focusing on professional-grade formulations or on trend-led digital campaigns can extract disproportionate returns in segmented micro-markets — provided they manage regulatory and supply-chain complexity effectively.
Representative corporate moves and implications (selective, illustrative):
- Large beauty groups continue to deploy multi-brand strategies that span mass, prestige, and professional channels — leveraging centralized R&D and global supply footprints to accelerate new launches.
- Luxury houses are investing in product narratives and limited-edition collections, demonstrating that scarcity and craftsmanship can justify elevated price points even in a cost-conscious environment.
- Third-party certifications and independent lab reporting (recent industry lab publications) are becoming de facto trust signals for consumers and retailers; brands that pre-emptively validate claims gain distribution advantages.
Regulatory and trade developments to prioritize
Regulation and trade decisions in 2025–2026 materially change compliance cost curves and market-access strategies:
- Ingredient restrictions and transitional timelines in Europe mandate an immediate audit of product portfolios and claims. Firms must map ingredient exposures and implement staged reformulations aligned with enforcement dates.
- Tariff and duty regimes in North American and other markets have tightened, affecting landed costs for specific inputs and finished goods. Pricing models should incorporate scenario-based duty impacts to avoid margin surprises.
- China’s updated cosmetics regulatory framework streamlines certain registration processes but heightens scrutiny on efficacy claims — making cross-market label harmonization and regulatory intelligence essential for global players.
What our full report contains — practical deliverables for 2026 decisions
The study is built for executives who need to act. Highlights of the deliverables you will find in the complete report include:
- Robust market model: Time-series market sizing (2020–2025 actuals), base-year 2025 calibration, and a scenario-based forecast through 2032, underpinned by channel- and price-tier elasticity assumptions. (We present high-level aggregates above; proprietary segmentation tables and interactive models are available in the full package.)
- Regulatory playbook: Itemized ingredient and claims exposure matrices cross-referenced to enforcement timelines and practical reformulation pathways, plus supplier and testing options to de-risk compliance projects.
- Supply-chain diagnostic: Impact assessment of tariff scenarios and alternative sourcing maps, with recommended nearshoring and inventory strategies to protect gross margins under trade shocks.
- Go-to-market toolkit: SKU rationalization frameworks, pricing ladders, omnichannel merchandising plans, and a digital-conversion checklist tailored by retailer type and consumer cohort.
- M&A and partnership screening: Criteria and a short-list of industrial targets and capability partners (manufacturing, ingredient specialists, certification bodies) aligned to strategic objectives such as premiumization or clean-beauty credentials.
Strategic implications and recommended moves for 2026
Based on our integrated model and field interviews, we recommend the following priority actions for market participants in 2026:
- Conduct a rapid compliance triage. Within 90 days, map all SKUs against new ingredient restrictions and create a phased reformulation calendar that aligns production cycles and retail windows.
- Reconfigure sourcing by risk tier. Shift strategic volumes to lower-tariff or nearshore suppliers where economic math supports the move; reserve premium import strategies for differentiated SKUs that can sustain price premiums.
- Rationalize SKU portfolios and re-invest savings. Eliminate low-rotation SKUs and redeploy margin gains into high-growth formats (e.g., premium finishes, refillable systems, or limited-edition luxury drops) and into digital acquisition channels.
- Invest in independent verification. Certification, lab testing, and transparent traceability are increasingly table stakes for distribution agreements and consumer trust — budget for external validation as part of product launch costs.
- Pursue selective partnerships. Consider contract manufacturing agreements, co-branding deals with prestige houses, or acquisitions that add ingredient or testing capabilities to reduce compliance risk.
Final note — what’s behind the curtain
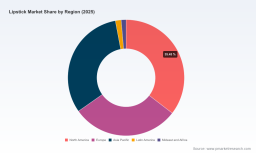
This preview surfaces the macro trends, competitive posture, and regulatory inflection points you must factor into 2026 planning. The full PW Consulting Lipstick Market report contains the granular segmentation, channel-by-channel revenue models, and proprietary scores that operational teams need to execute confidently. We purposefully withhold detailed segment-by-region figures and SKU-level shares in this public summary to preserve the analytical integrity and commercial value of the source datasets.
To translate these insights into a tailored 90‑day playbook for your business — including scenario-run forecasts under specific tariff and regulation outcomes — contact PW Consulting. Our clients get the full model, implementation templates, and a focused executive workshop to convert strategy into measurable results.
For detailed analysis of this topic, please visit the official page: Lipstick Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com