

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Market Insights: Hazardous Chemical Warehousing and Logistics Market Set to Expand at a 6.12% CAGR Through 2032

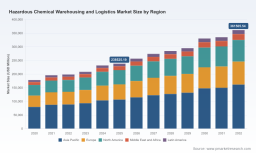
Hazardous Chemical Warehousing And Logistics Market — Strategic Briefing for 2026 Decisions
PW Consulting’s new market research briefing on Hazardous Chemical Warehousing and Logistics delivers a focused, decision-ready view for executives planning capital, procurement, safety, and commercial strategies in 2026. The global market has expanded materially through the pandemic recovery period and supply‑chain reconfiguration: from approximately 178,240.5 Million USD in 2020 to an estimated 238,525.19 Million USD in 2025. Under our central forecast, the market will continue to grow at a compound annual growth rate of 6.12% over the 2026–2032 horizon, reaching roughly 361,505.54 Million USD by 2032. This briefing explains why those headline numbers matter for boardroom choices next year, what pragmatic content the full report contains, and the strategic actions that separate winners from laggards in a fragmented market.
Hazardous Chemical Warehousing And Logistics Market
Why 2026 is a strategic inflection point
-
Regulatory catalysts are accelerating capital and operating decisions. Multiple international and national rules became effective or were updated for 2026, including major amendments to air, sea and road dangerous‑goods codes and evolving U.S. harmonization initiatives. Compliance programs that were “good enough” in 2024–25 need remediation in 2026, and that creates windows for service providers with certified capabilities to win share.
Hazardous Chemical Warehousing And Logistics Market -
Market growth and fragmentation are creating selective scale advantages. The market’s trajectory to 2032 reflects steady demand for safer, more traceable chemical flows and greater appetite for specialized warehousing. At the same time, concentration metrics show industry fragmentation — the top players account for a relatively small share of global volumes — meaning local specialists and new technology-led players can meaningfully displace incumbent relationships if they deliver demonstrable safety and cost benefits.
Hazardous Chemical Warehousing And Logistics Market -
Decarbonization and modal shifts are reshaping asset and network requirements. Investments in alternative fuels (including certified hydrogen transport pilots), intermodal tank container solutions, and electrified handling equipment are shifting CAPEX priorities and altering operating cost curves for chemical logistics providers.
What PW Consulting’s full report delivers (practical, implementable content)
-
Executive playbook: a prioritized set of strategic moves tailored for shippers, 3PLs, and terminal owners — from short‑term operational fixes to medium‑term network redesign and long‑term capability build.
-
Macro market sizing and forecast model: transparent, auditable projections for 2020–2032 (headline figures are summarized above). The interactive model in the full report allows you to stress‑test demand scenarios and CAPEX timelines against commodity and regulatory shocks.
-
Compliance and regulatory matrix: a practical mapping of new and revised standards (air, sea, road, workplace) and the operational checklist required for 2026‑compliant handling, storage, labeling, and employee training.
-
Operations toolkit: facility design checklists for classifying and segregating hazardous stocks, recommended storage capacity buffers, ventilation and secondary containment templates, and sample SOPs for multimodal transits and tank handling.
-
Commercial and procurement templates: vendor scorecards, RFP language for hazardous warehousing and transport, contract clauses for liability and DR/BCP, and benchmarking KPIs for safety, fill rates, and dwell time.
-
Technology and digitalization use cases: capex/opex impact estimates for real‑time tracking, telematics, automated gate/yard solutions, and sample approaches for integrating dangerous‑goods rules into TMS/WMS systems.
-
Deal and M&A playbook: a focused section on acquisition targets, valuation levers, and integration risks when adding hazardous‑goods warehousing to a logistics portfolio — with diligence checklists specific to regulatory compliance and insurance exposure.
Note: consistent with our “trailer” approach, this public briefing highlights the report’s scope and actionable outputs while withholding the proprietary, segment‑level revenue splits and certain unit economics to encourage direct engagement with PW Consulting for full datasets and models.
Competitive landscape — capabilities that matter in 2026
-
DHL Supply Chain (Germany) — Specialized hazardous chemical warehousing and multimodal logistics with hazmat‑certified facilities and real‑time dangerous‑goods tracking. Their compliance breadth across ADR, IMDG and IATA positions them to capture customers prioritizing global standardization.
-
DB Schenker (Germany) — Comprehensive hazardous goods logistics emphasizing European ADR compliance, tank container transport, and strong road/rail coverage — attractive for shippers optimizing intra‑European flows.
-
Kuehne + Nagel (Switzerland) — Integrated chemical logistics solutions combining specialized warehousing, tank storage, and sustainability commitments, appealing to multinationals seeking single‑vendor supply‑chain simplification.
-
DSV (Denmark) — Hazmat warehousing and logistics with an operational focus on flammable, corrosive and toxic substances and full alignment with international dangerous‑goods codes.
-
CEVA Logistics (France) — Certified facilities and integrated supply‑chain management for the chemical sector — a competitive provider for distribution‑heavy requirements.
-
Rhenus Logistics (Germany) — Specialized storage, packaging and multimodal transport solutions that target regulated chemical flows with local presence in key hubs.
-
Bertschi AG (Switzerland) — Intermodal tank container specialist focused on bulk liquids and hazardous‑liquid transport, offering niche capabilities for liquid chemistry supply chains.
-
Hoyer Group (Germany) — Tank container logistics and dedicated warehousing for liquid chemicals and gases, valuable for shippers needing global connectivity.
-
Agility Logistics (Kuwait) — Offers hazardous materials logistics across emerging markets; local market knowledge supports growth in developing chemical demand centers.
-
C.H. Robinson (USA) — Technology‑forward provider with advanced tracking and safety tech suited to customers seeking visibility and liability mitigation.
-
Odyssey Logistics & Technology Corporation (USA) — Specialist in chemical sample fulfillment and hazardous warehousing, recently expanding via acquisition to broaden global coverage.
-
Rinchem Company LLC (USA) — Provides dedicated hazmat and temperature‑controlled warehousing combined with hazardous transport capabilities for sensitive chemicals.
-
Univar Solutions LLC (USA) — Chemical distribution and specialized storage services, well‑positioned for integrated distribution and inventory management solutions.
-
BRENNTAG (Germany) — A leading distributor with deep hazardous‑materials warehousing expertise and an extensive regional footprint.
-
ALFRED TALKE GmbH & Co. KG (Germany) — Focused chemical logistics and dedicated hazardous goods warehousing with a safety and compliance orientation.
Recent market moves illustrate how capability gaps are being filled quickly: certification pilots for hydrogen trucks in Europe; new ISO tank rail services for bulk liquids; launches of liquid chemical vessels; targeted acquisitions expanding fulfillment networks; and rapid deployment of advanced tracking and safety systems. These examples are early indicators of which providers will scale differentiated offers into 2026.
Regulatory inflection points and operational implications
-
Air and sea rule updates: The IATA 67th edition and the latest IMDG amendment (effective 2026) introduce changes that affect classification, labeling and shipment preparation. Shippers and 3PLs must update TMS/WMS controls and training protocols immediately to avoid costly detention and rework.
-
Road transport harmonization: Europe’s ADR 2025 is fully operative and continues to evolve around battery and tank inspection standards. Road carriers and warehousing operators must confirm vehicle and facility compliance to maintain cross‑border operations.
-
Workplace and U.S. rulemaking: OSHA updates and PHMSA’s harmonization proposals require operational changes to labeling, PPE, and shipping‑name alignment. For U.S. operations, comments and compliance timelines create both risk and a chance to influence final rules.
Practical strategic moves for leaders in 2026
-
Rapidly prioritize compliance CAPEX to avoid interruption: convert short‑list facilities to certified hazmat handling status and standardize training across the network.
-
Invest selectively in visibility and automation: real‑time tracking reduces dwell time penalties and enhances traffic lane tenders; automated gate/yard systems improve throughput while lowering HSE incidents.
-
Pursue targeted partnerships and bolt‑on M&A: acquire or partner with tank‑container specialists and regional hazardous‑goods warehousing providers to stitch together global coverage without overbuilding CAPEX.
-
Embed sustainability as a competitive requirement: demonstrate low‑carbon modal mixes, alternative‑fuel pilots, and certified hydrogen transport capabilities to win procurement mandates tied to ESG goals.
-
Restructure commercial agreements to allocate regulatory risk: update RFPs and contracts to reflect the cost of compliance changes and to secure predictable pricing amid evolving rules.
How to use this briefing in your 2026 planning
Use the headline market sizing and growth trajectory presented here to validate strategic bets: is your organization positioned to capture share from an expanding but fragmented market? The full PW Consulting report supplies the segmented figures, regional dynamics, service‑type economics, proprietary vendor scorecards, and the interactive models referenced above — all designed to be dropped into boardroom planning sessions, capital allocation spreadsheets, and procurement negotiations.
This release is intentionally a preview: it demonstrates the analytical depth and operational orientation of our work while withholding the granular, proprietary subsegment tables and unit‑economics that executives need to finalize budgets. For teams preparing 2026 budgets, RFPs, or M&A pipelines, the full dataset and customized briefings are available through PW Consulting’s report portal and advisory services.
To move from strategy to execution in 2026, organizations must align compliance programs, upgrade digital controls, and selectively invest in certified, resilient capacity. PW Consulting’s Hazardous Chemical Warehousing and Logistics Market report provides the maps, tools, and templates to do exactly that — and the full intelligence package is the next step for decision makers who cannot afford to wait.
For detailed analysis of this topic, please visit the official page: Hazardous Chemical Warehousing And Logistics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com