

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Diphenylmethanol Market Poised to Expand at 4.78% CAGR Through 2032, New Insight Shows

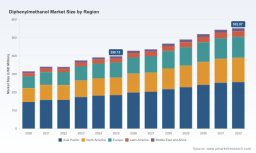
Diphenylmethanol Market — 2026 Strategic Preview
PW Consulting’s latest Diphenylmethanol Market report delivers a focused, decision-grade briefing designed for executives preparing for 2026. Anchored on a 2025 base-year assessment and a 2026–2032 forecast window, the study quantifies the near-term expansion trajectory (projected compound annual growth rate of 4.78%) and translates this into operational, commercial, and M&A insights that leaders can act on immediately. This preview outlines the report’s strategic value while intentionally holding back proprietary segment-level datasets — the exact figures, regional and application splits, and granular price curves remain available in the full report.
Diphenylmethanol Market
Why this market matters to 2026 decision-making
-
Diphenylmethanol (benzhydrol) occupies a critical position as a specialty intermediate used across pharmaceuticals, agrochemicals, and fragrance chemistries. Our 2025 base sizing and 2026 forecast highlight steady growth with clear pockets of premium demand driven by pharmaceutical-grade requirements and formulation-grade specifications.
Diphenylmethanol Market -
The market’s mid-single-digit forecast CAGR converges with broader specialty-chemical trends: steady demand, selective premiumization, and supply-chain sensitivity around upstream feedstocks. For procurement, operations, and corporate development teams, these dynamics necessitate tactical sourcing, selective capacity investments, and playbooks for resilience.
Diphenylmethanol Market -
Beyond headline growth, the market demonstrates a mixed structural profile — a meaningful presence of established, high-purity global suppliers alongside a vibrant base of regional manufacturers and custom-synthesis providers. Reported concentration metrics indicate moderate clustering among top players (three-firm and five-firm concentration indices are material inputs in our competitive assessment), which has direct implications for pricing power and consolidation strategies.
What the report delivers — operational modules for 2026
-
Practical market-sizing and forecasting: validated base-year metrics, scenario-driven forecasts (base, upside, stress), and sensitivity analysis tailored for procurement and capex planning.
-
Go-to-market and procurement playbook: supplier scorecards, qualification checklists for pharmaceutical versus technical grades, contracting templates, and dual-sourcing frameworks that reduce single-source exposure without eroding margin.
-
Supply-chain and feedstock risk map: upstream dependency analysis (benzophenone-centric feedstock risk), lead-time benchmarking, and inventory optimization models for lean and resilient strategies.
-
Technology and process assessment: comparison of commercial reduction routes (catalytic hydrogenation; metal-reduction methods using aluminum, zinc, or other reagents), energy and CAPEX implications, and recommendations for greener hydrogenation adoption where decarbonization yields cost or credential advantages.
-
Regulatory & safety dossier: distilled interpretation of CLP classifications, workplace exposure mitigation, and compliance checklists for cross-jurisdictional shipments — essential for firms scaling exports or registering new product grades.
-
Commercial intelligence: pricing trend frameworks, distribution channel economics, and a playbook for premiumization (how to capture pharma-grade premiums through QA/QC and supply agreements).
-
M&A and partnership roadmap: target screening criteria, synergies quantification templates (cost, capability, and market access), and regulatory considerations for cross-border transactions.
Market dynamics and strategic implications
-
Demand composition: the chemical’s role as an intermediate for antihistamines, antispasmodics, agrochemical active ingredients, and fragrance building blocks underpins a diversified end-use profile. This mix smooths demand cyclicality but also creates bifurcated quality requirements — high-purity pharma grades versus robust technical grades — each requiring distinct manufacturing controls, testing protocols, and documentation.
-
Upstream feedstock concentration: benzophenone is the principal upstream feedstock. Our field validation confirms that producers relying on a limited set of benzophenone suppliers face outsized exposure in events that constrain supply or spike feedstock prices. Firms evaluating capacity additions should model feedstock integration (procure vs. vertically integrate) as a primary sensitivity in NPV analyses.
-
Manufacturing routes and CapEx trade-offs: proven reduction chemistries — including catalytic hydrogenation and metal-reduction approaches (e.g., aluminum/caustic in alcohols, zinc reductions) — present clear trade-offs between operating cost, safety profile, capital intensity, and environmental footprint. The report’s techno-economic appendix quantifies these trade-offs and recommends technology choices by scale and target grade.
-
Regulatory positioning: Diphenylmethanol is classified under CLP with specific hazard statements (skin and eye irritation, and potential respiratory effects). It is not currently captured in restricted-substance lists that would require higher authorization in the jurisdictions we surveyed, which eases near-term market access but does not obviate the need for robust occupational health programs and transport compliance.
Competitive landscape — profiles and tactical takeaways
-
Supplier diversity spans three archetypes: (1) global laboratory and reagent suppliers providing ultra-high-purity, certified standards; (2) regional manufacturers and exporters supplying industrial and specialty grades; and (3) custom-synthesis partners offering kilogram-to-tonne scale-up services and small-batch, high-value production. Each archetype maps to distinct go-to-market tactics and margin expectations.
-
Representative companies in our competitive mapping illustrate these archetypes. Global lab suppliers specialize in certified, high-purity packs for research and regulated production; regional producers — notably industrial clusters in South Asia and specialty sites in East Asia — deliver cost-competitive volume and customization; custom synthesis firms provide rapid prototyping, scale-up and high-purity intermediates for smaller pharma programs. The full report contains anonymized benchmarking and supplier scorecards tailored for sourcing teams.
-
Concentration insight: top-tier sellers account for a significant, but not dominant share of market capacity. This creates opportunities for disciplined mid-sized players to capture share through targeted quality upgrades, geographic diversification, and service-based differentiation (e.g., regulatory support for global customers).
Actionable recommendations for 2026
-
Procurement & supply security: institute layered contracts (short-term capacity bookings + long-term offtake options) with clear quality gates. Require traceability to benzophenone feedstock and supplier contingency clauses tied to lead-time performance.
-
Manufacturing strategy: favor modular investments that allow switching between hydrogenation and metal-reduction processes at pilot scale. Where regulatory and customer expectations justify, prioritize investments toward cleaner hydrogenation pathways that may yield both environmental and marketing advantages.
-
Product & portfolio: create a two-track product roadmap — preserve high-margin pharma-grade supply through certified manufacturing pathways and extend technical-grade offerings through regional partners to manage cost-to-serve.
-
M&A and partnerships: prioritize bolt-on acquisitions that add missing capabilities (analytical QC, regulatory dossiers, or regional warehousing). Small to mid-sized producers with established export infrastructure and GMP-capable lines are especially attractive as quick access points into under-penetrated end-use markets.
-
Risk and compliance: elevate CLP hazard management into supplier audits and customer specifications, and embed occupational exposure limits into facility design and contractual warranties for third-party manufacturers.
How PW Consulting’s report supports 2026 execution
-
Turnkey decision support: leadership-ready slide decks, scenario models (sensitivity to feedstock price and lead times), and procurement scorecards to accelerate board-level and commercial decisions.
-
Action kits: supplier RFP templates, technical due-diligence checklists, and M&A valuation multipliers calibrated to diphenylmethanol’s commercial dynamics and grade differentials.
-
Confidential appendices: proprietary price-band analytics, granular regional and application splits, and a ranked list of near-term acquisition targets. These datasets are intentionally gated in the full report so clients can access the precise inputs needed for contracting and valuation exercises.
In short, the Diphenylmethanol Market is neither a commodity drift nor an untouchable niche — it is a specialty intermediate market with predictable growth, defined quality bifurcation, and tangible operational levers for those who act now. For procurement leads, plant managers, BD teams, and PE sponsors planning allocations in 2026, PW Consulting’s report converts market signals into executable steps: where to negotiate, where to invest, and where to partner.
To access the complete dataset, supplier scorecards, and the full suite of practical tools referenced above, visit PW Consulting’s report page and request the Diphenylmethanol Market full report and executive toolkit.
For detailed analysis of this topic, please visit the official page: Diphenylmethanol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com