

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Market Insights: Fluid Management Systems Poised for 6.69% CAGR in 2026–2032 Forecast

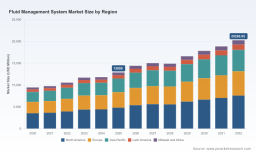
Fluid Management System Market: A Strategic Briefing for 2026 Decision-Makers
As healthcare providers, device OEMs, and industrial-services operators enter 2026, the Fluid Management System market is transitioning from steady expansion to strategic inflection. PW Consulting’s latest market study—anchored on a comprehensive historical review (2020–2025) and a rigorous forecast (2026–2032)—shows the market growing from roughly USD 9.45 billion in 2020 to USD 12.88 billion in 2025, and projected to reach approximately USD 20.27 billion by 2032, representing a compound annual growth rate (CAGR) of 6.69% over the forecast window. These topline dynamics conceal important structural shifts: consolidation among leading players, accelerating digital integration, and supply-chain sensitivities tied to specialized polymer and tubing supply. This release outlines the strategic value of the report for executives planning initiatives in 2026 while preserving the granular segmentation that clients obtain from the full research package.
Fluid Management System Market
Why this intelligence matters for 2026 planning
-
Decisive capital allocation: With market expansion accelerating into the late-2020s, capital planners must identify which product archetypes and commercialization models will compound return on invested capital. Our report quantifies TAM trajectory and models five investment scenarios to stress-test portfolio choices against regulatory and reimbursement contingencies.
Fluid Management System Market -
Portfolio prioritization under uncertainty: The market’s moderate concentration (CR3 ≈ 42.5%; CR5 ≈ 58.2%) signals room for both scale players and focused challengers. We translate competitive positioning into clear “defend, divest, double-down” recommendations for 2026–2028 horizons.
Fluid Management System Market -
Regulatory and go-to-market readiness: Recent clearances and launches — including a U.S. regulatory milestone in early 2026 and multiple product introductions across medical and industrial verticals — mean first-mover advantages can be decisive. The report provides playbooks for regulatory filing strategies and rollout sequencing optimized for 2026 timelines.
-
Supply chain and sourcing resilience: Dependence on specialized polymers and biocompatible tubing is a recurring operational risk. The report delivers a prioritized supplier map and a set of mitigation actions to insulate production and margins during component bottlenecks.
What the full PW Consulting report delivers (practical, actionable content)
-
Robust market-sizing and forecast model (2020–2032) with transparent methodology, sensitivity scenarios and downloadable model files for client stress-testing.
-
Demand-driver decomposition that quantifies the influence of minimally invasive procedure rates, hospital capital spending cycles, and outpatient-shift dynamics on market growth.
-
Technology deep dives into integrated vs. standalone platforms, disposables economics, and digital fluid-tracking systems—each accompanied by cost-to-serve benchmarks and margin simulations.
-
Regulatory roadmap and checklist tailored to North American, European and APAC pathways, including submission timelines, evidence packages and post-market surveillance strategies.
-
Competitive benchmark suite: strategic profiles, product portfolios, patent landscaping, recent investment and M&A pipelines, and scenario-based rivalry forecasts.
-
Commercial playbooks: value-based pricing frameworks, channel and service models, tender and hospital procurement strategies, and pilot design templates for rapid validation.
-
Deal and partnership blueprints: target screening criteria, integration risk checklists, and valuation sensitivity tables to support M&A and licensing decisions.
Market dynamics shaping 2026 strategy
-
Minimally invasive procedures are the structural growth engine. Demand for precise inflow/outflow control and integrated visualization is propelling investment in platforms that can deliver better procedural outcomes while optimizing OR throughput.
-
Digitalization is migrating from additive capability to core value-driver. New entrants and incumbents are embedding telemetry, usage analytics and digital consumables management into field-service and clinical workflows—a shift illustrated by recent product rollouts that emphasize wireless tracking and mobile dispensing.
-
Consumables-led business models are gaining prominence. The lifecycle economics of disposables and accessories increasingly determine platform adoption; therefore, decisions about modular vs. fully integrated systems will shape recurring-revenue potential.
-
Material and manufacturing constraints are material. Medical-grade polymers and precision tubing remain critical inputs. Firms with diversified sourcing, in-sourced extrusion capabilities, or long-term supplier agreements are positioned to protect gross margin in a tightening supply environment.
-
Regulatory activity is concentrated and consequential. Early-2026 clearances for clinical-use systems underscore the advantage of proactive regulatory strategies that combine clinical data design with targeted submission timing.
Competitive landscape: who matters and what they imply for strategy
The sector comprises a mix of global medtech leaders, specialized surgical OEMs, industrial fluid-systems players and healthcare-focused service providers. Market concentration metrics point to an oligopolistic center and a long tail of niche specialists. Below, we summarize strategic postures of core players included in our analysis and the implications for competitors and partners.
-
Stryker Corporation (Kalamazoo, MI, USA — https://www.stryker.com): Strength in integrated surgical platforms and recent launches that bundle scopes with fluid systems indicate a platform-led push to lock-in clinical workflows. Implication: competitors must match platform integration or create compelling open-system economics.
-
Baxter International Inc. (Deerfield, IL, USA — https://www.baxter.com): Broad hospital-care footprint and monitoring solutions make Baxter a strategic anchor for perioperative and critical-care fluid management offerings. Implication: partnerships between device OEMs and clinical-monitoring providers can accelerate adoption in hospital systems.
-
B. Braun Melsungen AG (Melsungen, Germany — https://www.bbraun.com): Depth in irrigation and suction systems for surgical applications highlights an installed-base advantage in procedure rooms.
-
Medtronic plc (Dublin, Ireland — https://www.medtronic.com): Focused development for gynecologic and hysteroscopy procedures shows how procedure-specific optimization can capture clinical preference and purchasing decisions.
-
Fresenius Medical Care (Bad Homburg, Germany — https://www.freseniusmedicalcare.com): Dominant in renal dialysis platforms; demonstrates the value of specialized, high-utilization clinical devices for steady recurring revenue.
-
CONMED, Hologic, Olympus, Karl Storz, Boston Scientific, Cardinal Health, Smith & Nephew, Ecolab and Graco: each offers complementary strengths—from arthroscopy fluid control to industrial field-dispensing systems—creating a competitive mosaic where cross-sector partnerships and selective M&A can unlock scale and distribution advantages.
Recent developments to watch (strategic implications)
-
Regulatory wins and product launches in early 2026 accelerate clinical adoption curves—firms that can couple regulatory readiness with rapid commercial rollout will capture disproportionate share gains.
-
Industrial entrants bringing digital field-dispensing solutions (e.g., wireless mobile tracking) are broadening the definition of fluid management and creating white-space for service-led business models beyond the OR.
-
Patents and IP around fluid metering, closed-loop control and disposable interfaces are differentiators; IP landscaping in the report quantifies freedom-to-operate risks and licensing opportunities.
Five strategic moves for 2026 (priority checklist)
-
Prioritize platform economics: Evaluate shifting R&D spend from incremental hardware improvements toward integrated software, consumables and analytics that create recurring revenue.
-
Lock supply and diversify materials sources: Secure long-lead polymer and tubing contracts, and validate secondary suppliers to hedge manufacturing risk.
-
Execute targeted regulatory sequencing: For companies with multi-procedure portfolios, prioritize submissions that unlock the greatest near-term adoption and reimbursement benefits.
-
Accelerate service and digital propositions: Pilot digital fluid-tracking and remote service offers to demonstrate TCO reductions for hospital partners and create stickier customer relationships.
-
Scan for tuck-ins and capability buys: Use M&A selectively to acquire consumables franchises, digital telemetry capabilities or regional distribution footprints—our report provides a prioritized shortlist and valuation framework.
How PW Consulting helps clients convert insight into value
-
Custom scenario modeling and portfolio optimization workshops to convert forecast scenarios into actionable capital and R&D plans.
-
Due-diligence and integration support for M&A, including synergy-target validation and integration playbooks tailored to fluid-management assets.
-
Regulatory and clinical strategy advisory: dossier design, evidence generation sequencing and post-market surveillance planning.
-
Commercial performance uplift programs: pricing pilots, bundle designs, and hospital procurement negotiation support.
We intentionally withhold segmented regional and application-level figures from this public briefing to preserve the value of the full report and to encourage stakeholders to engage directly with our analysts for tailored insights. For executives building 2026 strategy—whether allocating R&D budgets, sizing M&A firepower, or launching next-generation platforms—PW Consulting’s Fluid Management System market study provides the data, diagnostics and actionable playbooks required to capture the upside in a market growing at a mid-single-digit CAGR and undergoing rapid technological and commercial evolution. Contact PW Consulting to access the full report, the downloadable model and a complimentary strategy workshop tailored to your organization’s objectives for 2026.
For detailed analysis of this topic, please visit the official page: Fluid Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com