

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: One‑Stop Collaboration Platform Market Set to Reach USD 179,000 Million by 2032 on a 12.48% CAGR — Cloud‑Based Solutions Lead with USD 68,378M in 2025

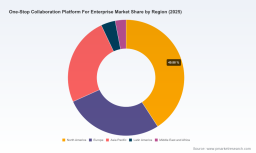
One Stop Collaboration Platform for Enterprise Market — Strategic Briefing for 2026 Decisions
Executive teaser
As enterprises enter a decisive phase of digital workplace transformation in 2026, PW Consulting’s new market study — One Stop Collaboration Platform For Enterprise Market — translates market dynamics into actionable strategy. The enterprise collaboration market has moved from a rapid adoption phase into scale and optimization: our analysis finds the market reached approximately USD 78,500 Million in 2025 and, driven by AI-enabled functionality, hybrid-work investments, and cloud-first deployments, is forecast to expand at a compound annual growth rate (CAGR) of 12.48% through 2032, approaching USD 179,000 Million by the forecast horizon. Market concentration is material: the top three vendors account for a majority share and the top five for a pronounced portion of revenue, shaping competitive dynamics and negotiation leverage for enterprise buyers.
One Stop Collaboration Platform For Enterprise Market
What this report delivers — operational intelligence for 2026
- Rigorous market sizing and scenario modelling grounded in 2020–2025 historical trends, with demand-driver sensitivity analyses that translate macro assumptions into procurement outcomes for buyers and product roadmaps for vendors.
- Vendor capability maps and quadrant-style evaluations that benchmark platform breadth (communications, document collaboration, workflows, integrations), depth (security, admin controls, compliance), and extensibility (APIs, app marketplaces, developer ecosystems).
- Practical procurement & implementation artifacts: RFP templates, TCO and migration calculators, pilot design blueprints, and technical validation checklists tailored for cloud, hybrid, and on‑premise architectures.
- Compliance and risk playbooks that map evolving privacy and regulatory obligations — including the expanded California privacy rules effective in 2026, advancing state frameworks in the U.S., and intensified GDPR enforcement — to vendor contract clauses, data residency options, and ADMT (automated decision-making technology) considerations.
- Go-to-market and M&A readiness frameworks for vendors and integrators: segmentation strategies, partner ecosystem models, and acquisition due‑diligence scorecards focused on IP, data flows, and integration debt.
- Case studies and success metrics from enterprise pilots, illustrating measurable productivity uplifts, meeting-cost reductions, and governance trade-offs across industry archetypes.
Key strategic implications for enterprise decision-makers in 2026
1) Consolidation versus best-of-breed is a calibrated choice. The market’s scale and concentration create compelling efficiencies in consolidating to a single vendor ecosystem — improved admin, unified identity, and bundled licensing — but the premium for ecosystem lock-in requires a clear business case. Organizations should quantify switching and exit costs, data portability constraints, and long-term innovation exposure before committing to a single platform.
One Stop Collaboration Platform For Enterprise Market
2) AI transitions from novelty to operational requirement. Vendors are embedding generative and assistive AI across meeting summaries, action-item extraction, intelligent routing, and automated workflow generation. These AI features materially influence buyer choice but introduce new governance needs: model provenance, logging, consent for automated decisioning, and vendor commitments on hallucination controls and fine-tuning.
One Stop Collaboration Platform For Enterprise Market
3) Cloud economics and hosting strategy are increasingly strategic. Public cloud expenditure remains a dominant cost vector for collaboration platforms — influencing latency, resilience, and security posture. While cloud-first deployments drive rapid feature availability, hybrid and selective on‑prem deployments persist where data sovereignty, latency, or regulatory constraints are binding. Our TCO models demonstrate that cloud hosting costs can exceed license fees at scale unless optimized through usage governance and architectural choices.
4) Regulatory momentum changes procurement minimums. New privacy rules effective in 2026 require risk assessments, auditability, and clearer consent flows for ADMT. The proliferation of state-level privacy laws and renewed GDPR enforcement means vendor contracts must deliver specific commitments on data minimization, processor obligations, subprocessors, and cross-border transfer mechanisms.
5) Hybrid work drives differentiated room and endpoint strategies. Investment is shifting from basic conferencing licenses toward intelligent room systems, integrations with scheduling and booking, and UX consistency across remote and colocated participants. This creates an opportunity for specialized hardware partners and integrators to add value within platform ecosystems.
Competitive landscape — what buyers must know about leading suppliers
The vendor field is mature and strategically diverse. A few high-level positions to inform vendor selection:
- Large platform incumbents have doubled down on integrated suites and AI. One vendor’s deep integration with its productivity suite and continued rollout of Copilot-style capabilities strengthens its proposition as a one-stop choice for enterprises prioritizing unified identity and admin simplicity.
- Channel- and app-centric platforms retain strong appeal for organizations valuing modularity and best-of-breed workflows. These suppliers emphasize developer ecosystems, rich third-party integrations, and lightweight admin models that accelerate departmental adoption.
- Communications-first vendors continue to compete on reliability, meeting scale, and telephony features; their value is strongest where real-time media quality and contact-center convergence are strategic priorities.
- Project- and task-focused suites provide the workflow backbone for cross-functional teams; they are increasingly interoperable with comms platforms through APIs and native connectors, blurring traditional category boundaries.
- Regional and vertically focused vendors are winning niche deals where localized compliance, language, and vertical workflows matter more than global scale.
Recent product and ecosystem moves sharpen these dynamics: advanced AI feature expansions across major suites in late 2025, targeted product updates that introduce AI agents and visualization widgets in leading work-management platforms, and hybrid-room hardware showcases at industry events. Buyers should interpret these updates not as feature skirmishes but as strategic bets on where vendors will monetize and differentiate over the next 24 months.
Priority actions for procurement, IT, and business leaders
- Establish an executive governance forum for collaboration strategy that spans HR, IT, legal, and finance. This reduces stove‑piped pilots and aligns measurement of productivity, security, and cost.
- Adopt a vendor-evaluation framework that weights interoperability (data egress, APIs), AI safety (explainability, model controls), and compliance (processor clauses, audit rights) as heavily as feature parity and price.
- Run staged pilots with clear success metrics: start with cross-functional cohorts, instrument outcomes at the workflow level (time-to-decision, meeting hours, task completion), and evaluate dilution effects on specialized tools.
- Operationalize privacy and AI risk assessments into procurement checkpoints. Require vendors to disclose ADMT use, provide model-risk mitigation clauses, and commit to contractual SLAs for data handling and incident response.
- Optimize cloud spend through usage governance: adopt policy-driven provisioning, meeting-capacity throttles, and archive strategies that reduce persistent storage and streaming costs.
- Plan for exit and data portability from day one: capture export testing in acceptance criteria and negotiate standardized data formats in contracts to mitigate future migration friction.
How to use the full report — what we intentionally defer in this preview
This briefing is designed as a strategic preview: it highlights high-impact conclusions and operational actions but intentionally omits the granular segmentation tables, regional and vertical percentage splits, vendor-by-feature scorecards with their numeric weights, and the full set of pricing and TCO line items. Those detailed intelligence artifacts — the ones procurement teams and deal negotiators rely on — are compiled in the full PW Consulting report, which also includes downloadable RFP templates, executable pilot scripts, and our bespoke migration cost model.
Closing: the 2026 inflection point
For enterprise leaders the coming 12–18 months represent an inflection point: platforms will no longer be selected simply on feature completeness but on an ability to safely accelerate work, control cloud economics, and meet rising compliance obligations. The market’s strong growth trajectory and concentrated competitive structure mean that strategic vendor choices today will shape productivity and risk exposure for years. PW Consulting’s One Stop Collaboration Platform For Enterprise Market report equips boards, CIOs, and procurement teams with the frameworks, templates, and risk-mitigation playbooks necessary to convert market momentum into sustainable advantage. To access the full data annex, vendor scorecards, and operational toolkits, request the complete report through PW Consulting’s report page.
For detailed analysis of this topic, please visit the official page: One Stop Collaboration Platform For Enterprise Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com