

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Bronchiolitis Obliterans Syndrome Market to Grow at 6.5% CAGR, Reaching USD 598.3 Million by 2032

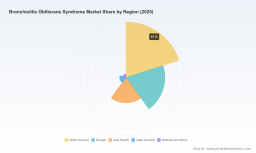
Bronchiolitis Obliterans Syndrome Market — 2026 Strategic Brief
Executive snapshot
PW Consulting’s latest Bronchiolitis Obliterans Syndrome (BOS) Market report (base year 2025) provides a forward-looking intelligence package crafted to inform commercial, clinical development and investment decisions throughout 2026. At a macro level, the BOS market is estimated at approximately USD 385.0 Million in 2025 and, under our base-case assumptions, is forecast to grow to roughly USD 598.3 Million by 2032 — representing a compound annual growth rate (CAGR) of 6.5% over the 2026–2032 forecast horizon. Historical trend analysis across 2020–2025 is integrated into our models to highlight structural drivers and emerging inflection points.
Bronchiolitis Obliterans Syndrome Market
Why 2026 is a strategic inflection point
-
Pipeline maturation: Multiple late-stage and mid-stage candidates are converging in a narrow time window. Notably, a pivotal inhaled formulation has completed Phase 3 enrollment in recent years and other inhaled and systemic candidates are progressing through Phase 2 programs. This compressed timeline creates a definable window for commercialization and partnership activity.
Bronchiolitis Obliterans Syndrome Market -
Corporate repositioning and capital flows: The market has seen targeted M&A and financing activity tied to inhaled therapeutics and platform capabilities. A recent acquisition and financing round (May 2026) is explicit proof of investor appetite for BOS-focused assets and technology platforms that can accelerate inhaled drug delivery.
Bronchiolitis Obliterans Syndrome Market -
Regulatory and reimbursement dynamics: BOS currently lacks therapies explicitly approved for the indication in major regulatory markets, augmenting the value of first-in-class or first-in-indication approvals. Simultaneously, payers are signaling stringent evidence expectations given the high lifetime cost burden associated with transplant complications, creating a runway where clinical differentiation and economic evidence will determine access and uptake.
What the report delivers — practical, executable intelligence
Beyond headline forecasts, the report is engineered as a tactical toolkit for 2026 decision-making. Highlights include:
-
Robust forecasting framework: A transparent, probabilistic model covering historical performance (2020–2025) and forecasts to 2032, with scenario toggles for adoption speed, pricing, and reimbursement outcomes.
-
Patient and treatment pathway analytics: Granular patient-flow models, transplant center catchments, and attrition points that explain demand formation and clinical trial recruitment risk.
-
Commercialization playbooks: Segmented go-to-market pathways by channel (transplant centers, specialist networks, and integrated health systems), evidence generation priorities to accelerate formulary access, and contracting strategies tailored for high-cost, small-population therapies.
-
Regulatory and HTA roadmaps: Country-specific engagement checklists, comparator selection guidance, and a matrix of likely evidentiary requirements for orphan-designated and fast-tracked therapies.
-
Competitive intelligence: Deep profiles of incumbent and emerging players, program timelines, trial designs, and strategic bets — synthesised to reveal win-states and likely consolidation scenarios.
-
Investor and BD&L decision support: Valuation-ready financial scenarios, milestone/royalty modeling templates and an M&A timing advisory informed by upcoming readouts and regulatory windows.
-
Interactive deliverables: Downloadable Excel models, sensitivity dashboards and a slide-ready executive summary to expedite internal briefings.
Competitive dynamics — who to watch and why
The competitive picture is nuanced: a mix of specialty players advancing inhaled formulations, larger biopharma firms with respiratory portfolios exploring anti-inflammatory and antifibrotic strategies, and clinical-stage companies pursuing systemic immune modulation. Key players profiled in the report include:
-
Zambon — advancing an inhaled liposomal formulation through pivotal Phase 3 programs, positioning to be the potential first approved inhaled therapy for BOS post-lung transplant. Their program benefits from orphan/fast-track regulatory designations that shorten regulatory timelines but will still require compelling clinical and health economic data to secure payer coverage.
-
Quince Therapeutics — following a May 2026 acquisition and financing event, the company is accelerating an inhaled sirolimus program currently in Phase 2, with pivotal readout potential in the near-term development horizon. Their capital raise and platform integration strategy underscore the prioritization of inhaled delivery for localized efficacy with potentially improved safety.
-
Incyte Corporation — exploring JAK inhibition with clinical data showing meaningful lung function improvements in post-hematopoietic stem cell transplant BOS; this systemic immune-modulation approach could be an attractive option in certain patient subgroups and may find utility in combination strategies.
-
Genentech (Roche) and GSK — both maintain respiratory and anti-fibrotic research programs that could be rapidly repurposed or combined into BOS strategies. Their scale and payer relationships give them optionality should clinical data support broader indications.
Market concentration metrics point to a market that is semi-consolidated: the top three firms account for a meaningful share of revenue, while the top five further increase concentration. This structure creates both incumbent advantages and windows for differentiated entrants, especially those delivering novel delivery platforms or compelling economic value.
Strategic implications for stakeholders
-
For developers: Prioritise robust, transplant-center-led endpoints and health-economic sub-studies in pivotal programs. Inhaled therapies that demonstrate localized efficacy with favorable safety will command premium pricing but will still need real-world cost-offset evidence to satisfy payers.
-
For payers and providers: Prepare coverage frameworks that reward clinically and economically demonstrable reductions in decline and downstream resource utilization; anticipate complex contracting with outcomes-based elements tied to lung function and survival metrics.
-
For investors and BD&L teams: Time deal activity around the pipeline calendar. Near-term value creation is heavily correlated to readouts and regulatory milestones; conversely, spending too early on scale manufacturing without clear reimbursement pathways raises execution risk.
-
For policy and HTA bodies: Implement early scientific advice and conditional coverage pathways to manage uncertainty while ensuring rapid patient access for therapies that address an unmet need in post-transplant care.
Scenario planning — mapped to the 6.5% CAGR baseline
Our base-case scenario aligns with the modeled CAGR of 6.5% and assumes a steady entrance of late-stage assets combined with conservative uptake curves driven by payer negotiation timelines. Upside scenarios — where market growth accelerates meaningfully — require at least one first-in-indication approval with favorable reimbursement and rapid adoption in high-volume transplant centers. Downside scenarios hinge on regulatory setbacks, failure to secure meaningful coverage terms, or clinical safety signals that constrain label scope.
How to use this report in 2026 — recommended actions
-
Conduct rapid-gap assessments against the report’s evidentiary checklist to prioritise 2026 trials, registries and health-economic studies.
-
Deploy the scenario models to stress-test pricing and market-access negotiations before engaging payers or entering partnership discussions.
-
Use the competitor and deal trackers to time BD&L outreach and to identify high-value partner profiles (manufacturing, inhalation-device expertise, or reimbursement specialists).
-
Plan manufacturing scale-up conditional on regulatory milestones — reserve capital for post-approval real-world evidence generation to accelerate uptake.
Methodology and credibility
PW Consulting’s BOS Market report is grounded in a multi-source evidence base: clinical-trial registries and publications, company disclosures, transplant registry data, payer and transplant center interviews, and health-economics literature. The model period spans a documented historical window (2020–2025) with a forecast to 2032; outputs include probabilistic sensitivity analysis, market-share simulations and a risk-adjusted valuation framework. Our competitive concentration analysis, supported by market-share modeling, informs the strategic implications described above.
Next steps and where to get the full intelligence
This bulletin is a strategic “trailer” designed to surface the decision-critical themes and near-term timing that should guide resource allocation in 2026. The full PW Consulting BOS Market report contains the complete segmentation tables, downloadable forecasting models, regional and indication breakdowns, trial-by-trial comparator matrices, and an expandable competitive-calendar that senior executives, investors and BD&L teams will find indispensable.
To request the full report, interactive model files and a tailored briefing, please visit PW Consulting’s report page or contact our industry team for a private walkthrough. For organizations preparing capital plans or partnering strategies in 2026, our recommendation is immediate: secure the full intelligence set to align clinical, commercial and market-access activities with the short window before pivotal readouts and reimbursement negotiations begin shaping the BOS landscape.
For detailed analysis of this topic, please visit the official page: Bronchiolitis Obliterans Syndrome Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com