

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Ear Wax Removal Drops Market to Expand at a 4.52% CAGR During 2026–2032

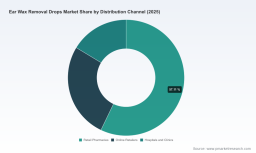
Ear Wax Removal Drops Market — Strategic Outlook for 2026: A PW Consulting Brief
Executive summary
PW Consulting’s latest market research synthesizes macro trajectories, competitive dynamics, regulatory constraints and practical go-to-market playbooks for the global ear wax removal drops category. Anchored on a rigorous historical window (2020–2025) with base year 2025 and a forward-looking forecast spanning 2026–2032, the study quantifies a steady market expansion driven by at‑home care adoption, product innovation and channel evolution. The category’s compound annual growth rate (CAGR) is modeled at 4.52% over the forecast horizon, reflecting resilient demand and episodic acceleration tied to product launches and channel shifts.
Ear Wax Removal Drops Market
Where the market stands and where it’s headed
-
Historical momentum: The market has progressed meaningfully from the early 2020s into 2025, reflecting higher consumer acceptance of OTC ear care solutions and greater retailer assortment.
Ear Wax Removal Drops Market -
Near-term posture: Our base-year analysis (2025) captures supply‑side normalization after pandemic-era disruptions and the initial commercial effects of new formulations and adjunct products introduced by category specialists.
Ear Wax Removal Drops Market -
Forecast view: Using scenario-driven modeling, PW Consulting projects steady growth through 2032 underpinned by incremental product differentiation, digital direct-to-consumer (DTC) expansion and continued clinician endorsement for selected brands and formulations.
Key macro and category drivers
-
Clinical and formulation science: Carbamide peroxide-based reagents remain the foundational active ingredient in most leading drops, with standardized concentrations and well-understood mechanisms (oxygen release to soften cerumen). This legacy science lowers scientific risk for newcomers but raises the bar on incremental innovation (e.g., combination actives, comfort-focused formulations).
-
Regulatory framework: Carbamide peroxide ear drops continue to be governed under OTC monograph guidance in major markets. Regulatory predictability reduces market execution risk but requires disciplined label and claims management for any novel claims or adjunct products (e.g., pain or itch indications).
-
Consumer behavior: OTC drops are entrenched as a first-line, at-home management step prior to irrigation or clinical removal. Rising consumer preference for non-invasive, convenient options and a willingness to purchase online supports premiumization and subscription plays.
-
Channel dynamics: Omnichannel coverage—retail pharmacies, online marketplaces, and clinical channels—drives assortment strategies. Retailers and e‑commerce platforms are competing on assortment breadth, price, and private-label alternatives, altering promotional dynamics and shelf placement economics.
Competitive landscape — strategic map (high level)
The market shows a moderate level of concentration, with a top-tier cluster of established OTC consumer brands, followed by clinically‑oriented entrants and generics. PW Consulting’s competitive framework profiles incumbents across brand equity, channel strength, clinical positioning and product breadth.
-
Prestige Consumer Healthcare (Debrox, Murine): Legacy consumer brands with strong OTC recognition, retail shelf presence and longstanding clinician awareness. Strengths include brand trust, broad distributor relationships and typical margin profiles of established consumer healthcare SKUs.
-
Eosera Inc.: A clinically‑oriented innovator that has recently broadened its portfolio. Recent product launches in 2026 (advanced ear care formulas plus ear swabs and supplements) signal a play to expand category adjacency and capture incremental DTC share through differentiated claims and clinician outreach.
-
NeilMed Pharmaceuticals: A portfolio player with a focus on ear and nasal care; leverages cross-category distribution and bundled kits to increase share of wallet among at‑home care patients.
-
Doctor Easy Medical Products Corporation: Unique positioning—product integration with irrigation systems—creates a hardware-software style moat where replenishment demand for drops complements device sales and provides a point of contact with clinical users.
-
Major Pharmaceuticals and generics suppliers: Competitive pressure on price, enabling private-label penetration into mass channels; attractive for retailers seeking margin flexibility but compressive for branded incumbents.
Collectively, the market concentration profile points to opportunity for targeted M&A and brand consolidation while leaving room for differentiated entrants that can prove clinical benefit or channel advantage.
What PW Consulting’s full report delivers (practical, actionable content)
The published study is intentionally structured for corporate strategy teams, business unit leads and M&A investors seeking executable recommendations for 2026 decisions. Highlights include:
-
Revenue and volume forecasting templates: Multi-scenario projections (base, upside, downside) with sensitivity levers for price, penetration, and channel mix calibrated to the 2026–2032 horizon.
-
Commercial playbooks: Channel-specific GTM blueprints for retail pharmacy, online marketplaces and clinic/hospital partnerships—each with merchandising tactics, promotional cadence, and assortment logic.
-
Innovation roadmap and product development checklist: Prioritized feature sets and clinical study designs that materially improve conversion and justify premium pricing; regulatory pathway maps for label claims and combination product strategies.
-
M&A and partnership playbook: Screening framework for targets, valuation stress-tests, and 100-day integration templates focused on SKU rationalization, supply-chain consolidation and route-to-market synergies.
-
Supply chain and raw material risk matrix: Critical inputs, single‑point‑of‑failure analysis, and mitigation strategies—centered on active ingredient sourcing and packaging constraints.
-
Pricing and promotional elasticity models: Robust econometric models quantifying trade-off between price, promotional depth and long-term brand equity.
-
KPIs and implementation dashboards: Turnkey scorecards for commercial ops, R&D prioritization, and post‑merger performance monitoring.
Strategic recommendations for 2026 decision-makers
-
Prioritize differentiated clinical evidence: With formulation science well understood, the most defensible route to premium positioning is controlled, well-designed studies demonstrating better tolerability, faster wax softening, or broader symptomatic relief. Allocate an early portion of 2026 R&D spend to randomized, pragmatic trials tied to label claims.
-
Invest in DTC and subscription fundamentals: The forecasted CAGR and channel evolution favor brands that can convert first-time buyers into repeat purchasers via subscriptions tied to dosing cycles, bundled irrigation supplies, or complementary ear-care products.
-
Harden supply-chain resilience: Secure multi-sourced contracts for key actives and packaging, and stress-test logistics under multiple scenarios. The report includes a playbook for near-term hedging and a mid-term supplier diversification roadmap.
-
Pursue value-accretive consolidation: Given the current concentration profile and the presence of generics and private label competition, selective M&A—focusing on clinical-heavy incumbents or channel-specialized players—can yield scale economics and shelf-listing leverage.
-
Design retail and e-commerce differentiation: For brick-and-mortar, prioritize merchandising and pharmacist-facing education; online, optimize content for clinical reassurance and SEO, and experiment with bundled SKUs and trial-size formats.
-
Manage regulatory risk proactively: Any movement toward expanded claims, combination products, or novel delivery formats must be accompanied by an FDA engagement plan and label-compliance roadmap to avoid costly rework.
Use cases and beneficiaries
This report is built for three primary audiences:
-
Category leaders (brand owners) needing to defend margin and expand premium share.
-
Investors and private equity teams screening acquisition targets or planning bolt-on strategies in consumer health.
-
Retail and distributor strategy teams optimizing assortment, private-label penetration and omnichannel promotions.
Methodology and transparency
PW Consulting’s analysis combines syndicated POS data, primary interviews with industry executives and clinicians, regulatory landscape mapping, and bottom‑up financial modeling. The study uses the 2025 base year with historical analysis covering 2020–2025 and a forecast period of 2026–2032. Projections are expressed in USD (Million) and incorporate our central CAGR estimate of 4.52% across the forecast window. Detailed assumptions and model workbooks are included in the full deliverable.
Why this matters for 2026 planning
2026 is a pivotal planning year: incumbent brands must decide whether to defend through incremental R&D and marketing spend, or to pursue consolidation plays that deliver shelf and online prominence. New entrants face a choice between competing on price versus clinical differentiation. For private-label players and distributors, the focus will be on assortment efficiency and margin recovery. PW Consulting’s report converts these strategic choices into prioritized action plans with measurable KPIs and financial impact estimates.
Next steps — how to access the full intelligence
This briefing is a selective preview designed to communicate the strategic value and practical orientation of PW Consulting’s full Ear Wax Removal Drops Market report. The complete study contains proprietary segment-level forecasts, detailed channel revenue models, retailer assortment maps, and competitive share tables—data critical for transaction diligence and GTM execution. To obtain the full report and model workbooks, contact PW Consulting or visit our publications page for licensing and delivery options.
Closing
For executive teams deciding resource allocation in 2026, the difference between reactive and proactive strategies will hinge on actionable evidence—clinical, commercial and financial. PW Consulting’s deliverables are structured to move organizations from insight to implementation within 90–180 days. If your strategic plan for ear care is being drafted this year, the intelligence and playbooks in our full report will materially de‑risk key decisions.
For detailed analysis of this topic, please visit the official page: Ear Wax Removal Drops Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com