

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ballistic Protection Market to Expand at a 6.35% CAGR During 2026–2032, New Report Finds

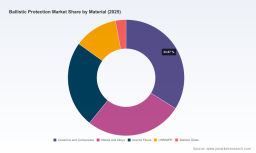
Ballistic Protection Market — 2026 Strategic Brief
PW Consulting’s latest Ballistic Protection Market study is designed as the operational intelligence playbook executives need as they set priorities for 2026. Anchored on a 2025 base year, the report traces demand dynamics across modern combat, law-enforcement modernization, and high-threat civilian protection programs — and translates those dynamics into concrete, near-term actions for procurement, engineering, manufacturing and M&A decision-makers. At the market level, global industry value expanded materially through the 2020–2025 period and is forecast to continue on a steady trajectory, compounding at a 6.35% CAGR through our 2026–2032 forecast window.
Ballistic Protection Market
Why this report matters for 2026 decision-makers
-
Procurement windows are compressing. Updated standards and allied interoperability requirements have created concentrated upgrade cycles that will shape budgets and sourcing choices for the next 18–36 months.
Ballistic Protection Market -
Material substitution is shifting the product map. Breakthroughs in UHMWPE and new hard unidirectional laminates materially alter design trade-offs between weight, blunt trauma, and cost-to-protect.
Ballistic Protection Market -
Supply-chain stress and feedstock volatility are real. Elevated raw-material input prices and localized capacity expansions change negotiating leverage between system integrators and fiber producers.
-
Competitive positioning is intensifying. The market’s mid-to-upper tier exhibits moderate concentration, leaving room for targeted consolidation, vertical integration and specialist partnerships.
What PW Consulting’s report delivers (practical, actionable outputs)
-
Executive decision memos: tailored one-page recommendations for CEOs, procurement leads, and R&D heads keyed to specific 2026 portfolio choices.
-
Go-to-market playbooks: segment-agnostic commercialization roadmaps that include pricing guardrails, certification timelines and aftermarket capture strategies.
-
Supplier scorecards and sourcing decision matrices: criteria-based assessments that prioritize resilience, certification readiness, and unit-cost trajectory.
-
Engineering trade-off calculators: configurable tools to evaluate weight, protection level, and cost outcomes for candidate material stacks.
-
Regulatory and certification checklists: step-by-step paths to meet updated NIJ and NATO testing regimes, including timelines and likely cost buckets.
-
Scenario-driven financial models: base/optimistic/stress cases covering revenue, gross margins and CapEx implications over the 2026–2032 period.
-
M&A playbooks: target screens, integration templates and projected synergies for strategic and financial buyers.
Market trajectory and growth drivers
Over the 2020–2025 historical span the global ballistic protection market registered meaningful expansion as modernization programs resumed and civilian procurement of protective equipment accelerated. With a 2025 base year established in this report, our forward view projects healthy compound growth through 2032, driven by four interconnected forces:
-
Standards-led refresh cycles. The transition to updated protective-armor standards has prompted defense and public-safety buyers to accelerate replacement timelines and to require fresh certification, increasing short-to-medium term replacement demand.
-
Material innovation. Advanced UHMWPE fibers and next-generation unidirectional hard materials are delivering dramatic weight reductions versus legacy stacks, enabling new form factors and greater user endurance — a competitive inflection that favors firms that control or co-develop supply of these materials.
-
Platform survivability programs. Modern vehicle and aircraft survivability upgrades increasingly integrate modular armor packages, creating demand not only for primary armor but for integration engineering and aftermarket sustainment services.
-
Regional defense modernization. Geopolitical pressure and alliance interoperability requirements continue to drive procurement planning and influence vendor selection criteria toward certified, scalable suppliers.
Competitive landscape — structure, moves and implications
The market presents a hybrid structure: established system integrators and platform OEMs sit alongside specialized material and textile suppliers. Concentration metrics indicate a market where the top three players account for a meaningful portion of industry revenue, and the top five widen that share considerably — a structure that creates space for smart mid-market consolidation while retaining room for specialist entrants.
Strategic implications by player archetype:
-
Integrated defense primes (e.g., established systems integrators): Their strength is platform-level integration, certification capability, and existing procurement relationships. Expect continued emphasis on modular armor modules and aftermarket sustainment contracts.
-
Material innovators and fiber producers (aramid and UHMWPE specialists): Control of advanced fibers and unidirectional laminates translates directly into product differentiation. Recent launches demonstrating substantial weight reduction underscore the competitive premium for materials IP.
-
Specialist personal-protection OEMs: These firms compete on ergonomics, certification speed and service channels to law enforcement and first responders; rapid certification-ready offerings will win early 2026 contracts.
-
Regional manufacturers: Local-content and manufacturing proximity offer procurement advantages in constrained or politically-sensitive programs, creating attractive targets for strategic partnerships or bolt-on acquisitions.
Notable industry activity through the last 18 months illustrates these dynamics: ultra-light hard unidirectional materials introduced by a leading UHMWPE supplier that promise substantial weight savings; new combat-helmet product launches with modular ballistic enhancements; certification-ready plate showcases at major trade shows; and capacity investments by U.S. manufacturers expanding tooling and assembly footprint. Taken together, these moves signal a market where materials innovation, speed-to-certification and manufacturing scale will determine winners in 2026.
Supply-chain and raw-material dynamics — risk and response
Two supply-side realities demand attention. First, feedstock and polymer inputs for para-aramid production experienced price pressure late in 2025, creating higher-than-normal unit cost risk for aramid-based solution stacks. Second, UHMWPE fibers offer structural advantages — including exceptionally high strength-to-weight ratios and substantial weight advantages versus aramid systems — that are accelerating substitution in lightweight applications.
Recommended mitigation actions for 2026:
-
Lock in multi-year material offtakes with indexed pricing clauses to stabilize unit-cost exposure.
-
Qualify dual-material architectures where possible to preserve design flexibility if a feedstock shock occurs.
-
Invest in in-house or partner-based certification labs to shorten time-to-market for upgraded products compliant with new standards.
-
Monitor strategic suppliers for capacity expansion announcements and secure capacity commitments where critical to program timelines.
Go-to-market and procurement playbook for 2026
-
Prioritize certification readiness: Make updated-standards certification a gating item for 2026 bids and RFP responses.
-
Differentiate on total cost-to-protect: Shift pricing conversations from unit price to lifecycle protection cost and integration savings.
-
Bundle services: Offer sustainment, retrofit kits and upgrade pathways that capture aftermarket margin and deepen client relationships.
-
Pursue selective vertical integration: Acquire or partner with material specialists to secure critical inputs and speed innovation cycles.
-
Use modular architectures: Design armor as modular, upgradable subsystems to extend platform life and simplify certification paths.
-
Establish regional manufacturing nodes: For priority procurement markets, consider in-region assembly to meet local-content requirements and shorten lead times.
M&A and investment posture — where to place bets
Investor appetite in 2026 should prioritize three target profiles: material-IP owners with demonstrated weight-performance advantages; mid-sized integrators with certified product portfolios and proven procurement relationships; and regional manufacturers offering fast market access and attractive valuation arbitrage. The market’s current concentration suggests consolidation can create scale benefits, but successful deals will hinge on preserving engineering autonomy and securing long-term material supply.
What we are intentionally holding back — and why
True to the “trailer” principle, this brief demonstrates the depth of PW Consulting’s strategic thinking while deliberately omitting detailed segment-level tables, region-by-region revenue splits, and application-specific pricing grids. Those datasets form the core of the report’s proprietary modeling and are provided exclusively through the full report package and its accompanying data workbook. Clients who require transaction-level diligence, tailored supplier scorecards, or custom forecasting scenarios will find the full dossier contains downloadable models, supplier contact maps and RFP-ready procurement templates.
Final recommendation
For 2026, leaders should treat the ballistic protection market as a technology-and-certification-driven growth opportunity underpinned by defensive procurement cycles and material substitution. Short-term winners will be those who combine rapid certification execution, secured material supply, and modular product strategies that reduce program risk for buyers. PW Consulting’s Ballistic Protection Market report delivers exactly the executable tools and intelligence that procurement, corporate development and engineering teams will need to convert this market momentum into sustainable advantage.
To access the full report, datasets and practical templates referenced here, please visit PW Consulting’s Ballistic Protection Market page for the complete package and client onboarding options.
For detailed analysis of this topic, please visit the official page: Ballistic Protection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com