

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Floor-Standing Aircraft Weighing Scales Market to Reach USD 836.75 Million by 2032, Posting 7.0% CAGR (2026–2032)

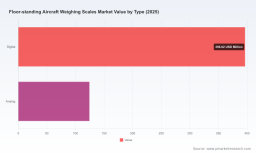
Floor Standing Aircraft Weighing Scales Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
The global floor standing aircraft weighing scales market has undergone a notable transformation in recent years and remains on a robust growth trajectory. After expanding from approximately USD 312.45 Million in 2020 to an estimated USD 521.09 Million in the 2025 base year, the market is forecast to continue accelerating across the 2026–2032 horizon, reaching roughly USD 836.75 Million by 2032 at a compound annual growth rate (CAGR) of 7.0%. This rhythm of growth reflects a convergence of regulatory tightening, fleet renewal and ramp-ups, product innovation (notably wireless and low‑profile digital systems), and the increasing emphasis on digitized weight-and-balance workflows.
Floor Standing Aircraft Weighing Scales Market
Why 2026 matters — a strategic inflection point
-
Regulatory alignment is tightening and operational tolerance for weight-and-balance errors is shrinking. With standards and advisory guidance requiring high-accuracy, traceable calibrations, aircraft operators and ground-support equipment (GSE) suppliers will need to upgrade capabilities or risk compliance gaps.
Floor Standing Aircraft Weighing Scales Market -
Technology shifts are moving value from hardware alone to integrated data services — real‑time wireless telemetry, NIST‑traceable calibration management, and cloud-enabled recordkeeping are becoming differentiators that command price premia and recurring revenue.
Floor Standing Aircraft Weighing Scales Market -
Market concentration (CR3 ~48.5%; CR5 ~62.3%) indicates a moderately consolidated supplier landscape where scale, certification footprint, and service networks provide meaningful competitive advantage. For 2026 planning, this concentration implies both barrier effects for new entrants and potential for M&A to accelerate capability acquisition for incumbents and fast followers.
-
Supply chain dynamics — including aircraft-grade aluminum sourcing and precision load-cell manufacturing — are creating execution risk for production planning and aftermarket fulfilment. Buyers and suppliers who lock in resilient sourcing or verticalize key inputs will preserve uptime and margins.
What PW Consulting’s report delivers — practical, actionable intelligence
Our latest Floor Standing Aircraft Weighing Scales Market study is structured to support high‑stakes 2026 decision-making across corporate strategy, procurement, product management, and M&A. The report combines proprietary shipment and revenue modeling, supplier capability maps, regulatory impact assessments, and a prioritized set of strategic plays. Highlights include:
-
A validated market-sizing time series (2020–2025 historical; 2026–2032 forecast) with sensitivity scenarios that translate macro fleet and regulatory drivers into near-term revenue impacts.
-
An operational playbook for procurement leaders: procurement levers, contract design templates that embed calibration and traceability SLAs, and a vendor evaluation scorecard tuned for 2026 requirements.
-
Product and R&D guidance: technology roadmaps for transitioning legacy analog offerings to digital, low‑profile platforms and wireless ecosystem integration, including recommended feature sets and test matrices for ±0.1% accuracy compliance.
-
Service and aftermarket monetization models that quantify the ROI of moving from one‑time hardware sales to subscription calibration, fleet health monitoring and predictive maintenance services.
-
A risk register and mitigation playbook covering raw-material volatility, certification timelines, and single-source component exposures.
-
Competitive benchmarking and scenario planning: relative positioning of incumbent global suppliers, their certification footprints, product portfolios, and likely strategic moves through 2028.
Competitive dynamics — who matters and why
The market is shaped by a set of specialized manufacturers and GSE integrators that combine domain engineering with regulatory know‑how. Leading players have differentiated along three vectors: certified load‑cells and platform design for high-capacity aircraft, wireless and low-profile productization, and global calibration/service networks.
-
Intercomp Company (Medina, Minnesota) has strengthened its position through technology-driven launches and customer wins. Recent product introductions that embed Bluetooth wireless telemetry exemplify the industry move to real-time data capture and traceable workflows; large operator adoptions demonstrate how features translate to procurement decisions.
-
General Electrodynamics Corporation (Arlington, Texas) competes strongly on portability, patented platform designs and global field support — factors that make it a default supplier for mobile and OEM applications.
-
Teknoscale Oy (Finland) and specialist European OEMs have focused on high-capacity, aircraft-specific platforms for commercial and military airplanes, playing to strengths in engineering for fighter and wide‑body applications.
-
Langa Industrial and select European vendors have leveraged close working relationships with OEMs and MROs to secure homologations — a competitive advantage where type-approval and GSE compatibility matter.
-
Smaller regional suppliers add breadth to the market, particularly in aftermarket service niches and integrated weighing solutions embedded in final assembly lines.
Recent industry moves illustrate these dynamics: product launches that emphasize wireless, low-profile weighing technology; major airline adoptions of next‑generation platform scales; and supplier certifications aligned to OEM requirements. Each of these developments compresses buying cycles toward vendors who can demonstrate certified accuracy, traceability, and data connectivity.
Regulatory and technical drivers — what keeps procurement awake
-
Accuracy and traceability: Industry standards now expect accuracy to the order of ±0.1% of applied load with NIST‑traceable calibration. This is not a comfort target — it is an operational and audit requirement that shapes both product design and ongoing calibration services.
-
Advisories and certification: Regulatory guidance and advisory circulars require operators to demonstrate consistent weight-and-balance control; suppliers that can provide auditable, digital calibration records and certified instruments will capture a premium.
-
Material and manufacturing choices: Aircraft‑grade aluminum remains the dominant structural material for low‑profile platforms, balancing capacity and payload. Suppliers with secured, certified material suppliers and quality controls will reduce lead‑time variability.
Strategic recommendations for 2026 planning
For executives shaping 2026 plays, prioritize actions that convert market growth and regulatory pressure into defensible revenue and operational resilience:
-
Invest in digital migration now. Transition product portfolios to support wireless telemetry, cloud calibration records, and API-based integration with weight-and-balance systems. The business case combines faster sales cycles and recurring calibration/subscription revenue.
-
Lock in calibration and traceability as a service. Offer bundled calibration plans with SLAs tied to regulatory accuracy thresholds — this increases customer switching costs and smooths revenue.
-
Target certification and homologation early. Where your customers operate certified fleets, certification timelines determine deal timing. Allocate resources to secure approvals that competitors lack.
-
Mitigate material and critical-component risk. Create dual-sourcing strategies for aircraft-grade aluminum and key load-cell suppliers, and evaluate low-variability contract forms that protect gross margins in a volatile raw-material environment.
-
Pursue focused M&A and partnerships. Given the market’s moderate concentration, bolt-on acquisitions of service networks, calibration laboratories, or wireless telemetry specialists are high-leverage moves to accelerate capability and geographic reach.
-
Design procurement contracts for total cost of ownership. For airlines and MROs, shift from a lowest‑price procurement mindset to TCO frameworks that value uptime, calibration traceability, and integration efficiencies.
Risks, signals to watch, and timing
-
Watch certification backlogs. Delays in homologation create procurement bottlenecks — flagged by prolonged testing cycles or regulatory queueing.
-
Monitor raw-material price spreads. Significant jumps in aluminum prices or constrained availability will pressure lead times and margins; hedging or upstream agreements are prudent.
-
Track technology adoption curves. Early adopters of wireless and cloud-based weighing systems will define market expectations; laggards risk being relegated to price competition.
-
Observe consolidation activity. Acquisitions among the top players can rapidly change CR dynamics — a key input for competitive and pricing strategies.
How PW Consulting can support your 2026 agenda
Our report is designed as a decision-ready tool: scenario financials you can drop into board-level planning, procurement scorecards you can operationalize immediately, and a prioritized action list for product, service, and M&A plays. We have intentionally presented high‑level strategic signals here to demonstrate analytical depth; the full report contains the granular, executable sections — including supplier scorecards, contractual templates, regional demand scenarios, and product feature matrices — that organizations will need to execute with precision.
Next steps
For executives and procurement leads preparing 2026 budgets or strategic roadmaps, the next logical step is to review the full PW Consulting Floor Standing Aircraft Weighing Scales Market report and accompanying toolkit. The complete dataset and model include the detailed segment breakdowns, price tiers, and vendor-level comparatives that are deliberately withheld here to preserve the report’s role as a value‑added decision asset. Contact PW Consulting to access the full intelligence package and schedule a bespoke briefing focused on your specific operational and strategic levers.
For detailed analysis of this topic, please visit the official page: Floor Standing Aircraft Weighing Scales Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com