

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Production of Lentiviral Vectors Market to Grow at 18.52% CAGR — From USD 1,340.35 Million in 2025 to USD 4,403.11 Million by 2032

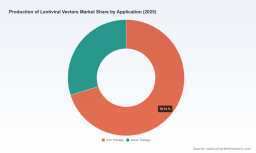
PW Consulting: Strategic Brief — Production of Lentiviral Vectors Market (2026 Decision Playbook)
PW Consulting today publishes an executive industry insight accompanying our full Production of Lentiviral Vectors Market report. Built on a comprehensive 2020–2025 historical review and forward-looking forecasts for 2026–2032, this brief distills the strategic intelligence that senior executives, investors and manufacturing leaders will need to craft competitive decisions in 2026. Our modelling shows the total market scaling from a mid-single‑hundred million base in 2020 to roughly USD 1.34 billion in 2025, with a projected trajectory that accelerates to approximately USD 4.40 billion by 2032 — a compound annual growth path in the high teens (18.52% over the forecast window).
Production Of Lentiviral Vectors Market
Why this market matters in 2026
-
Convergence of demand and capacity: Rapid clinical progress in ex vivo cell therapies and expanding gene therapy pipelines have created acute, visible demand for GMP lentiviral vectors. Sponsors are confronting capacity bottlenecks that affect program timelines, valuation milestones and commercialization readiness.
Production Of Lentiviral Vectors Market -
Manufacturing economics now influence therapeutic strategy: Vector cost-of-goods and upstream raw material inputs are material drivers of program economics. Decisions about transient transfection versus stable production platforms and choices in upstream/downstream process design are shifting from technical to strategic priorities.
Production Of Lentiviral Vectors Market -
Regulatory evolution is enabling but exacting: Recent regulatory guidance in 2025–2026 increases flexibility to support innovation in early‑phase development while reinforcing expectations that analytical methods be fit‑for‑purpose and demonstrably qualified as programs progress to later phases.
-
Market structure creates opportunities for differentiated CDMOs and platform providers: The supply base is consolidating, but room remains for specialist players that can offer scale, regulatory experience and integrated services across plasmid supply, vector production and fill/finish.
Core insights from the PW Consulting report
-
Robust top‑line growth with differentiated risk profiles: Our base-case forecast embeds technology substitution, regulatory scenarios and capital‑intensity assumptions. The headline growth trajectory (18.52% CAGR) masks meaningful variance by workflow, application and scale; navigating that variance is the crux of near-term strategy.
-
Capacity mapping and lead times are the new scarce resource: We model current installed capacity and near‑term commissioning plans, identifying where project timelines will compress and where premium pricing and contract structuring power will accrue to providers.
-
Upstream choices drive cost and supply resilience: Transient HEK293 systems remain the operational standard for many programs, but stable producer lines and alternative upstream architectures materially reduce reliance on high‑cost plasmid inputs. Each path implies different investment horizons and operational risks.
-
Analytical strategy is a program enabler: Programs that invest early in fit‑for‑purpose assays and a staged qualification plan reduce regulatory friction and downstream rework. Our report includes recommended assay portfolios and qualification checklists tied to typical program milestones.
-
Commercial readiness extends beyond manufacturing: Fill‑finish, cold chain, release testing and supply‑chain risk management are often underestimated. We provide scenario modelling that links manufacturing bottlenecks to peak sales risk and time‑to‑market sensitivity.
What the full report contains (operational, actionable modules)
-
Market sizing and high‑resolution forecasts (2026–2032) with scenario analysis to assess downside, base and upside demand paths.
-
Capacity and facility registry: verified facility footprints, technology platforms, commissioning timetables and utilization modelling.
-
Vendor benchmarking and CRV (competitive readiness value) scorecards to evaluate CDMO partners on technical capability, regulatory history, supply resilience and commercial experience.
-
Cost‑of‑goods and material cost models, including sensitivity analyses on plasmid supply, consumables and single‑use technologies.
-
Regulatory readiness and assay qualification playbooks tied to IND, pivotal and commercial phases.
-
Investment decision templates, payback and IRR models for greenfield facilities, platform upgrades and M&A scenarios.
-
Contracting and procurement archetypes: term‑sheet constructs, capacity reservation models and penalty/earn‑out mechanisms tailored to long‑lead vector supply.
-
Custom dashboards and interactive scenario tools to stress‑test commercialization timelines against supplier constraints and regulatory options.
Competitive landscape — pragmatic reading for 2026
-
Strategic CDMOs with integrated capabilities dominate the conversation: Established global CDMOs are expanding footprint and capabilities to capture commercial programs and anchor long‑term supply agreements. These providers pair process development with large‑scale GMP manufacturing and fill/finish facilities — a combination that remains decisive for late‑stage sponsors.
-
Specialists and regional leaders provide niche differentiation: A set of focused players offers dedicated lentiviral vector workflows and fast‑to‑deploy cleanroom capacity, often attractive to early‑phase or geographically local sponsors who prioritize speed and technical specialization.
-
Market concentration delivers both stability and risk: The supply base shows measurable concentration among top providers, creating potential counterparty concentration risk for sponsors that centralize supply with one provider.
-
Recent industry moves you should factor into 2026 planning: Several leading providers have announced capacity expansion and strategic supply agreements that affect forward availability and commercial pricing dynamics. Notable examples include multi‑year commercial supply agreements by established CDMOs, acquisitions and commissioning of commercial‑scale viral vector sites, opening of large cell and gene therapy centers directed at plasmid and viral vector production, and strategic collaborations between CDMOs and academic translational institutes to accelerate GMP‑grade vector supply for CAR‑T programs. These developments materially alter the competitive map and should inform contracting and contingency planning.
How to use this intelligence in 2026 — recommended actions
-
Lock in capacity early but structure for flexibility: Use staged purchase agreements with defined ramp‑up milestones and options to swap technologies or sites as programs advance.
-
Invest in analytical readiness now: Budget for assay development and staged qualification; early investments shorten IND‑to‑pivotal timelines and reduce regulatory risk.
-
Diversify raw material sources and consider upstream platform choices: Where plasmid supply or transient transfection is a bottleneck, evaluate co‑investment or strategic partnerships that secure long‑term feedstock.
-
Quantify supply concentration risk: Map counterparty exposure against program value and time sensitivity; incorporate contingency triggers into commercial contracts.
-
Integrate manufacturing strategy with commercial planning: For programs targeting rapid, high‑volume commercialization, prioritize CDMOs with proven commercial supply chains and validated fill/finish capacity.
-
Explore M&A and JV structures selectively: For investors and platform owners seeking growth, targeted acquisitions of specialist capacity can accelerate time‑to‑market and capture premium margins in tight supply windows.
Report methodology and sources
-
Primary research: dozens of executive interviews across sponsors, CDMOs, technology providers and regulatory advisors; facility assessments and vendor data collection.
-
Proprietary financial and capacity modelling calibrated to observable supply announcements, commissioning timelines and commercial contracts in the public domain.
-
Regulatory and technical analysis aligned with the latest FDA guidance and peer‑reviewed literature on vector manufacturing practices and analytical expectations.
Final perspective — the strategic value of the report for 2026
For any organization with exposure to cell and gene therapy programs — whether sponsor, CDMO or investor — 2026 is a pivot year. The market’s headline growth trajectory creates opportunity, but the operational and regulatory complexity converts that opportunity into a test of strategic execution. Our report converts market scale and growth into decision‑ready intelligence: where to secure capacity, how to design resilient supply chains, which technology choices shorten time to clinic and which commercial contracts protect program value. The brief you’re reading highlights the core themes; the full report contains the segment‑level forecasts, facility registries, vendor scorecards and contractual playbooks that operational teams need to execute with confidence.
Next steps
-
Download the full report or contact PW Consulting for a tailored briefing and an interactive scenario workshop for your portfolio. Our advisory teams can run bespoke supplier selection, capacity‑allocation and investment models directly against your program timelines.
-
Subscribe to our quarterly Market Monitor to receive rolling updates on capacity announcements, regulatory shifts and the vendor landscape that will affect lentiviral vector supply in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Production Of Lentiviral Vectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com