

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Angiography Contrast Media Market Poised to Grow at a 5.82% CAGR from 2026 to 2032

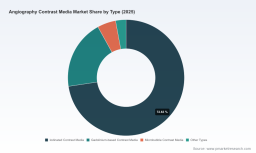
Angiography Contrast Media Market: Strategic Imperatives for 2026 — PW Consulting Outlook
Executive Snapshot
The angiography contrast media market is navigating a period of sustained, mid-single-digit expansion underpinned by diagnostic volume recovery, interventional procedure growth and incremental technology-driven value capture. Our new PW Consulting market study — built on historical analysis from 2020–2025 with 2025 as the base year and a forward-looking forecast to 2032 — projects continued expansion at a compound annual growth rate (CAGR) of 5.82% across the 2026–2032 horizon. In revenue terms (USD, Millions), the market is measured comprehensively in the study and exhibits clear upside through 2032 driven by clinical demand, regulatory developments and evolving capital equipment ecosystems.
Angiography Contrast Media Market
Why This Report Matters for 2026 Decision-Making
- Strategic timing: 2026 is a pivotal year for commercialization and regulatory alignment — recent FDA and CMS updates are reshaping device-contrast interoperability and coding pathways; our analysis decodes their near-term impact on procurement, formulary decisions and product positioning.
- Investment prioritization: With a concentrated supplier landscape (top-three players capture a dominant share and the top-five an even greater share), the report helps companies determine where to allocate R&D and manufacturing CAPEX to sustain defensibility without overexposing to commodity pricing pressure.
- Go-to-market clarity: Shifts in imaging platform capabilities and contrast delivery systems are creating new partnerships and bundling opportunities. The report translates these technical trends into executable commercial playbooks for 2026 market entry and scale-up.
Market Dynamics: Forces Shaping 2026
Several structural and episodic factors converge to set the 2026 agenda:
Angiography Contrast Media Market
- Clinical demand and modality shifts — Ongoing preference for minimally invasive diagnostics and increasing utilization of CT-based angiography are sustaining demand for iodinated and alternative contrast agents. Procedural mix shifts (diagnostic vs. interventional) drive different product and service value propositions for manufacturers and hospital procurement teams.
- Regulation and safety imperatives — Regulatory guidance continues to influence product selection and liability exposure. Recent regulatory advisories emphasize risk mitigation in vulnerable patient populations and reinforce the market differentiation of certain macrocyclic agents with near-zero reported risks in severe renal impairment.
- Reimbursement and coding changes — Updates to CPT coding and CMS reimbursement pathways for diagnostic angiography in 2026 create pockets of margin expansion and contraction depending on how suppliers structure bundled offerings with imaging service providers.
- Technology convergence — Advances in contrast delivery systems, including high‑pressure injectors and smart contrast management platforms, are enabling closer integration between contrast makers and modality OEMs; these integrations are beginning to influence purchasing decisions beyond price alone.
Competitive Landscape — What Leaders Are Doing
The market exhibits high concentration: the top three suppliers capture a substantial share, and the top five an even larger share, leaving limited white space for undifferentiated entrants. Leading multinational pharmaceutical and imaging companies maintain broad portfolios and active regulatory pipelines, while niche players are specializing in contrast-formulation innovation or delivery-system integration.
Angiography Contrast Media Market
- Global pharmaceutical leaders continue to leverage established brand franchises and extensive clinical evidence to protect share and defend pricing in core markets. These firms pair product lifecycle management with targeted regulatory filings to expand labeled uses and system compatibility.
- Imaging OEMs and injectors are executing complementary strategies: approvals for high-pressure injector series and CT platform updates have been secured in recent quarters, reinforcing the trend toward device–contrast co-validation and bundled solutions.
- Regional and specialty manufacturers remain relevant by focusing on regional distribution efficiency, cost-competitive production and tailored formulations for specific clinical protocols.
Recent Industry Developments (Strategic Implications)
- Regulatory clearances for contrast–device compatibility and for next-generation injectors elevate the importance of interoperability. Suppliers should evaluate partnerships and co-marketing agreements to capture procurement tenders where device-validated contrast products command a premium.
- Updates to clinical safety guidance around gadolinium and iodinated agents are shifting hospital formularies and premedication workflows; firms with differentiated safety dossiers can leverage these to negotiate favorable contracting terms with health systems.
- Coding and reimbursement adjustments effective in 2026 create a near-term window to influence service definitions and bundling logic — manufacturers must engage early with payers and professional societies to shape economic outcomes.
Growth & Innovation Vectors
To prosper through 2026 and beyond, stakeholders should pursue a multi‑pronged strategy that balances innovation with operational rigor:
- Product differentiation through safety and efficacy evidence. Investments in comparative real‑world evidence and head‑to‑head clinical trials can convert safety-conscious buyers and unlock premium positioning for macrocyclic and next‑generation formulations.
- Integrated solution models. Coupling contrast media with validated delivery systems and digital dose-optimization tools creates higher switching costs and can justify value-based pricing in integrated delivery networks.
- Manufacturing resilience and regulatory readiness. Given concentrated supply sources for certain raw materials and the elevated regulatory scrutiny on parenteral agents, vertical integration or qualified second-source arrangements should be prioritized in 2026 capital plans.
- Market access engineering. A targeted payer and provider engagement program that maps the new CPT/CMS environment and quantifies per-procedure economics will increase uptake and defend margins amid pricing pressures.
Operational Priorities for 2026
- Refine the product pipeline roadmap to accelerate filings for compatibility and safety labels that translate into clinical preference and formulary inclusion.
- Execute selective partnership pilots with imaging OEMs and injector manufacturers to test co-marketing and bundled procurement models in key health systems.
- Deploy a differentiated value narrative that links clinical outcomes (e.g., reduced adverse events, optimized contrast volume) to hospital operational metrics (e.g., throughput, readmission risk), enabling premium contracting.
- Stress-test supply chain and quality systems against accelerated demand scenarios and potential regulatory inspections; prioritize investments that reduce lead times and secure critical inputs.
M&A and Capital Allocation Playbook
Given market concentration and steady growth dynamics, 2026 is a favorable year for strategic M&A that delivers scale, portfolio breadth or manufacturing robustness. PW Consulting recommends three archetypal transactions:
- Scale acquisitions to consolidate share in fragmented regional markets and achieve step-change cost synergies in distribution and manufacturing.
- Capability bolt-ons to acquire delivery-system interoperability, software-enabled dose optimization or specialty formulations that enhance differentiation versus commodity products.
- Manufacturing platform investments — greenfield or brownfield — to ensure supply security and to qualify for regulated markets, thereby supporting premium price capture.
What the PW Consulting Report Delivers
Our report is designed as an operational toolkit for executive teams preparing 2026 strategies. Key deliverables include:
- Market sizing and forecast model (USD, Millions) with scenario analysis calibrated to modality adoption and regulatory permutations across 2026–2032.
- Competitive scorecards and supplier benchmarking that evaluate clinical dossiers, regulatory position, contract coverage and manufacturing footprint.
- Commercial playbooks for pricing, bundling and OEM partnerships, with play-by-play implementation timelines tailored to hospital procurement cycles.
- Regulatory & reimbursement trackers updated through early 2026, outlining actionable steps for labeling, coding advocacy and payer engagement.
- M&A target screening criteria and valuation heuristics specific to contrast media and related delivery-system assets.
Conclusion — A Roadmap for Executives
The angiography contrast media market presents an attractive, defensible growth opportunity for companies that combine clinical differentiation with strategic partnerships and supply‑chain resilience. With a projected mid-single-digit CAGR in the forecast window and a concentrated supplier base, 2026 is the year to convert market intelligence into concrete moves: accelerate safety‑focused evidence generation, negotiate interoperability agreements, secure manufacturing continuity, and engage payers early on coding revisions.
PW Consulting’s new study provides the data-driven foresight and tactical playbooks leaders need to execute those moves. For full access to the detailed segmentation, per-region and per-application forecasts, subscriber-only datasets, and the complete list of recommended actions validated by scenario modeling, visit our report landing page and download the executive package.
Contact PW Consulting to schedule a bespoke briefing and translate these insights into a 90-day prioritized action plan for 2026.
For detailed analysis of this topic, please visit the official page: Angiography Contrast Media Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com