

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ready-to-Eat Broth Market Poised to Reach USD 4,586.0 Million by 2032

Ready-To-Eat Broth Market — Strategic Outlook for 2026: Why This Report Will Shape Your Next Move
PW Consulting’s latest Ready-To-Eat Broth Market report provides the selective, high-impact intelligence senior leaders need to make confident 2026 strategic decisions. Built on a robust base year (2025) and a multi-scenario forecast period (2026–2032), the study quantifies the macro runway for the category — with the global market size estimated at USD 3,450 million in 2025 and a compound annual growth rate (CAGR) of 4.15% across the forecast horizon, reaching roughly USD 4,586 million by 2032. More importantly, the report translates those headline numbers into practical choices: where to invest, what to reformulate, which channels to double down on, and which competitive moves to pre-empt.
Ready To Eat Broth Market
Why 2026 Is a Pivotal Inflection Point
-
Cost dynamics are bifurcating product strategies. Expanding chicken supplies are exerting downward pressure on broiler prices through early 2026, while wholesale beef is expected to trend higher. These diverging inputs create asymmetric margin opportunities across protein-led SKUs and favor flexible supply-chain strategies.
Ready To Eat Broth Market -
Regulatory momentum — notably proposed front-of-package nutrition labeling and continuing updates to Nutrition Facts requirements — changes how consumers perceive broth as a ‘health’ product. Sodium, saturated fat and added sugar callouts will alter purchase triggers and platform-level merchandising approaches.
Ready To Eat Broth Market -
Consumer usage is evolving: broth is expanding beyond kitchen bases into single-serve sipping, wellness occasions and foodservice back-of-house solutions. New flavor adjacencies and premium ingredient narratives are enabling incrementally higher price points in targeted channels.
What the Report Delivers — Practical, Executable Intelligence
-
Market sizing and seven-year forecasts anchored to 2025, with upside/downside scenarios to stress-test investment cases.
-
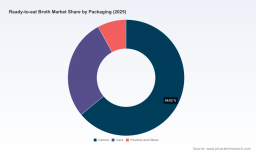
Segmentation frameworks (product type, packaging format, and channel) that map expected margin profiles and growth velocity — presented as decision matrices rather than raw data dumps to support playbook building.
-
Competitive landscaping and capability maps that highlight who is competing on price, convenience, claims (organic, clean-label, bone broth), and culinary authenticity.
-
SKU-level innovation trackers and retailer planogram guidance showing the NPD attributes that convert in mainstream and premium sets.
-
Commercial levers and pricing models: trade promotion optimization, private-label benchmarking, and price–elasticity scenarios tuned to anticipated input cost moves.
-
Supply-chain stress-testing and procurement playbooks for protein sourcing, including contract structures, hedging templates, and supplier diversification strategies.
-
Regulatory impact assessment and reformulation pathway templates to meet emerging front-of-package rules without sacrificing flavor and margin.
-
M&A and partnership screening tools focused on capability gaps (e.g., organic, bone-broth manufacturing, or aseptic carton fills) and accretive tuck-in opportunities.
How to Use These Insights — Priority Moves for 2026
-
Immediate: Audit SKUs through a sodium/saturated-fat lens and prioritize reformulation where regulatory labeling risk intersects with high-visibility SKUs. Use our reformulation scorecard to quantify development cost vs. incremental share gains.
-
Near-term (Q2–Q4 2026): Rebalance promotional spend toward convenience and sipping occasions; test limited-edition flavors that build premium perception with low capex (e.g., spice or infusion variants) to capture incremental margin while sourcing costs normalize.
-
Mid-term: Implement packaging experiments — lightweight aseptic cartons and shelf-stable formats that align with e-commerce and grab-and-go placement. Our SKU cannibalization models forecast channel-level ROI for each packaging pivot.
-
Operational: Secure flexible protein contracts and broaden supplier panels for beef and chicken to blunt raw-material shocks. Leverage contract clauses tied to transparent indexation to shield margins without offloading all cost increases to consumers.
-
Strategic: Build a two-track innovation funnel — defensive (cost-focused, label-compliant versions of mainstream SKUs) and offensive (wellness and premium broths with premium sourcing stories). Our playbooks show ideal resource splits by company profile.
Competitive Landscape — Who Matters and What They Signal
The category exhibits moderate concentration. The top three companies account for a material share of the market, and the top five combine to command a clear majority of shelf presence and national distribution muscle. This structure favors scale players for mainstream retail, while specialty incumbents and DTC brands continue to capture wellness-driven premium pockets.
-
The Campbell’s Company (Swanson, Pacific Foods) — Scale, national retail distribution, and a dual play on mainstream and organic portfolios. Their recent launches underscore a strategy of flavor-led extensions to drive space and incremental trips.
-
Kraft Heinz (Heinz) — Focused on broad-market convenience SKUs and leveraging strong grocery capture to defend core retail bays. Expect tactical price and pack promotions in value channels.
-
Unilever (Knorr) — A global culinary player that competes on flavor credentials and concentration formats suited for both retail and foodservice. Their global reach makes them a strategic ally or rival in international expansion plays.
-
General Mills (Progresso, College Inn via portfolio moves) & B&G Foods (College Inn) — Legacy brands that provide reliable category pull and are well-placed for private-label displacement or co-manufacturing partnerships.
-
Specialty players (Kettle & Fire, Bonafide Provisions, Imagine Foods, Manischewitz) — These brands own the premium/wellness narrative, driving higher ASPs and commanding loyal, health-focused consumers. Recent NPD (e.g., Bonafide’s no-salt-added launch in early 2026) demonstrates agile response to both regulatory pressure and demand for cleaner labels.
-
Ajinomoto and other ingredient-specialists — Provide umami-forward bases and technical know-how for flavor optimization, a key enabler for reformulation without consumer taste loss.
Taken together, these competitors outline three defensible strategic postures for 2026: scale-and-efficiency, premium-wellness differentiation, and portfolio modularity (where companies operate both mainstream and niche banners). Our competitive playbook helps management choose the right posture and execution timeline.
Supply-Chain and Cost Dynamics — Tactical Implications
Input volatility will be a dominant P&L lever in 2026. While poultry supplies are creating short-term relief in broiler costs, beef price inflation pressures will require active margin management for beef-forward SKUs. Companies with flexible formulas, shared co-manufacturing capacity, or hedged procurement will preserve margin and price competitiveness. The report includes procurement templates and sensitivity analyses that quantify margin throughput under a range of commodity scenarios.
Regulatory & Labeling Headwinds — How to Prepare
Proposed front-of-package labeling that flags sodium, saturated fat and added sugars will change competitive dynamics, especially for incumbents relying on heritage formulations high in sodium or fat. Our regulatory playbook offers pathway maps for reformulation timelines, consumer communication strategies, and trade-up plans that maintain flavor while minimizing label risk. These are essential to avoid abrupt assortment removals or costly relabeling programs mid-year.
Why PW Consulting’s Report Is Different
-
We pair rigorous top-down market modeling with bottom-up SKU economics, creating a bridge between headline opportunity and unit-level decision making.
-
Deliverables include interactive scenario tools, promotability dashboards, and an M&A filter that lets executives run rapid “what-if” due diligence on tuck-in targets.
-
The research synthesizes primary interviews with procurement, R&D and category heads, proprietary trader-cost models, and retailer shelf-scans — producing recommendations that are both defensible and immediately actionable.
Next Steps — Where to Focus Investment
For 2026, management teams should prioritize three linked investments: procurement flexibility (to navigate protein divergence), label-compliant reformulation (to reduce regulatory risk), and targeted NPD for sipping/wellness occasions (to capture premiumization). Each lever is modeled in the report with expected payback windows and resource requirements.
PW Consulting’s Ready-To-Eat Broth Market report is designed as a decision engine for 2026 — demonstrating where dollars should be spent, where SKUs should be retired or reformulated, and where partnerships or M&A can accelerate capability. For access to the full dataset, granular segmentation tables, regional and channel breakdowns, company market shares, and the proprietary playbooks referenced here, please visit the report landing page to download the complete study and interactive tools.
For detailed analysis of this topic, please visit the official page: Ready To Eat Broth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com