

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Asia Pacific Leads as Digital Inclinometer Market Tops USD 342.7 Million in 2025, Set to Grow at 6.3% CAGR (2026–2032)

Digital Inclinometer Market Outlook 2026: Strategic Signals for Decision‑Makers
Executive preview
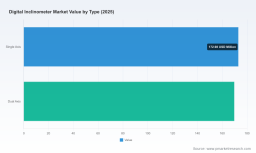
As organizations plan capex, product roadmaps, and M&A activity for 2026, PW Consulting’s new Digital Inclinometer Market research brief provides an evidence‑based compass for near‑term strategic choices. The market for digital inclinometers has demonstrated steady expansion through the first half of the decade, growing from a clearly established base in 2020 to an estimated global market size of 342.7 Million USD in 2025. Our forward view indicates continued momentum across the forecast window, with total market value rising toward 525.58 Million USD by 2032 — reflecting a compound annual growth rate (CAGR) of 6.3% for the 2026–2032 period.
Digital Inclinometer Market
Why this matters for 2026
- Timing of investments: The market’s projected mid‑single digit CAGR signals a predictable expansion phase rather than a hyper‑growth bubble. This dynamic favors staged investments — pilots and modular rollouts in 2026 with scalable spending tied to measurable adoption signals.
- Product roadmaps must prioritize MEMS: Our analysis confirms MEMS architectures now dominate the technical trajectory for digital inclinometers, driven by precision, size, and power advantages. Vendors and OEMs should prioritize MEMS‑based variants and associated signal conditioning/firmware competencies when defining 2026 R&D priorities.
- M&A and partnership playbook: Market concentration metrics indicate a moderate level of consolidation among incumbent vendors. Strategic buyers can manufacture scale advantages by targeting complementary technology stacks (e.g., sensor fusion, ruggedized interfaces) or by acquiring distribution channels in verticals with accelerating demand (infrastructure monitoring, energy, specialized industrial equipment).
- Procurement readiness: System integrators and end users should focus procurement criteria on interface compatibility (common industrial protocols), environmental robustness, and maintainability. Given the maturity of core sensing technology, differentiation increasingly arises from integration, software, and field support.
What the report delivers — hands‑on tools for 2026 decisions
PW Consulting’s full report is structured to move executives from insight to action. Key operational deliverables include:
Digital Inclinometer Market
- Granular market sizing and forecast models with transparent methodology and downloadable data tables (historical series 2020–2025 and forecasts 2026–2032).
- Segmented demand analysis by product type, end use, and channel — presented as scenario models to stress‑test strategic options (note: detailed segment values are reserved for the full report).
- Vendor benchmark dossiers — concise profiles, product stacks, pricing posture, distribution footprint, and a weighted vendor selection matrix tailored for procurement teams.
- Technology deep dives covering MEMS sensor variants, signal processing approaches, communications protocols (RS‑232/RS‑485/Modbus/CAN etc.), and edge analytics patterns.
- Commercial playbooks: go‑to‑market tactics by vertical (construction, structural health monitoring, energy), total cost of ownership templates, and ROI calculators to support business cases in 2026 procurement cycles.
- Risk and compliance heatmaps including quality management indicators, supply chain stress tests, and regulatory change scenarios to prioritize mitigation actions.
- Primary research appendix with interview synopses, test lab findings, and an annotated data‑source register for auditability.
Competitive landscape — who’s shaping the market
The market ecosystem blends specialist sensor houses, industrial OEMs, and broader connectivity players. PW Consulting’s competitive framework evaluates firms on product breadth, interface support, vertical focus, and field reliability.
Digital Inclinometer Market
- Jewell Instruments (Manchester, NH) — A specialist in single, dual and tri‑axis MEMS and force‑balance inclinometers. Strengths include flexible output options (serial and industrial protocols) and a reputation for ruggedized solutions that serve construction and harsh‑environment applications. Their recent Ruby MEMS introductions reflect an ongoing product refresh strategy that improves resolution and responsiveness.
- GEOKON (Lebanon, NH) — Known for geotechnical inclinometer systems and in‑place monitoring solutions. GEOKON is positioned strongly where long‑term structural monitoring and slope stability projects require integrated probe systems and lifecycle service support.
- US Digital (Vancouver, WA) — Focused on absolute optical and networked devices with full‑rotation capability. Their product set appeals to applications needing high angular range and resolution, particularly where networkability and precision interplay (e.g., solar tracking, dredging).
- Level Developments Ltd (Croydon, UK) — Specializes in dual‑axis inclinometers and OEM tilt sensors for machinery and energy applications. Their SOLAR 2 family and catalog updates demonstrate targeted productization for the renewables sector.
- Rieker Inc (Aston, PA) — Concentrates on vehicle and equipment tilt monitoring. Rieker’s offerings are purpose‑built for applications that emphasize human safety and machine stability, such as boom angle systems.
- Fredericks Company (Huntingdon Valley, PA) — Offers a broad range of analog and digital sensor options with strong performance envelopes; a viable partner for precision industrial and environmental monitoring requirements.
- TE Connectivity (Schaffhausen, Switzerland) — Brings scale, system integration capabilities, and automotive/industrial interface know‑how. AXISENSE products with CAN J1939 interfaces illustrate TE’s strategy to serve platform‑level safety and tip‑over protection use cases.
Recent industry developments underscore the market’s quality and product evolution dynamics. For example, a leading supplier completed an ISO 9001:2015 follow‑up audit in early 2026, signaling continuity in quality processes across production lines. Product introductions and catalog refreshes in 2024–2025 further validate a competitive focus on MEMS and interface enhancements.
Technology and application trends shaping 2026 choices
- MEMS as the baseline: MEMS sensors dominate adoption due to their precision, compact form factors, and energy efficiency. This makes them the logical starting point for new product designs and cost optimization exercises.
- From sensor to system: Competitive differentiation has shifted toward signal conditioning, firmware, calibration methodologies, and system integration — not just the sensing element itself. Roadmaps should account for software and life‑cycle services.
- Connectivity and edge analytics: Protocol diversity remains wide (serial, industrial fieldbuses, CAN), while embedded analytics and local filtering reduce downstream data costs and improve maintenance workflows on infrastructure assets.
- Structural health monitoring (SHM) acceleration: Infrastructure modernization and risk management programs are primary demand drivers, calling for long‑term, low‑drift sensors and comprehensive monitoring frameworks.
Actionable recommendations for executives — a 90‑day checklist
- Initiate cross‑functional pilots that validate MEMS‑based sensor platforms with end‑to‑end telemetry and a minimal viable analytics stack.
- Update procurement RFP templates to include interface compatibility, long‑term drift metrics, and vendor quality assurance evidence (ISO and equivalent certifications).
- Prioritize partnerships with firms that can bundle hardware, firmware updates, and cloud ingestion — these combinations reduce integration time and accelerate time‑to‑value.
- Model three adoption scenarios (conservative, base, accelerated) using the PW Consulting forecast to stress‑test capex requests and staffing needs for 2026.
- Scan for tuck‑in M&A targets that offer complementary IP (edge analytics, unique ruggedization) rather than broad horizontal consolidation, unless scale in distribution is the objective.
How to get the full intelligence
This release is a strategic preview intended to orient executive decisions for 2026. The complete Digital Inclinometer Market report from PW Consulting contains the full set of segmented demand estimates, regional and application splits, vendor scorecards, and the underlying data files that power our models. Those detailed segment tables and company score derivations are intentionally withheld from this summary to protect the actionable analytics that our clients value.
For procurement teams, product leaders, investors, and strategy groups preparing plans in 2026, acquiring the full report will provide the downloadable datasets, scenario models, and executable playbooks needed to convert market signals into profitable actions.
About PW Consulting
PW Consulting provides strategic market research and bespoke advisory services for industrial sensors and infrastructure technologies. Our work blends primary technical validation, field testing, and financial modeling to create decision tools executives can rely on. Contact our team for inquiries on licensing the Digital Inclinometer Market dataset or for tailored strategy workshops based on the report’s findings.
For detailed analysis of this topic, please visit the official page: Digital Inclinometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com