

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Anti‑Acne Skin Patches Market Set to Grow at 8.5% CAGR Through 2032, Fueled by Rising E‑commerce Sales

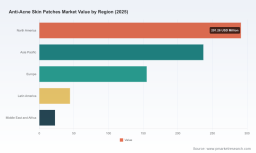
Anti-Acne Skin Patches Market: Strategic Outlook for 2026 — PW Consulting Report Summary
The global anti-acne skin patches market has entered a phase of sustained expansion. Our latest PW Consulting market model shows the market reached approximately USD 750.6 Million in the base year 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 8.5% over the 2026–2032 horizon, arriving at roughly USD 1,328.7 Million by 2032. This trajectory reflects a confluence of durable consumer demand for targeted, low-friction skincare solutions, expansion of direct-to-consumer distribution, and technologic differentiation across product subclasses (hydrocolloid, medicated, and microneedle formats).
Anti Acne Skin Patches Market
Why this report matters for 2026 decision-makers
-
Board-level foresight: The report translates top-line growth into strategic options — from M&A and joint ventures to channel investments — enabling leadership teams to prioritize capital allocation confidently in 2026.
Anti Acne Skin Patches Market -
Commercial playbooks: It supplies execution-ready recommendations for product launches, pricing ladders, and assortment tactics that reflect current consumer behaviors and retailer expectations.
Anti Acne Skin Patches Market -
Risk & regulatory planning: We map regulatory entry points and manufacturing controls for both non-medicated and active-ingredient patches, reducing the regulatory uncertainty that often stalls launches.
-
Supply-side levers: The analysis identifies sourcing and contract manufacturing pathways to shorten lead times and preserve margin — critical as demand scales under the modelled CAGR.
What the report delivers — practical, actionable content
-
Proprietary market model with annualized forecasts to 2032, enabling scenario analysis for multiple investment horizons.
-
Demand-driver diagnostics that quantify the impact of e-commerce growth, retail shelf dynamics, and consumer self-care trends on unit velocity and price mix.
-
Channel and category playbooks — differentiated tactics for DTC, drugstore, and mass-market retail — including SKU rationalization guidance and promotional cadence templates.
-
Manufacturing & sourcing intelligence covering OEM/ODM capacity, required certifications, lead-time benchmarks, and cost levers for hydrocolloid and advanced-format patches.
-
Regulatory decision trees that clarify when a patch is regulated as a Class I medical device versus an OTC drug product under the applicable monograph, along with registration and GMP implications.
-
Competitive positioning maps and a confidential M&A target short-list derived from concentration metrics, capability gaps, and synergies.
-
Consumer segmentation and creative brief templates to accelerate brand positioning, messaging, and retail storytelling for different age cohorts and treatment-use cases.
Competitive landscape — leaders, challengers & the manufacturing backbone
The market structure is characterized by a mix of high-profile consumer brands, heritage industrial players entering the category, and a robust set of contract manufacturers enabling rapid scale-up. Market concentration metrics indicate a moderate level of consolidation: the top three firms account for a meaningful share, while the top five increase that share further — a structure that supports both collaborative partnerships and bolt-on consolidation strategies.
Brand-led competitors such as Hero Cosmetics, COSRX, Rael, Starface, and ZitSticka drive category awareness through differentiated product design and targeted marketing. Hero Cosmetics and COSRX remain exemplars of hydrocolloid-led retail success, leveraging strong brand recognition and broad retail distribution. Rael and Starface emphasize product aesthetics and discreet application, catering to consumers who prioritize formulation and visibility. ZitSticka’s focus on micro- and micropoint technologies addresses deeper cystic lesions, signaling a push toward clinical differentiation within a largely OTC category.
At the other end of the value chain, large consumer-health incumbents including Church & Dwight and 3M bring scale, retail relationships, and channel breadth that can compress shelf lifecycle times for emergent brands. Premium skincare houses such as Peter Thomas Roth participate by extending credibility and pricing power through established brand equity.
Equally strategic are contract manufacturers and material specialists — Amparo Medical Technologies, Hi-Tech Products, ZenPro, DERMATECH, Taiki, Lessonia, and Guangzhou Dunxin among them. These companies supply medical-grade hydrocolloid substrates, custom active integrations, and private-label services that reduce go-to-market complexity for brand owners. Their adherence to ISO 13485, ISO 9001, and, where applicable, FDA registration is a key gating factor for scaling any higher-margin medicated or claim-intensive SKUs.
Recent developments and what they imply
-
The release of new hydrocolloid formulations and catalog expansions from European and Asian manufacturers indicates ongoing product innovation and an intensifying private-label opportunity set.
-
Manufacturing capability updates from contract producers reinforce the sector’s preparedness to absorb additional brand launches and regional diversification — a vital dynamic against potential supply-chain disruptions.
-
Industry guides and market analyses published late in 2025 show a rising emphasis on vegan formulations and sustainability claims, which will become differentiating attributes for premium segments.
Regulatory, manufacturing and reimbursement considerations
From a regulatory standpoint, the distinction between non-medicated hydrocolloid patches and medicated (e.g., salicylic acid-containing) patches is material. Non-medicated hydrocolloid devices are generally regulated as Class I devices under the relevant product code, while patches with salicylic acid within typical OTC concentrations fall under the OTC Monograph framework. Patches making drug claims or containing actives beyond monograph allowances will typically require FDA establishment registration, listing, and demonstrable GMP controls. Many manufacturers have already adopted ISO 13485:2016 and ISO 9001:2015 frameworks and maintain FDA registrations — prerequisites for entering major retail and institutional channels.
On reimbursement, consumer anti-acne patches remain largely OTC and self-paid; we found no recent CPT or DRG updates that create coverage pathways. This reality reinforces the importance of consumer pricing strategy and channel placement as primary levers for revenue growth.
Strategic imperatives for 2026
-
Prioritize channel-tailored product portfolios: differentiate SKUs for DTC discovery versus pharmacy shelf economics.
-
Secure certified contract manufacturing with geographic redundancy to reduce lead-time and tariff risk.
-
Invest in clinical differentiation where warranted (e.g., microneedle formats) but balance claims risk against regulatory complexity.
-
Leverage private-label partnerships to penetrate mass and international channels quickly without large CapEx.
-
Use acquisition or minority investment to capture niche technologies or faster-growing regional footprints — the market’s current concentration profile rewards both scale and unique IP.
-
Embed sustainability and ingredient transparency as part of product roadmaps — these features resound with core consumer cohorts and can command premium pricing.
How PW Consulting can support your 2026 agenda
PW Consulting’s Anti-Acne Skin Patches Market Report pairs a rigorous, bottom-up market model with practitioner-ready tools: competitive scorecards, sourcing playbooks, regulatory decision trees, and confidential M&A shortlists. For executive teams seeking to convert the market’s projected CAGR into predictable, defensible growth, the report reduces executional risk and clarifies priority bets.
Note: this summary intentionally omits detailed regional and application-level splits and proprietary unit economics to preserve the report’s strategic value. The full report contains these segmented datasets, confidential company-level benchmarking, and downloadable financial models available on our website.
To obtain the complete intelligence package — including the full segmented forecasts, sensitivity scenarios, and the confidential M&A target list — please visit our report page or contact PW Consulting’s Strategy Desk for an executive briefing tailored to your organisation’s 2026 roadmap.
For detailed analysis of this topic, please visit the official page: Anti Acne Skin Patches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com