

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Portable Keratometer Market to Grow at a 6.75% CAGR, Reaching USD 115.5 Million by 2032

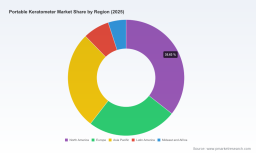
Portable Keratometer Market — Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s latest Portable Keratometer Market report (base year 2025; forecast 2026–2032) is a focused strategic briefing designed to inform capital allocation, product roadmaps, and commercial strategies for the coming three to seven years. The market is on an unmistakable upward trajectory — reaching USD 73.15 Million in 2025 and expected to cross USD 81.0 Million in 2026 — with a compound annual growth rate (CAGR) of 6.75% across the forecast horizon and a projected market size north of USD 115 Million by 2032. For executives evaluating investments, partnerships, or competitive maneuvers in 2026, the accompanying analysis translates these macro dynamics into actionable options while preserving the detailed segmentation and financial models for subscribers.
Portable Keratometer Market
Why this report matters in 2026
-
Timing of strategic moves: With steady, mid-single-digit CAGR growth, 2026 represents a phase of consolidation and targeted expansion rather than explosive disruption. Firms that move now — to secure distribution, validate field performance, or shore up regulatory dossiers — will be better positioned to capture the most profitable growth pockets through 2032.
Portable Keratometer Market -
Shift from clinic to point-of-care: Portable keratometers are transitioning from niche tools used in outreach and mobile clinics to mainstream instruments supporting hospital outreach programs, ambulatory surgery centers, and tele-ophthalmology workflows. This shift alters procurement criteria — from pure metrology to connectivity, integration with biometry/refraction platforms, and post-market support.
Portable Keratometer Market -
Risk profile for investors: The market exhibits moderate concentration, with the top three players holding a meaningful portion of revenue and the top five commanding a clear majority of share. This structure creates both entry barriers and attractive M&A opportunities for established players seeking complementary technology or channel reach.
Report contents — built for operational decision-making
-
Market sizing and forecast: A granular, bottom-up estimate covering 2020–2025 historicals and 2026–2032 forecasts (presented in USD Million), plus sensitivity scenarios that reflect technology adoption and regulatory outcomes.
-
Demand-side diagnostics: Buyer personas, purchasing workflows (clinic, outreach, procurement cycles), reimbursement touchpoints, and clinical adoption drivers that determine speed-to-revenue for new entrants.
-
Supply-side playbook: Component sourcing risks, manufacturing cost buckets, service and warranty models, and channel economics for distributors and OEMs.
-
Technology trajectories: Comparative assessment of sensing modalities (including wavefront-based and traditional reflection patterns), software integration, mobile app ecosystems, and validation protocols required for surgical planning and pre-op workflows.
-
Regulatory and standards matrix: Step-by-step compliance pathways for major markets (including premarket notifications and conformity assessments), plus an assessment of clinical evidence expectations and post-market surveillance obligations.
-
Competitive benchmarking: A vendor scorecard covering technical capability, go-to-market strength, and strategic risk — informed by primary interviews and proprietary scoring.
-
Go-to-market playbooks: Product launch sequencing, channel strategies (direct sales vs. distributor partnerships), and prioritized use cases for commercial pilots aligned to revenue uplift timelines.
-
Appendices: Primary research transcripts, methodology notes, and downloadable financial models for scenario planning.
Competitive landscape — players to watch and strategic implications
The competitive field blends specialist innovators, established ophthalmic OEMs, and cost-focused regional manufacturers. Market concentration metrics point to an environment where a small set of vendors shapes purchasing norms and platform expectations. Key companies profiled in the report include:
-
Micro Medical Devices (United States) — Offers handheld keratometer probes and integrated biometry platforms optimized for mobile use. Their field deployments underscore the importance of ruggedized hardware, simple workflows, and bundled services in outreach settings. Strategic take: established field validation reduces adoption friction in mission-based and community eye-care programs.
-
PlenOptika (United States) — Differentiates through wavefront aberrometry and an ecosystem approach that tightly couples hardware with a companion mobile app. Recent software updates demonstrate how rapid iteration of user-facing software can extend device value beyond raw metrology into workflow productivity gains. Strategic take: software-first innovations can command premium pricing and accelerate channel adoption if they prove robust in clinical settings.
-
NIDEK (Japan) — A legacy ophthalmic OEM that brings portability into a broader clinical equipment portfolio. Their positioning highlights the advantage of integrated sales coverage and cross-selling into established accounts. Strategic take: incumbent OEMs will leverage installed-base relationships to push hybrid bundles that include portable devices.
-
Marco (United States) — Provides portable referral solutions focused on accuracy and ease-of-use. Strategic take: differentiation through service agreements and clinical support can be as important as pure device specs.
-
Devine Meditech (India) — Represents a class of value-oriented manufacturers targeting price-sensitive markets with rugged, low-cost handheld devices. Strategic take: aggressive cost-performance propositions will shape procurement decisions in emerging markets and influence pricing benchmarks globally.
-
Reichert (AMETEK, United States) — As part of a larger diagnostics portfolio, Reichert emphasizes channel leverage and integration into comprehensive diagnostic suites. Strategic take: portfolio breadth and channel depth create durable competitive advantage for capital equipment procurement.
-
Huvitz (South Korea) — Supplies portable-compatible refraction products and competes on engineering quality and value. Strategic take: OEMs balancing price and feature-rich designs can undercut high-margin players while maintaining acceptable clinical performance.
Regulatory and standards landscape — what to prioritize
-
Regulatory classification and premarket pathways: In the U.S., auto-keratometers are regulated as Class II devices and typically require 510(k) clearance. This has implications for development timelines and clinical evidence generation. The EU’s Medical Device Regulation (MDR) introduces stringent conformity and post-market surveillance obligations in that market. Companies must plan for longer time-to-market and increased evidence collection costs.
-
Standards compliance: ISO 15004-1:2020 sets fundamental requirements and test methods for non-invasive ophthalmic devices. Demonstrable adherence to recognized standards reduces regulatory friction and supports procurement decisions in credential-driven institutions.
-
Commercial implications: Regulatory timing will materially affect when products can be included in bundled surgical suites or telehealth solutions. Firms should synchronize regulatory milestones with commercial pilots and reimbursement pathways to avoid costly launch delays.
Recent developments that shape near-term strategy
-
Product and software evolution: A prominent handheld device maker released an updated companion mobile app in early 2025, enhancing the usability and data integration of a clinically-oriented handheld keratometer. This underscores the market’s move toward software-enabled device differentiation.
-
Field validation and outreach evidence: A vendor deployed integrated biometry and keratometry systems in a large-scale mission in late 2025, demonstrating the commercial value of field-validated solutions that reduce clinical time per patient and increase throughput.
Key strategic takeaways for executives planning in 2026
-
Prioritize integrated solutions: Buyers increasingly favor devices that integrate with EMR, biometry suites, and telehealth platforms. Hardware-only plays will face pressure unless paired with compelling software or services.
-
Invest in regulatory capital early: Given the regulatory complexity in major markets, allocate budget and talent for clinical validation and post-market surveillance now to avoid launch slippage.
-
Balance price with clinical trust: In many procurement settings, validated clinical performance and service support trump cost alone. Consider trials, KOL endorsements, and third-party validations as part of the commercial launch.
-
Leverage partnerships for distribution: For newcomers, partnering with established ophthalmic OEMs or distributors accelerates access to surgical centers and hospital networks.
-
Targeted M&A and licensing: With a moderate degree of market concentration, strategic acquisitions (niche metrology, software platforms, or regional distribution) can quickly move the needle on market share and margin.
-
Design for field realities: Durability, battery life, ergonomic workflows, and simple calibration procedures matter in outreach and resource-constrained environments — design choices here directly affect adoption and retention.
Conclusion — a pragmatic roadmap to action
For decision-makers in 2026, the Portable Keratometer Market presents a steady-growth opportunity that rewards focused, evidence-driven strategies. The market’s mid-single-digit CAGR and predictable expansion give companies time to execute deliberate plays — but they must act with clarity on regulatory sequencing, software integration, and channel execution. This report translates the available macro trajectory into practical steps for product, commercial, and M&A leaders while reserving the proprietary segmentation, regional breakdowns, and vendor scorecards for subscribers.
Access the full analysis
PW Consulting’s full report contains the confidential segmentation, regional models, detailed vendor benchmarking, and downloadable scenario models necessary to convert insight into investment-grade action. Executive teams ready to accelerate decisions in 2026 should consult the full report to unlock the granular analytics and prescriptive implementation plans that sit behind the strategic conclusions summarized here.
For detailed analysis of this topic, please visit the official page: Portable Keratometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com