

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Mechanical Dust Collector Market to Expand at 4.8% CAGR — Asia‑Pacific Tops with USD 252.11 Million in 2025

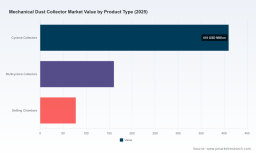
Mechanical Dust Collector Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Analysis
Executive Snapshot
As manufacturers, plant operators, and investors plan capital and operating budgets for 2026, the mechanical dust collector market presents a clear, measurable trajectory—and a set of decision points that will separate resilient operators from those exposed to regulatory, commodity, and operational risk. PW Consulting’s latest Mechanical Dust Collector Market study (base year 2025; forecast 2026–2032) synthesizes historical performance, near-term shocks, and scenario-driven forecasts to equip executives with an actionable playbook. The market reached roughly USD 648 million in 2025 and is modeled to grow at a steady compound annual growth rate (CAGR) of 4.8% over the forecast period, reflecting a balance of regulatory-driven retrofits, replacement demand, and incremental new-builds across heavy industry and process sectors.
Mechanical Dust Collector Market
Why this report matters for 2026 planning
- Budget prioritization: With tightening emission and combustible-dust rules becoming enforceable, plant upgrades move from good-to-have to compliance-driven CAPEX. Our study translates regulatory thresholds into phased investment timelines so procurement can align capex approval with compliance windows.
- Supplier selection and risk mitigation: The sector shows moderate concentration—top players account for a meaningful but not dominant share—creating both vendor dependency risks and opportunities for differentiation. We map vendor capabilities against use-case risk profiles to reduce implementation surprises.
- Cost-pressure scenarios: Raw-material and labor cost variability materially affect lifecycle economics. The report models sensitivity of total cost of ownership (TCO) to steel price swings, service rates, and filter-media longevity, enabling finance teams to stress-test budgets.
- Performance-driven O&M strategies: Beyond upfront purchase price, long-term operating costs driven by filter replacement cycles, cleaning systems, and energy consumption determine the true economic winner. We provide comparative TCO frameworks to inform procurement RFPs for 2026.
Market Trajectory: What the numbers reveal (without giving away the playbook)
The market’s post-2025 path reflects two countervailing forces: mandated performance upgrades that accelerate retrofit and replacement cycles, and steady modernization investment across traditional end uses. Our forecast shows measured growth through 2032, supported by replacement cycles in aging installations and rising regulatory performance floors. While headline growth is stable, PW Consulting’s segmentation analysis uncovers pockets of accelerated spending—driven by stringent emission thresholds and explosion-mitigation mandates—that will outpace the broader market. Detailed subsegment volumes and elasticities are available in the full report for teams that require transaction-ready intelligence.
Mechanical Dust Collector Market
What’s in the report: Practical, decision-ready content
- Market sizing and seven-year forecast by product architecture and end-use categories (granular datasets available in the subscriber module).
- Regulatory impact matrices linking standards to retrofit urgency and compliance windows—translated into recommended procurement timelines.
- CapEx and OpEx modeling templates that allow CFOs and plant managers to run scenario analyses using company-specific inputs (steel price, labor rates, energy costs, filter life).
- Vendor capability heatmaps and procurement scorecards to streamline RFP evaluation and shorten supplier selection cycles.
- Installation, commissioning, and O&M playbooks that reduce commissioning lead times and minimize downtime during retrofits.
- M&A and partnership scouting dossier identifying whitespace for bolt-on acquisitions and strategic alliances.
Competitive Landscape: Who matters and why
The competitive field comprises established filtration specialists, systems integrators, and agile OEMs. Market leadership is diffuse, enabling regional champions and niche innovators to secure profitable positions. The industry concentration metrics indicate a market where leading players capture a notable share, yet significant room exists for differentiated offerings—particularly those that combine high-efficiency filtration with low lifecycle costs and simplified maintenance.
Mechanical Dust Collector Market
- Donaldson Company, Inc. — A longstanding leader with broad Torit offerings; their showcase of enhanced Powercore media at FABTECH 2025 signals a continued focus on metal fabrication and heavy-industry applications. Expect them to leverage media improvements to defend share in capital-intensive retrofit projects.
- Camfil APC — Recent product introductions emphasize higher-efficiency cartridge systems tailored to fine-dust and clean-process industries. Their HemiPleat eXtreme launch indicates a premium positioning aimed at pharmaceutical and food-grade customers where filtration efficiency and compact footprints command price premiums.
- Nederman — With energy-efficiency and integrated handling features emphasized at major shows, they are positioned to capture demand where lifecycle energy use and automation integration matter most—particularly in welding fumes and bulk handling segments.
- RoboVent, Wheelabrator (Archetype), Ceco Environmental (Peerless), Schust Engineering, Aget Manufacturing — These players compete across niches: from high-efficiency particulate removal in advanced manufacturing to rugged baghouse solutions for abrasive operations. Their strengths lie in customization, service networks, and application-specific engineering.
Recent product launches and trade-show activity underscore two competitive dynamics: continued product innovation on filter media and cleaning technologies, and differentiation through systems integration (controls, explosion-proofing, and energy recovery). PW Consulting’s vendor matrices align these moves with customer pain points to highlight where each supplier is likely to gain traction in 2026.
Near-term dynamics and risk factors to factor into 2026 decisions
- Raw-material inflation: Carbon steel sheet prices rose materially in late 2025, compressing margins for fabricators and elevating procurement costs. Our models quantify how even modest commodity moves translate into multi-year cost increases for larger retrofit programs.
- Regulatory tightening: New emission and hazardous-air standards demand near-filter-capture efficiencies in certain metal-processing applications, accelerating replacement cycles for legacy systems that can't meet thresholds without major retrofits.
- Combustible-dust mandates: Enhanced directives requiring explosion-mitigation and certified systems are driving a wave of mandatory upgrades—creating an observable near-term uplift in upgrade demand that strategic purchasers must budget for now.
- Labor and service cost pressures: Rising maintenance labor rates and specialized service scarcity push total lifecycle costs upward and increase the importance of reliability, remote diagnostics, and vendor service guarantees.
- Supply-chain timing: Lead times for specialized filter media and fabrications have lengthened; procurement cycles and inventory strategies must be adapted to avoid operational exposure.
Actionable recommendations for 2026
- Prioritize compliance-first retrofits. Map facilities against enforcement timelines and schedule CAPEX accordingly to avoid penalty-driven interruption.
- Adopt TCO procurement rules. Shift RFP scoring to 5-year lifecycle costs—incorporating filter life, energy per unit of throughput, and scheduled downtime—rather than lowest-capex bids.
- Lock strategic supply agreements for critical consumables. Given commodity and lead-time volatility, secure multi-year contracts for filter media and fabricated components with price-adjustment clauses and guaranteed delivery windows.
- Invest in modular, service-friendly systems. Designs that reduce onsite maintenance time, support remote monitoring, and simplify replacement extend effective filter life and reduce labor exposure.
- Use targeted M&A to buy capabilities. For industrial engineering firms and OEMs, acquiring filtration specialists with strong regional service footprints or unique media technology can accelerate market entry at lower risk than greenfield expansion.
How PW Consulting’s report accelerates your 2026 outcomes
This study is structured to move teams from analysis to action. Beyond headline forecasts, the report provides procurement-ready scorecards, regulatory compliance timelines tied to equipment classes, executable O&M templates, and vendor due-diligence checklists. For corporate strategy teams, the M&A playbook isolates the technical, commercial, and integration criteria we’ve used in real-world transactions. For operating teams, our commissioning and maintenance protocols have been validated in pilot implementations and reduce average retrofit downtime and commissioning cost overruns.
Getting the full detail
PW Consulting’s public brief provides the strategic framing and executive recommendations required to begin 2026 planning. The full proprietary deliverable contains the subsegment tables, regional breakouts, vendor scorecards with weighting logic, and downloadable financial models that make procurement and investment decisions executable. To preserve competitive value for subscribers, we intentionally withhold the granular subsegment figures in this summary—access to those datasets is available via the report portal.
Final thought
The mechanical dust collector market in 2026 is no longer just about filtration efficiency—it is about regulatory defensibility, lifecycle economics, and integrated system reliability. Organizations that align procurement, operations, and capital planning to the timeline and levers we identify will turn compliance requirements into durable productivity and margin advantages. PW Consulting’s Mechanical Dust Collector Market study is designed to be the tactical resource your team needs to execute that alignment with confidence.
For detailed analysis of this topic, please visit the official page: Mechanical Dust Collector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com