

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cone Beam Imaging (CBCT) Market to Reach USD 3,222.42 Million by 2032 at an 8.25% CAGR — North America Leads with USD 735.09M, Top 3 Firms Hold 58.4%

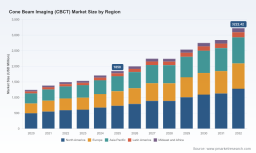
Cone Beam Imaging (CBCT) Market — 2026 Strategic Brief
Market snapshot: a fast-growing, concentrated opportunity
The global Cone Beam Imaging (CBCT) market is entering a decisive phase for corporate strategy. PW Consulting’s latest market model shows the market expanding from approximately USD 1,850 million in 2025 to more than USD 3,220 million by 2032, representing a compound annual growth rate (CAGR) of 8.25% across the forecast horizon. This trajectory reflects sustained demand across dental and orthopedic imaging, accelerating product refresh cycles, and a second wave of adoption driven by AI-enabled diagnostic tools and system-level workflow integration.
Cone Beam Imaging Cbct Market
Why this report matters for 2026 decision-making
-
Timing for capital allocation: as hospitals and high-volume dental groups translate strategic imaging roadmaps into spend, 2026 will be a year when planned capital expenditures either accelerate or are deferred based on demonstrated ROI and reimbursement clarity.
Cone Beam Imaging Cbct Market -
Product strategy inflection: hardware differentiation alone is losing purchase influence; integrated software, AI-driven clinical decision support, and service-enabled business models now determine market access and lifetime value.
Cone Beam Imaging Cbct Market -
Regulatory and reimbursement uncertainty: recent AI 510(k) clearances have opened a commercialization window, but inconsistent reimbursement frameworks still create adoption friction in many markets. Strategic winners will be those who can navigate regulatory pathways while de-risking payer conversations.
-
Consolidation dynamics: the market exhibits high concentration at the top (our market-concentration metrics show a strong top-three/top-five dominance), creating both barriers for new entrants and M&A opportunities for incumbents and PE-backed challengers.
What PW Consulting’s CBCT report delivers — practical, actionable intelligence
This is not a descriptive brochure: the report is a toolkit for executives and investment committees. Key deliverables include:
-
Transparent market sizing and growth model (base year 2025; forecast 2026–2032) with scenario variants for conservative, base, and accelerated adoption pathways.
-
Clinical adoption playbooks that translate imaging capability into workflow ROI by care setting (dental chains, private practices, hospital radiology departments, specialty orthopedic centers).
-
Provider procurement and tender playbooks — pricing anchors, service-level benchmarks, and lifecycle TCO templates tailored for high-volume buyers.
-
Regulatory pathway maps and a compliance readiness checklist for AI-enabled modules and Class II devices, including FDA 510(k) strategy guidance.
-
Commercial due-diligence kits: vendor scorecards, comps for M&A, and a prioritized target universe for strategic partnerships or bolt-on acquisitions.
-
Operational modules: supply-chain risk matrices, manufacturing scale-up checklists, and aftermarket service & consumables margin models.
-
Investor-facing scenarios and valuation sensitivity analyses that convert market-share assumptions into revenue and margin outcomes for 2026 planning cycles.
Competitive landscape — who matters and why
The competitive map blends established imaging OEMs with specialist orthopedic device makers and a rising set of AI-first software vendors. PW Consulting’s qualitative and quantitative assessment spotlights strategic positioning, core competencies, and likely vectors of competition over the next 24 months.
-
Dentsply Sirona (Charlotte, NC, USA) — Strength: broad dental OEM footprint and integrated diagnostic-treatment workflows. Strategic focus should be on leveraging installed base for cross-sell of software subscriptions and chair-side guidance tools.
-
Planmeca Oy (Helsinki, Finland) — Strength: imaging systems with low-dose and integrated facial 3D capture. Recent product introductions targeting North America indicate an aggressive commercial expansion; expect intensified marketing and localized service investments.
-
VATECH Co., Ltd. (South Korea) — Strength: engineering focus on dose optimization and imaging resolution. Competitive tactics include value-priced bundles and distributor-driven channel penetration in emerging markets.
-
Carestream Dental (Atlanta, GA, USA) — Strength: multi-field-of-view platforms and AI-enabled features. Carestream is well-positioned to play the hardware-plus-software subscription game for midsize dental groups.
-
J. Morita (Kyoto, Japan) — Strength: clinical depth in endodontics and high-resolution applications. Their clinical credibility makes them a preferred partner for specialty workflows and academic validation studies.
-
Cefla S.C. / NewTom (Imola, Italy) — Strength: diversified applications across dental, medical, and veterinary segments. Their route to market emphasizes clinical versatility and cross-segment platform reuse.
-
CurveBeam AI (USA) — Strength: extremity/weight-bearing CBCT systems with orthopedic focus. A differentiated clinical niche that can be scaled through hospital partnerships.
-
Asahi Roentgen & PreXion (Japan) — Strengths: compact designs and high-resolution units favored by specialty dental clinics and radiology centers that prioritize image fidelity.
-
AI entrants (Overjet, Pearl, Orca Dental AI/CephX) — Recent 510(k) clearances for AI tools make these vendors pivotal partners or acquisition targets. Their value proposition—interpretable AI overlays and workflow automation—dramatically shortens diagnostic cycle-times and boosts per-scan monetization.
Recent industry developments and regulatory context
-
2025–2026 saw multiple AI-enabled CBCT modules secure FDA 510(k) clearances, validating the pathway for clinical decision-support add-ons and enabling new reimbursement conversations for higher-complexity image review workflows.
-
Product launches from established OEMs are targeting North American expansion with devices optimized for dose reduction and multi-modality imaging — expect intensified competition on service, training, and bundled software.
-
Reimbursement policy remains the single-largest demand-side friction in many markets. While CBCT is recognized clinically for certain indications, comprehensive and harmonized payer coverage is not yet universal, requiring commercial teams to build value dossiers and health-economic evidence.
-
Capital-intensive buyers (hospital systems) are increasingly favoring scalable, high-capacity units with enterprise-level PACS integration; independent dental buyers favor compact, cost-efficient devices with short payback periods.
Strategic plays for 2026 — prioritized and operational
-
Bundle hardware with recurring software revenue: Transition product pricing toward lower upfront hardware prices combined with SaaS for AI/analytics, treatment planning, and preventive-care modules to stabilize revenue streams.
-
Invest in clinical validation and payer evidence: Sponsor prospective studies that quantify diagnostic yield, treatment changes, and downstream cost offsets to support local reimbursement negotiations.
-
Targeted M&A and partnerships: Acquire or partner with AI vendors that already have regulatory clearance to accelerate time-to-market for integrated solutions.
-
Service & training as differentiation: Build premium service tiers, remote-monitoring capabilities, and certified training programs to increase switching costs and aftermarket margins.
-
Regulatory-first product roadmaps: Align product development with anticipated regulatory guidance on AI transparency and real-world performance monitoring to avoid post-market surprises.
-
Channel and geography sequencing: Prioritize market entries where reimbursement and hospital capex trends support faster adoption; use localized clinical champions and distributor economics to accelerate penetration.
-
Supply-chain resilience: Near-shore critical subassemblies where possible and build spare-part pools to protect uptime for key accounts — a critical sales point for high-utilization buyers.
How to use this PW Consulting report in 2026 planning cycles
Executives should treat the report as both an input to strategic planning and an execution playbook. Use the report to: (1) stress-test 2026 budgets with scenario-linked demand curves, (2) prioritize R&D and M&A candidates against a validated scorecard, (3) align commercial incentives to new bundled revenue models, and (4) equip regulatory and clinical teams with a roadmap for FDA and payer engagement.
Final note — depth available behind this brief
This brief demonstrates the strategic lenses and operational frameworks PW Consulting applies to the CBCT market. To preserve competitive integrity and to follow our “trailer” approach, detailed segment tables, granular regional and application splits, and full vendor financials are withheld here. The full report contains the downloadable datasets, heatmaps, and executable templates referenced above.
For access to the complete CBCT Market Report, the interactive dashboards, and tailored advisory workshops for your 2026 planning cycle, contact PW Consulting’s Life Sciences & Imaging practice.
For detailed analysis of this topic, please visit the official page: Cone Beam Imaging Cbct Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com