

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Maskless Lithography Systems for Semiconductor Packaging to Expand at 11.48% CAGR Through 2032

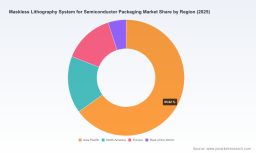
Maskless Lithography System For Semiconductor Packaging Market — Strategic Snapshot for 2026 Decision-Makers
PW Consulting’s latest market research on Maskless Lithography Systems for Semiconductor Packaging delivers an actionable strategic blueprint for executives, investors, and technology leaders planning investments and go-to-market moves in 2026. This release summarizes the report’s high-level findings, explains the decision-useful analyses inside, and highlights key competitive and technology dynamics that will determine winners and losers as the market scales toward advanced packaging adoption.
Maskless Lithography System For Semiconductor Packaging Market
Why This Market Matters Now
Maskless lithography has moved beyond laboratory novelty into a core enabling technology for advanced packaging. Driven by heterogeneous integration, chiplet-based architectures for AI/HPC, and the need to process large, warped panel and wafer substrates with high design flexibility, maskless approaches reduce time-to-market and capital tied up in photomask inventories. Our base-year assessment (2025) places the market in the high hundreds of USD Million, and the forecast shows robust, sustained expansion: the global market grows into the low billions by the end of the 2026–2032 forecast window under an 11.48% compound annual growth rate (CAGR). This trajectory reflects both mid-volume manufacturing adoption and pilot-to-production migrations at scale.
Maskless Lithography System For Semiconductor Packaging Market
Top-Line Market Trajectory (select milestones)
- Established growth path from 2020 through 2025 shows accelerating adoption as packaging foundries and OSATs internalize maskless advantages.
- 2026 marks an inflection where high-throughput systems and sub-2 µm resolution capabilities enable direct substitution in many back-end lithography steps.
- By the end of the forecast horizon, total market value is projected to exceed a billion USD on an annual basis, driven by penetration into fan-out, panel-level processes, and 2.5D/3D integrations.
Note: This communication is a strategic summary. Detailed segment-level figures, regional and application breakdowns, and customer-level forecasts are reserved for the full report.
Maskless Lithography System For Semiconductor Packaging Market
What the Report Contains — Practical, Executable Intelligence
PW Consulting’s full study is designed for practitioners who must convert insight into action in 2026 and beyond. The report combines quantitative forecasting with operational playbooks, including:
- Market sizing and trend extrapolations calibrated to 2020–2025 historical performance and stress-tested scenarios for 2026–2032.
- Technology roadmaps comparing maskless modalities (e.g., SLM-based projection, laser direct imaging, digital micromirror-based approaches), with throughput, resolution, footprint, and TCO matrices for procurement decisions.
- Vendor benchmarking and scorecards that rate suppliers across capability dimensions — resolution, stitch-free patterning, throughput scalability, die-shift compensation, service & spares ecosystem, and geographic delivery risk.
- Go-to-market and deployment playbooks tailored by buyer persona: packaging foundries, OSATs, panel converters, and IDM advanced packaging groups.
- CapEx optimization templates to compare maskless investment versus legacy photomask workflows, including lifecycle maintenance, materials consumption, and sustainability KPIs.
- Risk matrices addressing supply chain, export controls, and regional manufacturing dependencies — and mitigation strategies for procurement, localization, and dual-sourcing.
- Case studies and adoption pathways derived from early high-volume adopters that demonstrate migration timelines from pilot to production.
These components make the report immediately actionable for procurement teams, R&D heads, and corporate strategy groups shaping 2026 budgets and multi-year roadmaps.
Competitive Landscape — Capabilities to Watch
The market shows a degree of concentration: the top three suppliers command a majority share and the top five capture over three quarters of activity. That structure has strategic consequences for buyers and new entrants: scale matters for service networks and software ecosystems, but niche specialists still capture high-value, application-specific wins.
- Heidelberg Instruments (Heidelberg, Germany) — Offers the MLA 300 Maskless Aligner optimized for wafer-level and packaging applications. Its strengths are rapid design customization, die-shift compensation, and sub-micron to low-micron resolution in mid-to-high volume contexts. Heidelberg’s positioning is attractive for customers prioritizing flexibility and software-driven process controls.
- EV Group (EVG) (St. Florian, Austria) — EVG’s MLE and LITHOSCALE platform (including the LITHOSCALE XT) are engineered for high-volume manufacturing in heterogeneous integration. Capabilities such as stitch-free full-wafer patterning, sub-2 µm resolution, and die-shift compensation make EVG a frontrunner where throughput and stitch accuracy are gatekeepers to production migration.
- Nikon Corporation (Tokyo, Japan) — The DSP-100 Digital Lithography System brings SLM-based direct projection with 1.0 µm L/S capability and warpage correction to large substrates. Nikon’s optical heritage and system integration strengths make it a compelling choice for customers demanding fine-line resolution alongside robust process controls.
- SCREEN Holdings (Kyoto, Japan) — Known for LDI and maskless systems such as LeVina, SCREEN targets high-throughput package substrate processing for telecommunications and IoT infrastructure, balancing resolution and throughput for large-volume applications.
- SÜSS MicroTec (Garching, Germany) — Provides a mix of maskless exposure and projection lithography solutions aimed at specialty and flexible integration processes, suitable for customers requiring a blend of legacy and emerging process compatibility.
- In-Vision Technologies AG (Austria) — Supplies PANDIA digital light engines and focuses on micron-scale patterning without photomasks, carving a technical niche for wafer- and panel-level solutions.
- Applied Materials (Santa Clara, USA, in partnership with Ushio) — Collaborates on Digital Lithography Technology (DLT) for large glass and package substrates, aligning with chiplet and heterogeneous integration trends favored by hyperscalers and advanced foundries.
- Regional and emerging players — Several China- and Japan-based firms are advancing direct-write and maskless modules for domestic packaging ecosystems. These entrants are relevant for regional supply security and tailored application engineering.
Recent Industry Signals — What to Watch in 2026
- Nikon’s opening of orders for the DSP-100 (mid-2025) signals commercial availability of SLM-based systems at 1.0 µm L/S for large substrates — accelerating adoption curves for the highest-resolution packaging use-cases.
- EVG’s public demonstrations of LITHOSCALE XT (SEMICON 2025 and Korea 2026) highlight throughput leaps — critical for segmenting where maskless can genuinely replace conventional photomask workflows at scale.
- Heidelberg’s application briefings emphasize die-shift and warpage compensation techniques tailored to AI/HPC packaging, underscoring the industry’s focus on process stability for heterogeneously integrated stacks.
Strategic Implications for 2026 Decision-Making
For executives planning budgets, partnerships, and product roadmaps in 2026, three strategic implications emerge:
- Prioritize platform flexibility over single-metric superiority. Systems that combine high-resolution optics, real-time die-shift correction, and software-driven workflow orchestration reduce integration risk and accelerate time-to-volume.
- Align procurement with ecosystem access. Suppliers that provide robust spare parts, local service, and software update pathways often produce lower total cost of ownership than lower-priced entrants lacking support footprints.
- Mitigate geopolitical and supplier concentration risks. The market’s CR3 and CR5 concentration metrics suggest a need for dual-sourcing strategies, technology partnerships, and contingency planning — particularly for firms deploying advanced packaging lines in geopolitically sensitive regions.
How PW Consulting’s Report Helps Executives Act
Our study translates the macro forecast and vendor intelligence into executable choices: which systems to pilot by use-case, how to quantify CapEx and OpEx trade-offs for 2026 budgets, and how to structure supplier agreements that allow scaling without lock-in. The report’s scenario toolkits allow procurement and strategy teams to stress-test capital plans under different adoption and supply-chain shock scenarios.
For investors, the report provides forward-looking indicators of supplier and segment profitability, early signals for consolidation, and the technology milestones that de-risk commercial ramp-up.
Next Steps
This briefing intentionally presents a strategic overview. The full PW Consulting report contains the granular models, supplier scorecards, and deployment playbooks required to operationalize a 2026 strategy. To access the complete intelligence — including the full segment and regional decomposition, modeled adoption curves for specific packaging applications, and ready-to-use procurement templates — please consult the PW Consulting report landing page.
PW Consulting stands ready to provide tailored briefings, build custom vendor selection matrices, or run workshop sessions that translate these insights into immediate 2026 action plans for your organization.
For detailed analysis of this topic, please visit the official page: Maskless Lithography System For Semiconductor Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com