

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Industrial Centrifuge Market Set to Grow at a 5.12% CAGR Through 2026–2032

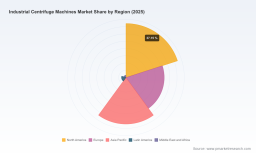
Industrial Centrifuge Machines Market — Strategic Implications for 2026: PW Consulting Intelligence Brief
PW Consulting’s new Industrial Centrifuge Machines Market report (base year 2025) synthesizes five years of historical performance and an actionable forward view across a 2026–2032 forecast window. The market finished 2025 at an estimated USD 9.53 Billion and is projected to expand at a compound annual growth rate (CAGR) of 5.12% through 2032, reaching a projected market size north of USD 13 Billion by the end of our forecast horizon. This briefing outlines why that macro trajectory matters to senior executives, supply-chain leads, investors and technology strategists planning capital and product decisions in 2026 — and how our full report turns strategic insight into executable plays.
Industrial Centrifuge Machines Market
Why this report matters for 2026 decision-makers
- CapEx prioritization under uncertainty: With steady mid-single-digit growth expected, capital planners must distinguish capacity investments that secure market share from those likely to be stranded by near-term disruption (materials, tariffs, or demand volatility).
- Supplier and procurement resilience: Rising raw-material stress and trade-policy friction are forcing procurement redesigns. The right sourcing and inventory strategies can protect margins without undermining service capability.
- Product and service monetization: Aftermarket services, digital retrofits and consumables represent high-margin, lower-capex growth pockets that can be scaled faster than greenfield equipment projects.
- M&A and partnership timing: Fragmentation metrics in the market point to targeted consolidation opportunities — both for platform players seeking new tech (sensors, controls) and for scale buyers hunting regional aftermarket access.
- Regulatory and ESG alignment: Environmental regulation and water-stewardship targets are reshaping demand profiles for separation technologies across municipal, industrial and bioprocess segments.
What the full report delivers — practical and executable
We designed the report as a decision-support toolkit rather than a descriptive market narrative. Key deliverables include:
Industrial Centrifuge Machines Market
- Validated market sizing and a scenario-based forecast suite (base, upside, downside) with sensitivity levers for demand shocks, raw-material inflation and accelerated product substitution.
- Procurement playbook and total cost of ownership (TCO) models that quantify lifecycle economics by equipment family, duty cycle and service profile.
- Supplier performance benchmarking and a pragmatic “vendor-fit” matrix intended to accelerate shortlisting in RFP cycles.
- Technology adoption roadmap highlighting where digital sensors, predictive maintenance and modular designs unlock new revenue or lower operating cost.
- Deal-ready M&A and partnership frameworks, including value-creation checklists, integration risk maps and illustrative synergy pools.
- Regional policy overlays and tariff-impact simulations that translate border measures and raw-material shocks into project-level cost delta estimates.
- Case studies and rapid-deployment pilots showcasing retrofit economics and aftermarket growth conversion methodologies.
Market dynamics to watch in 2026
Several structural and tactical dynamics will shape investment outcomes this year. Companies that proactively address these will have the best chance of converting steady market growth into lasting competitive advantage.
Industrial Centrifuge Machines Market
- Demand composition shift: Growth continues to be driven by a mix of traditional industrial end markets and accelerating demand from high-growth bio-process segments (fermentation, biopharma, alternative proteins). This creates divergent technical requirements — from heavy-duty solids handling to ultra-hygienic, high-speed separators.
- Digital and sensor-driven differentiation: Strategic acquisitions and product launches point to a consolidation of hardware and software capabilities. Smart sensing and condition-based service are no longer optional for OEMs seeking premium aftermarket revenue.
- Raw-material and input-cost pressure: Component costs are under stress — for example, hot-rolled coil steel prices remained firm in early 2026 — and specialty alloys face supply volatility. These dynamics increase the importance of design-for-cost and alternate-material strategies.
- Trade policy and localization: Elevated tariff regimes remain an active margin risk for import-reliant manufacturers. Localization of critical subassemblies and regional service hubs are becoming essential defensive plays.
- Market concentration and consolidation potential: Competitive concentration metrics indicate that leading groups account for a meaningful share of market value, but material scope remains for targeted consolidation — particularly around software and aftermarket capabilities.
Competitive landscape — players, plays and implications
The market is populated by global platform players, niche specialists and strong regional OEMs. The strategic posture of these firms provides a roadmap of likely competitive encounters in 2026:
- Alfa Laval AB (Lund, Sweden): Deep product breadth across decanters and disc-stack separators and aggressive new-product activity (including recent high-speed separators optimized for fermentation and biopharma). Their roadmap signals intent to win in alternative-protein and high-density fermentation workflows.
- GEA Group AG (Düsseldorf, Germany): A traditional food- and process-focused player now expanding digital and water-treatment capability through strategic acquisitions — an example being recent moves to integrate smart-sensor and decanter systems.
- ANDRITZ AG (Graz, Austria): Strong in heavy-industrial solids separation with an emphasis on mining and chemicals — a natural counterpoint to platform OEMs focused on hygienic processes.
- Flottweg SE (Vilsbiburg, Germany): A performance-centric decanter specialist enhancing application development capability through new process-center investments, signaling a commitment to close collaboration with end-users on process optimization.
- Regional and niche specialists: Long-standing manufacturers in North America, Japan, Italy and Turkey remain influential in specific verticals (pharma, sugar, olive oil, etc.). Their domain expertise and installed-base relationships create durable competitive moats for aftermarket and retrofit services.
For buyers and investors, the competitive takeaway is clear: market winners in 2026 will blend product reliability with digital-enabled, service-first business models. Hardware alone will not secure premium returns.
Strategic plays we recommend for 2026
- OEMs — move faster to servitization: Convert installed base into predictable revenue via condition-based maintenance contracts and consumable programs. Prioritize retrofit kits that reduce field-service costs and extend lifecycle revenues.
- End-users — adopt a portfolio approach to procurement: Combine long-lead capital buys with a flexible supplier roster for short-cycle needs. Use TCO models to compare CAPEX-light digital retrofits against heavy equipment replacement.
- Procurement teams — re-engineer supplier risk: Apply scenario stress tests for raw-material price shocks and tariff toggles; build shortlists that include regional manufacturers to hedge border exposure.
- Investors and M&A sponsors — target capability gaps: Acquire sensor/software providers and regional aftermarket platforms to capture higher-margin, recurring revenue streams that decouple growth from cyclical equipment demand.
- R&D and product teams — prioritize modularity and alloy alternatives: Design for lower-cost manufacturing without sacrificing corrosion resistance; invest in modular builds that can be localized.
How to use PW Consulting’s report in practice
The report is intentionally structured to be directly operational: decision-makers should extract the specific modules they need rather than read it end-to-end. Typical engagement flows we support include:
- Board-level CapEx decision pack: A one-page investment thesis, risk-adjusted NPV scenarios and an implementation timeline aligned to procurement cycles.
- Procurement & sourcing sprint: A 90-day playbook with vendor shortlists, negotiation levers and a parts-localization roadmap to mitigate tariff and steel-price risk.
- M&A diligence module: Rapid vendor diligence templates, synergy calculators and integration-risk heatmaps focused on software, aftermarket and regional service assets.
Next steps
PW Consulting’s Industrial Centrifuge Machines Market report is built for executives who need to translate market momentum into defensible, measurable action in 2026. The briefing above highlights the directional insights; the full report contains the granular models, supplier scorecards and scenario outputs required to act decisively. For access to the complete dataset, vendor shortlists, and our customizable TCO and scenario models, please visit the PW Consulting report page or contact our Industrial Equipment practice for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Industrial Centrifuge Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com