

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
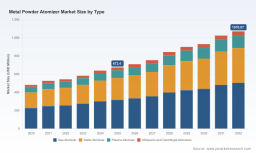
PW Consulting Forecasts Metal Powder Atomizer Market to Grow at 6.84% CAGR, Topping USD 1,070.07 Million by 2032

PW Consulting Releases Strategic Brief: Metal Powder Atomizer Market — A 2026 Decision Playbook
PW Consulting today publishes an executive briefing derived from our comprehensive Metal Powder Atomizer Market report (base year 2025, forecast 2026–2032). The briefing crystallizes the research team’s highest‑value, decision‑centric insights for corporate leaders, investors, and operations executives who must take position in 2026. Our objective is to deliver an immediately actionable perspective that demonstrates methodological rigor while intentionally withholding detailed subsegment figures—so readers are guided to the full report for complete commercial intelligence.
Metal Powder Atomizer Market
Macro snapshot that shapes 2026 strategies
The market for metal powder atomizers has shown resilient expansion through the early 2020s. Our modeling (base year 2025) places the global atomizer market at approximately USD 673.4 Million in 2025, progressing at a compound annual growth rate of 6.84% over the forecast horizon. Under our central scenario, the market reaches roughly USD 1,070 Million by 2032. These headline metrics capture steady demand growth driven by additive manufacturing scale‑up, industrialization of specialty powders, and localized production strategies that seek both supply assurance and cost control.
Metal Powder Atomizer Market
Why 2026 is an inflection year
- Operational scale decisions: Several powder producers have announced capacity expansions and new atomizer deployments in 2024–2026, signaling that 2026 will be the year capacity additions materially affect regional availability and logistics flows.
- Supply‑chain integration: Partnerships and process innovations that shorten the path from atomizer to AM printer (including inert‑storage and direct‑fill approaches) are moving from pilot to commercialization, creating new operational models for powder handling and contamination control.
- Cost‑and‑compliance pressure: Energy, inert gas consumption, regulatory safety requirements, and water recycling are becoming decision levers that materially shift operating economics and capital allocation priorities.
High‑value insights for 2026 decision‑makers
- Invest capital where controllable OPEX meets differentiation. Our unit‑economics overlays show that inert gas consumption and melt yields dominate running costs for gas‑based atomizers, while ultra‑high‑pressure water management and recycling systems determine cost parity for water‑atomization routes. Investment in recirculation and closed‑loop systems lowers unit cost and improves ESG performance—making capital spend on utilities and recycling systems high‑priority in 2026.
- Modular, scalable atomizer platforms win in uncertain demand environments. Vendors offering a continuum from research‑scale to medium‑batch production (with vacuum/inert options) enable customers to shift volumes across the product lifecycle without duplicative capex.
- Regulatory and safety design is a competitive moat. ATEX‑rated designs and robust vacuum/inert gas envelope control are not optional for reactive metals. Firms that standardize compliance into equipment design accelerate time‑to‑market and reduce customer integration friction.
- Vertical integration (atomizer + downstream handling) reduces contamination risk and total cost of ownership. Recent supply‑chain experiments that couple atomization with inert transfer, sieving, and packaging demonstrate measurable reductions in both scrap and QA overheads.
- Specialty feedstock and alloy flexibility matter more than ever. Demand for niche superalloys, reactive metals, and low‑oxygen powders is increasing; atomizers that can handle a broad range of chemistries with repeatable control command premium pricing and customer loyalty.
Competitive landscape — who to watch and why
The market remains moderately consolidated: the top three suppliers account for a meaningful share of installed base and capability (CR3 ≈ 34.2%), and the top five suppliers increase that share materially (CR5 ≈ 48.65%). But the landscape is nuanced—technology specialization, service model, and integration capability differentiate leaders from challengers.
Metal Powder Atomizer Market
- ALD Vacuum Technologies GmbH (Germany, https://www.ald-vt.com) — Market leadership in vacuum induction melting inert gas atomization (VIGA) gives ALD a strong position for high‑purity, spherical powders used in mission‑critical additive manufacturing and powder metallurgy applications. Their strength is process control and high charge‑weight systems that minimize gas entrainment and oxygen pickup.
- Retech Systems LLC (USA, https://www.retechsystemsllc.com) — A broad equipment portfolio (plasma, ceramic induction, TiGA, REGA, centrifugal) positions Retech as a provider to customers handling reactive and refractory chemistries. Their ability to tailor process technology to metal system complexity is a key differentiator for aerospace and specialty alloy producers.
- Arcast Inc. (Maine, USA, https://arcastinc.com) — Known for bespoke inert gas atomizers and flexible feedstock handling, Arcast is winning proof‑of‑concept and medium‑scale production contracts, particularly where customers require close collaboration on alloy development and application‑specific powder properties.
- BluePower Casting Systems GmbH (Germany, https://bluepower-casting.com) — Offers multi‑technology lineups (gas, water, ultrasonic) for small to medium batches. Their portfolio strategy appeals to labs, contract manufacturers, and recyclers that need multiple atomization modalities under a single supplier relationship.
- TOPCAST S.r.l. (Italy, https://www.topcast.it) — Focuses on closed‑coupled gas and water atomizers for industrial powder production. Their engineering emphasis on production robustness and powder morphology control makes them a preferred partner where consistency is a priority.
- Other notable players — A cluster of specialized equipment vendors and systems integrators across Europe, North America, and Asia (including AMAZEMET, SuperbMelt, Atomising Systems Ltd, Phoenix Scientific Industries Ltd, SMS group, Hasung, Taeantech, and CDOCAST) collectively fill gaps in lab‑scale, precious metal, and localized production markets. Each brings niche strengths—ultrasonic lab systems, ultra‑high‑pressure water atomizers, or integrated VIGA plants—that support differentiated go‑to‑market plays.
Our full report contains supplier scorecards, technology heatmaps, and CAPEX/OPEX models that show where each vendor’s installed base best fits customer use cases. These diagnostics are deliberately excluded from this briefing to preserve the tactical value of the primary research dataset.
Recent market signals and what they imply
- Direct‑to‑printer powders and inert packaging: Strategic partnerships announced in 2025 demonstrate industry movement toward closed‑loop logistics (minimizing contamination and handling risk). Operators should prioritize partnerships and equipment that support inert transfer and direct filling to reduce downstream qualification cycles.
- Capacity scale‑up in critical alloys: Several producers commissioned additional EIGA and gas atomizers in 2024–2025, specifically for titanium and nickel‑based alloys. Expect 2026 to be a year of balancing inventory build‑up with demand realization—buyers should incorporate flexibility clauses and off‑take options into procurement contracts.
- Localized verticalization: Equipment acquisitions and in‑house atomization pilots indicate that end‑users in both industrial and defense sectors are pursuing localized powder capabilities to manage strategic supply risk.
- Production scaling with technology variety: High‑volume nickel expansion and commissioning of gas atomizers point to divergent scaling strategies—some operators favor large single‑stream plants, others prefer distributed medium‑scale units that deliver closer customer proximity and faster lead times.
Strategic recommendations for 2026
- Manufacturers and OEMs: Prioritize investments that reduce unit cost and contamination risk—gas recirculation, water‑recycling packages, and integrated inert transfer systems should be evaluated first. Design equipment procurement to enable alloy flexibility and regulatory compliance by default.
- Investors and PE: Look for platform plays that combine equipment OEMs with downstream handling and packaging services. Target companies with clear service expansions, recurring revenue models (spares, service contracts), and customer lock‑in through process qualification support.
- End‑users (aerospace, medical, high‑end industrial): Insist on full process traceability and supplier scorecards during RFPs. Consider co‑investing in local atomization capacity where strategic alloy access is critical to continuity of supply.
- Policy and procurement teams: Update procurement specifications to require ATEX‑compliant hardware where reactive metals are handled; demand lifecycle environmental metrics for water and gas use; and price services with full TCO, not equipment price alone.
What the full PW Consulting report delivers (practical contents)
The complete report is built for execution. It includes:
- Bottom‑up market sizing with scenario forecasts to 2032 (base year 2025) and sensitivity to feedstock, energy, and regulatory variables.
- Supply‑chain mapping and logistics pathways for regional and localized production models.
- Vendor heatmaps and objective scorecards across technology capability, scale, service footprint, and compliance readiness.
- Unit economics and capex/OPEX models for gas, water, plasma, ultrasonic, and centrifugal atomization routes, including utility consumption drivers and recycling levers.
- Commercial playbooks for procurement, strategic partnerships, and build‑vs‑buy decision trees applicable to 2026 capital planning cycles.
- Risk registers and mitigation options for raw material volatility, regulatory constraints, and technology obsolescence.
We intentionally withhold granular regional and application split figures from this briefing to preserve the tactical advantage embedded in our primary research. Corporates and investors that require the full segmentation, vendor financial benchmarking, and downloadable models should consult the full report and dataset.
Next steps
For executives building 2026 capital budgets, procurement tenders, or M&A pipelines, this briefing identifies the strategic inflection points that matter. PW Consulting is prepared to deliver tailored briefings, scenario workshops, and deep‑dive vendor assessments to accelerate decision cycles. Access to the full report unlocks the complete set of subsegment data, supplier scorecards, and downloadable financial models needed to translate strategy into procurement‑ready actions.
Contact PW Consulting to schedule a briefing or to obtain the full Metal Powder Atomizer Market report and accompanying datasets.
For detailed analysis of this topic, please visit the official page: Metal Powder Atomizer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com