

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Silicone in Electric Vehicles Market Set to Reach USD 16,520.26 Million by 2032, Expanding at a 21.5% CAGR

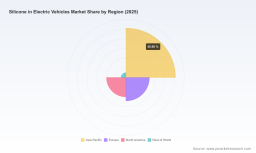
Silicone in Electric Vehicles Market: Strategic Preview for 2026 Decision-Makers
PW Consulting presents a strategic preview of our flagship market study, "Silicone in Electric Vehicles Market" (base year 2025, forecast 2026–2032). This briefing synthesizes the report’s most consequential implications for corporate strategy in 2026—what to act on now, what to monitor closely, and where disciplined investment will matter most. We reveal the high-level market trajectory and competitive posture while intentionally holding back granular splits and line-item forecasts: think of this as the trailer that convinces you to read the full playbook.
Silicone In Electric Vehicles Market
Headline market view: fast growth, structural tailwinds
The silicone materials market serving electric vehicles has entered a high-velocity growth phase. Our analysis values the market at approximately USD 4,226.5 Million in 2025 and projects it to expand to roughly USD 16,520.3 Million by 2032, representing a compound annual growth rate (CAGR) of 21.5% over the forecast window. That trajectory reflects the convergence of accelerating EV penetration, tougher battery safety and durability standards, and intensified demand for thermal management and electronic protection materials.
Silicone In Electric Vehicles Market
Why 2026 is a critical inflection year
- Regulatory activation: Recent regulatory moves—most notably regional mandates that elevate flame-retardant and performance standards for battery systems—have converted a future compliance risk into an immediate procurement and product-design consideration for OEMs and tier-1 suppliers.
- Component-level scaling: EV architecture standardization is enabling supply-chain scale for silicone formulations used in encapsulation, thermal interface materials and sealing—creating a rare window where material suppliers can lock in design wins at volume prices.
- Cost and supply volatility: Upstream feedstock and energy-driven price changes are compressing supplier margins and prompting manufacturers to rethink sourcing geographies and backward-integration options.
Practical, actionable intelligence inside the full report
The full PW Consulting report is structured for immediate use by strategy, procurement, and R&D leaders. Key deliverables include:
Silicone In Electric Vehicles Market
- Clear market-sizing and scenario models: base, upside and downside demand pathways for 2026–2032 that isolate the impact of EV unit growth, architecture mix and regulatory adoption rates.
- Supplier economics and margin maps: a cost-build model that quantifies the sensitivity of silicone product lines to changes in polysiloxane feedstock and energy prices, enabling stress-testing of supplier proposals.
- Technology readouts and validation criteria: engineering checklists and performance benchmarks for common EV silicone use-cases—battery potting, thermal gap fillers, EMI shielding, seals and adhesives—aligned to automotive-grade validation timelines.
- Commercial playbooks: tailored GTM approaches for material suppliers, formulators and converters—spanning direct OEM engagement, tier-1 partnerships, and region-specific distribution strategies.
- M&A and partnership screening: a prioritised list of capability gaps and target archetypes, supported by valuation heuristics calibrated to our revenue and margin forecasts.
These modules are designed to be operational—models and templates that your strategy and business development teams can plug into board-level planning processes for 2026.
Competitive landscape: concentrated, but with differentiation opportunities
The supplier landscape is meaningfully concentrated. Our market concentration assessment indicates that the largest incumbents hold a substantial portion of the market—creating both entry barriers and opportunities for niche differentiation. Leading global players are increasingly positioning silicone portfolios not just as commodities, but as integrated systems for battery safety, thermal management and power-electronics reliability.
- Dow (Midland, Michigan, USA) — A broad-based supplier with deep mobility relationships; recent product demonstrations at major industry shows highlight a push to embed advanced silicone encapsulants into next-generation battery architectures.
- Wacker Chemie (Munich, Germany) — Emphasising silicone gels and elastomers tailored for power-electronics insulation, with recent launches that target the specific dielectric and thermal properties required by inverter and module designers.
- Momentive Performance Materials (Waterford, New York, USA) — Focused on thermal interface materials and protective coatings; their activities at major auto exhibitions signal a premium, application-engineering-led GTM approach.
- Shin‑Etsu Chemical (Tokyo, Japan) — A profile rooted in high-volume rubber and fluid technologies used for seals, lubricants and gaskets in traction motors and battery systems.
- Elkem Silicones (Oslo, Norway) — Positioning around high-performance encapsulation, EMI attenuation and structural adhesives aimed at OEM integration.
- KCC Corporation / Kumho Chemical (Seoul, South Korea) — Concentrating on thermally conductive pads and encapsulants designed to meet EV safety and heat-dissipation specifications.
Recent corporate activity reinforces these strategic threads: product launches and trade-show reveals throughout 2025 show incumbents racing to pre-empt OEM specifications, and to secure qualification queues that will convert to multi-year supply contracts. This has implications for procurement timing and R&D partnership strategies in 2026.
Key market dynamics and near-term risks
- Demand driver: EV sales momentum remains the primary growth engine. Volume adoption of electrified powertrains continues to lift demand for silicone systems used in thermal management and power electronics protection.
- Raw material pressure: Silicone rubber and polysiloxane feedstock pricing experienced upward pressure in 2025, driven by a mix of demand surge from batteries and energy-driven costs in silicon metal production—creating a margin squeeze for formulators unless offset by productivity gains or index-linked pricing.
- Regulatory impact: Recent regulations requiring enhanced battery safety features have accelerated adoption of flame-retardant silicone materials, creating a compliance-driven increment to demand that is difficult for late entrants to capture quickly.
- Supply-side flexibility: Energy and feedstock volatility creates both near-term supply risk and strategic incentive for vertical integration, geographic diversification and long-term offtake agreements.
Strategic imperatives for 2026
For executive teams preparing 2026 budgets and roadmaps, our recommendation is threefold:
- Lock design wins now: Prioritise qualification cycles with OEMs and tier-1s in 1H–2H 2026. Incumbent suppliers will convert design qualifications into long-tail revenue; late movers face significantly higher commercial friction.
- Hedge material cost exposure: Implement a two-layer approach—(1) tactical price indexation and selective long-term contracts for feedstock; (2) strategic initiatives such as co-development or capacity partnerships with silicon metal and polysiloxane producers to manage margin volatility.
- Differentiate through systems engineering: Move beyond single-material sales to bundled solutions—thermal + dielectric + sealing—that align with OEM testing and integration workflows. This dramatically improves win rates and pricing stability.
How PW Consulting’s report supports your 2026 playbook
This PW Consulting study is built to be immediately useful in board-level decisions and commercial planning. The report includes downloadable models, supplier scorecards and a validation checklist that procurement, R&D and BD teams can apply directly in supplier evaluations and M&A screening. Our scenario dashboards allow executives to stress-test investment cases across regulatory, price and volume shocks—enabling clear go/no-go thresholds for 2026.
Next steps
This preview is intentionally selective: we have highlighted the structural thesis, competitive dynamics and the practical actions that matter in 2026 while reserving the full set of granular segmentation and regional breakouts for the complete report. To access the full dataset, including our regional and application-level demand models, supplier-level scorecards, and the downloadable decision-support templates, please visit the PW Consulting report page.
For bespoke briefings, enterprise licensing of the models, or a workshop to convert the insights into a 2026 operational plan, PW Consulting’s automotive materials team is available for tailored engagements. Contact our strategy desk to schedule a concise workshop that maps these insights to your organization’s priorities and risk appetite.
Prepared by: PW Consulting — Senior Strategic Advisory & Industry Analysis
For detailed analysis of this topic, please visit the official page: Silicone In Electric Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com