

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Processed Vegetable Market to Grow at 5.15% CAGR, Reaching USD 454.8 Billion by 2032

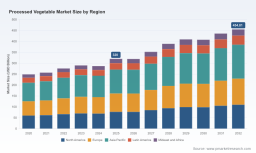
Processed Vegetable Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Report
PW Consulting’s new Processed Vegetable Market report is designed as a practical strategic playbook for businesses planning decisions in 2026. Built on a proprietary dataset that tracks the market from 2020–2025 and models the 2026–2032 outlook, the report synthesizes macro sizing, competitive dynamics, supply-chain stress tests, and regulatory scenario planning. Key headline context: the global processed vegetable market reached approximately USD 320.0 Billion in 2025 and, after near‑term normalization, is projected to expand at a compound annual growth rate (CAGR) of roughly 5.15% through the forecasting horizon—reaching an estimated mid‑hundreds of billions by 2032. These topline metrics anchor the strategic guidance below while detailed, actionable datasets and segment-level intelligence are available in the full report and interactive dashboards.
Processed Vegetable Market
Why 2026 Is a Pivotal Year for Decision‑Makers
Companies face a convergence of cost, regulatory, and market-structure forces that make 2026 a window for decisive action rather than incremental adjustment. On the cost side, official forecasts indicate a meaningful step-up in fresh vegetable prices next year, compounded by an outsized increase in farm‑level prices that will pressure processing margins and procurement strategies. Trade interventions enacted in 2025 — such as retaliatory tariffs affecting preserved vegetables between major North American partners — create immediate sourcing and routing challenges. Simultaneously, the regulatory environment is tightening: state‑level initiatives targeting food additives and a heightened enforcement posture have contributed to more than 300 food recalls in 2025 that involved vegetable products. For executives, the implication is clear: 2026 will reward companies that translate macro foresight into concrete operational changes across procurement, processing, and go‑to‑market approaches.
Processed Vegetable Market
Market Trajectory & Strategic Signals
Our historical analysis shows steady expansion through 2025, with a temporary market normalization at the outset of the forecast period before resumed growth that reflects ongoing consumer demand for convenient, nutrient‑dense options and industry investment in processing technologies. The ~5.15% CAGR embedded in our base forecast captures both structural growth drivers—urbanization, evolving retail and foodservice formats, and increased penetration of value‑added vegetable products—and the moderating effects of input inflation and episodic supply disruptions. Importantly, the market’s long‑term trajectory masks heterogeneity at the product and channel level: winners will be those that align portfolios with resilient demand vectors while hedging exposure to volatile upstream inputs.
Processed Vegetable Market
Competitive Landscape: Consolidation Opportunities in a Fragmented Market
The competitive map is simultaneously mature and fragmented. Market concentration metrics indicate that incumbent branded players do not yet dominate volume to the degree seen in many packaged-food sectors, leaving room for targeted consolidation. Major global players—ranging from multinational beverage‑and‑food conglomerates to specialist frozen‑vegetable processors—continue to steer strategic investments and portfolio reshaping.
- Dole plc remains a vertically integrated supplier with broad capabilities across fresh and processed formats, positioning it well to leverage supply‑chain synergies.
- Fresh Del Monte Produce Inc. materially expanded its processed-vegetable footprint via a March 2026 acquisition of select packaged-vegetable assets from Del Monte Foods, including multiple processing sites and brands—an acquisitive move that signals ongoing consolidation in 2026 and beyond.
- Conagra Brands , Kraft Heinz , and Nestlé continue to play the scale game in retail and foodservice channels, balancing national brand strength with private‑label competition.
- European specialists such as Bonduelle , Ardo Group , and Greenyard emphasize frozen and premium offerings, pairing sustainability claims with capacity investments tailored to regional demand.
- Specialized processors— Seneca Foods , J.R. Simplot —focus on category niches (potatoes, private label, and industrial processing), making them attractive targets for bolt‑on acquisitions by larger players seeking route‑to‑market or SKU diversification.
Recent industry events underscore strategic imperatives. The bankruptcy filing and subsequent asset divestitures in 2025 created acquisition windows; the March 2026 Fresh Del Monte transaction (announced consideration in the low hundreds of millions USD) exemplifies the type of mid‑market consolidation that will shape competitive positioning through 2027. At the same time, market concentration statistics suggest ample runway for further consolidation without triggering prohibitive antitrust scrutiny in most jurisdictions—making 2026 a prime year to evaluate opportunistic M&A.
Operational Hotspots: Procurement, Processing, and Food‑Safety
Our operational analysis identifies five levers that materially affect margins and risk exposure in 2026:
- Secure sourcing and contract design — Given projected fresh price inflation and farm‑level volatility, short‑term spot exposure must be balanced with longer‑dated contracting, indexed pricing mechanisms, and supplier diversification strategies.
- Processing flexibility — Investments in modular processing lines and multi‑format capacity (frozen, canned, dried) enable rapid SKU shifts in response to raw‑material and regulatory pressures.
- Cold‑chain resilience — For frozen‑led portfolios, traceability and refrigeration reliability are direct determinants of waste, recall probability, and customer satisfaction.
- Food‑safety and recall mitigation — With hundreds of recalls reported industry‑wide in 2025, companies should prioritize end‑to‑end traceability, third‑party audits, and incident response playbooks to preserve retail and foodservice contracts.
- Energy and input cost management — Processing is energy‑intensive; energy procurement hedges and efficiency retrofits are quick ROI opportunities in many facilities.
Regulatory and Trade Risk Management
Legislative moves targeting additives and heightened recall visibility have direct product and reputation consequences. Companies must adopt a three‑part compliance posture in 2026: (1) proactive reformulation and transparent labeling to meet emergent state and national standards; (2) active participation in standards‑setting and trade advocacy to influence practical implementation; and (3) legal‑operational alignment to minimize liabilities and safeguard supply agreements. Trade frictions—illustrated by cross‑border tariffs affecting preserved vegetables—require scenario planning that includes nearshoring, alternate routing, and tariff engineering for relevant SKUs.
What PW Consulting’s Report Delivers
Designed for C‑suite and business‑unit leaders, the report is a decision‑centred toolkit rather than an academic compendium. Highlights include:
- Market sizing and topline trajectory (2020–2025 historical and 2026–2032 forecast), with interactive dashboards for stress‑testing macro scenarios;
- Segment playbooks that map product‑format economics, channel profitability, and margin drivers (available in the full dataset to preserve tactical advantage for subscribers);
- Supply‑chain heatmaps and supplier scorecards that rank upstream risks by country, crop cycle, and processing dependence;
- M&A playbook including target archetypes, valuation benchmarks, and integration checklists tailored to the processed‑vegetable space;
- Regulatory tracker and recall risk matrix, including policy trendlines and compliance milestones for 2026;
- Innovation radar highlighting priority product concepts (clean‑label, fortified blends, and convenience formats) and manufacturing enablers (aseptic processing, high‑pressure preservation, and drying tech).
Five Tactical Priorities for 2026
- Lock down the supply base: renegotiate contracts with indexed protections, partner on shared storage solutions, and explore equity stakes in key farming hubs to dampen upstream volatility.
- Pursue targeted M&A: prioritize assets that add distributed processing capacity, retail shelf presence, or high‑margin specialty SKUs—particularly where bankruptcies or divestitures have created motivated sellers.
- Invest in safety and traceability: reduce recall exposure by implementing end‑to‑end traceability systems and standardized incident escalation protocols; this is a differentiator in buyer negotiations.
- Accelerate clean‑label reformulation: preempt additive restrictions with alternative preservation and processing technologies to maintain shelf life without compromising claims.
- Adopt flexible channel strategies: balance retail, foodservice, and industrial processing exposure with tailored SKUs and packaging investments to capture shifting demand patterns.
How to Use This Report in Boardroom Decisions
Executives should treat the report as a scenario engine for capital allocation, commercial strategy, and regulatory readiness. Use the dashboards to quantify balance‑sheet exposure under input‑price shocks, test the economics of acquiring mid‑market processing assets, and prioritize CAPEX that delivers resilience (e.g., cold storage and energy efficiency) with clear payback windows. For M&A committees, the report’s integration checklists and valuation comparables offer a short list of pragmatic metrics for triage and due diligence.
Call to Action
PW Consulting’s Processed Vegetable Market report delivers the actionable intelligence teams need to convert 2026 uncertainty into competitive advantage. The public summary above outlines strategic direction and operational priorities; the full report contains the granular datasets, supplier matrices, and scenario models that support executable plans. To access the complete report, interactive dashboards, and to request a tailored briefing for your organization, visit our report page or contact our processed‑foods practice lead for a confidential consultation.
For detailed analysis of this topic, please visit the official page: Processed Vegetable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com