

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Industrial‑Grade Three‑Phase Micro Inverter Market Poised for Rapid Growth at 18.52% CAGR Through 2032

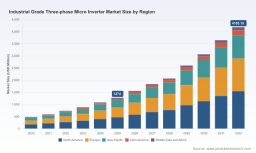
Industrial‑Grade Three‑Phase Micro Inverter Market — Strategic Outlook for 2026 Decision‑Making
Executive summary
PW Consulting’s latest market study on Industrial‑Grade Three‑Phase Micro Inverters delivers a focused, decision‑ready view for organizations shaping commercial and industrial PV strategies in 2026. Anchored on a 2025 base year and a detailed historical analysis covering 2020–2025, the report models the market through a 2026–2032 forecast horizon. The market demonstrates robust expansion — from roughly USD 485 million in 2020 to about USD 1,274 million in 2025 — and, under our central scenario (CAGR 18.52%), is projected to exceed USD 4.1 billion by 2032 (all values in USD Million). These headline metrics quantify a rapid maturation curve that will materially affect procurement, product roadmaps, and grid‑services strategies this year.
Industrial Grade Three Phase Micro Inverter Market
Why this matters for 2026 corporate planning
- Timing the technology adoption curve: With GaN‑enabled platforms arriving in commercial shipments and modular high‑power designs proliferating, decisions made in 2026 will determine whether a buyer captures near‑term efficiency and balance‑of‑system benefits or becomes locked into legacy lower‑efficiency platforms.
- Supplier selection under regulatory pressure: Domestic content and Foreign Entity of Concern (FEOC) rules in key markets are already influencing eligible project bids; supply chain and manufacturing footprint are now table stakes for eligibility in many commercial tenders.
- Revenue and margin implications: The projected market expansion implies new margin pools around value‑added services (grid support, monitoring, firmware lifecycle management) that can reshape traditional OEM/distributor economics.
- Risk and resilience: Semiconductor and GaN supply dynamics, plus evolving grid‑interconnection standards (e.g., IEEE 1547 / UL 1741‑SB), create a set of operational and compliance risks that require proactive mitigation in vendor contracts and implementation plans.
Report deliverables — practical, tactical, and ready to act
PW Consulting’s report is built as a playbook for C‑suite and procurement teams rather than a purely descriptive market brief. Highlights include:
Industrial Grade Three Phase Micro Inverter Market
- Robust market sizing and segmentation (methodology, assumptions, and sensitivity runs) with a central forecast on the 18.52% CAGR path and alternative scenarios to test downside and upside outcomes.
- Vendor scorecards and competitive positioning frameworks that assess technology maturity, manufacturing footprint, product efficiency, module compatibility, and service offerings — designed to support RFP shortlists and supplier negotiation.
- Technical benchmarking: head‑to‑head architectural comparisons (including GaN advantages, peak efficiencies, module‑level optimization capabilities, and transformerless 480‑VAC solutions), with pragmatic notes on installation, thermal design, and lifecycle maintenance.
- Regulatory & compliance playbook: how to interpret and operationalize requirements such as domestic content, FEOC screening, and IEEE 1547/UL 1741‑SB grid support mandates across procurement and field operations.
- Commercial templates: procurement scorecards, risk allocation clauses for semiconductor supply, warranty and firmware update SLAs, and financing models tuned to C&I project cash flows.
- Implementation roadmaps: from piloting module‑level power electronics (MLPE) on rooftops to scaling across multi‑site portfolios, including SOC (security), O&M, and firmware lifecycle plans.
Competitive landscape — who matters and why
The industrial three‑phase microinverter market is concentrated and evolving quickly. The top tier of vendors controls a material share of the market, creating a landscape where strategic partnerships and manufacturing footprints are as important as device performance. PW Consulting’s analysis—based on product roadmaps, public disclosures, and shipment data—highlights several archetypes:
Industrial Grade Three Phase Micro Inverter Market
- High‑performance innovator with domestic manufacturing: vendors who combine GaN‑based platforms with local production are positioned to win projects constrained by domestic content and FEOC rules. These vendors offer high peak efficiencies and simplified balance‑of‑system designs attractive to the C&I segment.
- Scale‑oriented multi‑module specialists: suppliers emphasizing multi‑module quad and 8‑in‑1 designs deliver lower per‑watt installation costs for large rooftop arrays and are favored in volume‑driven procurements.
- Integrated portfolio players: companies that embed three‑phase microinverters within broader inverter and storage portfolios provide one‑stop solutions that reduce integration risk for EPCs and asset owners.
- Regional challengers: a set of emerging vendors provide competitive, cost‑focused options—particularly in Asia and secondary markets—with differentiation around reliability and localized service networks.
Strategic implications: Given market concentration (the top three and top five vendors account for a substantial share of demand), buyers should balance the benefits of established vendors (warranty certainty, proven firmware update chains) against the potential cost and agility advantages of regional challengers. Supply security, certification track record, and long‑term firmware/support commitments are decisive selection criteria in 2026.
Technology and regulatory dynamics shaping 2026 choices
- GaN as an inflection point: GaN power semiconductors enable smaller, higher‑efficiency microinverters with improved thermal characteristics and simplified architectures. Organizations must evaluate the total cost of ownership impact of GaN‑based devices versus incumbent silicon designs.
- Grid‑integration standards: compliance with IEEE 1547 / UL 1741‑SB (including remote automatic updates and advanced grid support functions) is increasingly non‑negotiable for commercial and industrial interconnections. Firmware lifecycle management and cybersecurity for OTA updates are now procurement checkboxes.
- Procurement and eligibility constraints: domestic content and FEOC screening are directly influencing device acceptance in major markets. Buyers should map supplier manufacturing footprints against regulatory eligibility requirements early in project origination.
Supply chain and raw‑material realities
Semiconductor availability and GaN device supply chains are the near‑term choke points for many manufacturers. Our supplier due‑diligence work shows that lead times, qualifying capacity, and strategic sourcing agreements for GaN epitaxy and power packaging will determine which vendors can scale reliably in 2026. Procurement teams should incorporate multi‑tier supplier reviews, long‑lead procurement clauses, and manufacturing‑related KPIs into vendor contracts.
Top recommendations for executives acting in 2026
- Prioritize vendor qualification on three axes: technology maturity (including GaN readiness), manufacturing footprint (domestic vs. offshore), and firmware/cybersecurity lifecycle commitments.
- Adopt a two‑track procurement approach: pilot GaN‑enabled systems on priority rooftops while hedging volume purchases with established silicon platforms to mitigate supply risk.
- Embed regulatory eligibility checks into project origination to avoid last‑mile disqualification under domestic content or FEOC constraints.
- Design contracts to capture value from grid services (voltage support, reactive power) and to allocate firmware update risk and liabilities clearly between OEMs and asset owners.
- Invest in systems integration capabilities — EMS/SCADA and MLPE interoperability — to capitalize on module‑level optimization for yield uplift and predictive O&M.
- Structure R&D and supplier partnerships around modular architectures that allow swapping power electronics generations without redoing racking or wiring infrastructure.
How PW Consulting’s market intelligence accelerates your 2026 strategy
This report functions as a near‑term playbook and a long‑term strategic lens. It blends quantitative market sizing (base year 2025, historical 2020–2025, forecast 2026–2032, currency USD Million) with qualitative vendor intelligence and procurement‑grade tools. We present scenario analyses around the central 18.52% CAGR projection, sensitivity to GaN adoption rates, and regulatory shock scenarios to help executives stress‑test capital allocation and sourcing strategies for the year ahead.
Next steps — access the full report
The commentary above intentionally highlights strategic levers and market dynamics while withholding the granular regional and application split data that procurement teams require for transaction‑level decisions. To unlock the full dataset, proprietary vendor matrices, regional demand build‑outs, and downloadable procurement templates, access the complete PW Consulting Industrial‑Grade Three‑Phase Micro Inverter Market report. The full deliverable contains the segment‑level figures, comprehensive vendor scorecards, and the practical tools necessary to operationalize the 2026 actions outlined here.
For detailed analysis of this topic, please visit the official page: Industrial Grade Three Phase Micro Inverter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com