

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Industrial Smart Helmet Market Poised for Rapid Expansion at a 14.25% CAGR, New Report Reveals

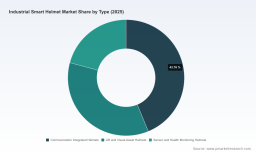
Industrial Smart Helmet Market 2026: Strategic Imperatives from PW Consulting’s Latest Market Research
PW Consulting’s newest market research brief on the Industrial Smart Helmet market (base year 2025; historical period 2020–2025; forecast 2026–2032) synthesizes technical, commercial and regulatory intelligence into an action-oriented playbook for executives making 2026 procurement, product, and M&A decisions. Our analysis finds the market accelerating from an estimated USD 810 million in 2025 to just over USD 2.05 billion by 2032, representing a compound annual growth rate of 14.25%. This growth creates both opportunity and complexity — and our report is positioned to help leadership teams translate macro momentum into defensible, near-term strategic moves without exposing the granular sub-segment modelling that underpins our forecasts.
Industrial Smart Helmet Market Research
Why PW Consulting’s 2026 Perspective Matters
-
Timing: 2026 is a convergence year — technology vendors move from prototype and pilot phases into wider commercial roll-outs, standards and site-level certifications are maturing, and industrial buyers are demanding demonstrable ROI for connected-worker investments. Our brief maps the inflection points buyers must navigate this year.
Industrial Smart Helmet Market Research -
Decision Focus: The report prioritizes the three decision horizons executives face: (1) immediate procurement choices to complete 2026 rollouts, (2) product and integration investments to be committed in 2026 for 2027–2028 scale, and (3) capability-based M&A or partnership plays to secure differentiated market positions through 2032.
Industrial Smart Helmet Market Research -
Actionable Intelligence: We combine market sizing, vendor scoring, use-case ROI templates, and a regulatory checklist into a single reference designed for procurement, EHS, operations and strategy teams — all while preserving the full granular data for readers who request the complete report.
Market Dynamics: Drivers, Constraints and Structural Signals
-
Adoption Drivers — Safety, Compliance and Productivity: The primary growth engine remains compliance-driven and operational safety requirements across heavy industries. Buyers increasingly value helmets that go beyond passive head protection to provide real-time hazard alerts, health monitoring, positioning and remote collaboration capabilities.
-
Technology Enablers: Improvements in low-power sensors, industrial wireless (including early 5G implementations), AI edge inference models and ruggedized AR peripherals are rapidly increasing the functional density of helmets. Expect product roadmaps in 2026 to emphasize integrated sensing and edge analytics rather than isolated add-ons.
-
Cost and Supply Constraints: Volatility in raw material costs — notably ABS, polycarbonate and EPS foam which have risen materially since 2021 — is compressing supplier margins and accelerating supplier consolidation. Procurement teams must build material-cost pass-through and hedging logic into multi-year contracts.
-
Regulatory & Certification Landscape: Safety certifications (e.g., ANSI/ISEA Z89.1) and hazardous-location approvals (ATEX, IECEx, CSA) remain gating factors for industrial deployments. OSHA enforcement trends and equivalent international mandates are pushing connected-worker technologies onto the approved list for fall- and impact-prevention programs.
Competitive Landscape — What Winners Look Like in 2026
The market exhibits moderate concentration with top incumbents holding meaningful but not dominant positions. Vendors that will lead the next wave share several attributes: product platforms that combine certified physical protection with modular sensor stacks; proven integration with site RTLS and command platforms; and commercial models that align with safety managers’ buying cycles.
-
Supplier archetypes: The market’s competitive fabric is formed by a mix of specialty helmet manufacturers, industrial-safety incumbents, and technology-focused entrants. Established head-protection brands bring manufacturing scale and certification expertise; technology-first firms contribute AI, connectivity and data services; regional players leverage local cost structures and deployment relationships.
-
Representative players profiled in our report: Examples include helmet innovators offering integrated impact/fall detection and MIPS-based protection; IoT-enabled manufacturers with modular sensor options and solar augmentation; 5G-capable designs targeting low-latency monitoring; and companies focusing on intrinsic safety certifications for explosive atmospheres.
-
Recent strategic moves (selection): Product announcements and launches in late 2024 through 2025 underscore rising competition — new integrated sensor helmets with automated emergency alerting, 5G-capable models aimed at industrial connectivity use-cases, and next-generation helmets incorporating MIPS for enhanced brain protection. These developments illustrate a shift from single-feature differentiation to multi-capability platforms.
What the Report Contains — Practical Modules for 2026 Execution
PW Consulting’s report is structured to be immediately usable by cross-functional teams. Key modules include:
-
Market sizing and scenario modelling: Base and upside scenarios through 2032, with sensitivity testing for material costs, certification timelines and 5G rollout velocity.
-
Use-case ROI calculators: Pre-built templates for construction, oil & gas, mining and manufacturing that quantify reductions in incident-costs, productivity impacts from remote guidance, and lifecycle TCO for connected helmets.
-
Vendor diagnostic and scorecards: Comparative capability matrices, deployment maturity assessments and procurement negotiation playbooks to shorten vendor selection cycles.
-
Integration and deployment playbook: Reference architectures for edge-cloud data flows, RTLS and MES/ERP integrations, and cybersecurity baseline requirements for on-site wearables.
-
Regulatory compliance checklist: Step-by-step validation and certification guidance tailored to hazardous and non-hazardous site types, including testing pathways and documentation templates.
-
Procurement templates and commercial models: Preferred contract structures, SLA language for sensor uptime and emergency response, and recommendations for CapEx vs. As-A-Service approaches.
-
Case studies and pilot blueprints: Real-world deployment blueprints that reduce pilot-to-scale timelines and identify common failure modes in field trials.
Strategic Recommendations for 2026
Executives should prioritize a small set of concrete actions this year to secure advantage as the market scales:
-
Move from proof-of-concept to outcome-based pilots: Require vendors to demonstrate measurable incident reduction or productivity uplift within defined timelines and accept commercial terms that tie payment milestones to outcomes.
-
Insist on certification-first roadmaps: Only engage suppliers that either hold, or have a documented pathway to, necessary safety and hazardous-location certifications for your sites. Certification timelines must be factored into procurement planning.
-
Design integration-first architectures: Treat helmets as nodes within a wider connected-worker ecosystem. Prioritize vendors with open APIs, established RTLS compatibility and secure edge analytics to minimize bespoke integration costs.
-
Securitize the data flow: Ensure helmet telemetry and voice/data links meet enterprise security standards. Include encryption, device identity management and incident response obligations in contracts.
-
Mitigate supply-chain and material risk: Build price-adjustment clauses and multi-sourcing options for helmet shells and sensor modules to protect against raw material inflation and single-vendor dependency.
-
Align procurement cadence with workforce training: Plan for phased rollouts that pair hardware deployments with supervisor and field training to capture behavioral benefits and improve adoption.
-
Consider partnership or tuck-in acquisition for capability gaps: For industrial OEMs or systems integrators seeking rapid entry, acquiring sensor or analytics specialists can be faster and lower-risk than greenfield development.
Implications for Investors and M&A
The market’s projected trajectory (14.25% CAGR through 2032) makes the smart helmet space attractive for strategic and financial investors, but the underlying opportunity is nuanced. Value creation favors firms that can: (1) demonstrate durable commercial traction in heavy industries, (2) own or tightly control certification pathways, and (3) provide recurring analytics or services that extend beyond one-time hardware sales. Our M&A due-diligence templates and valuation sensitivities are designed to expedite robust bids while highlighting integration risks.
How to Use This Report in 2026 Planning
-
Board-level briefing: Use the executive summary to align stakeholders on the timing and scale of investment required to participate meaningfully in the next five years.
-
Procurement RFPs: Leverage our vendor scorecards and contract templates to reduce procurement cycle times and improve comparative evaluation rigor.
-
R&D roadmaps: Map product investments to the capability tiers and certification milestones outlined in the technology roadmap chapter.
-
Investor decks: Integrate the scenario-based market sizing and ROI cases to validate adoption assumptions and capital requirements for scaling pilots.
Next Steps and Access to the Full Intelligence
PW Consulting’s Industrial Smart Helmet Market Research is intentionally structured as a "trailer" in this release: we provide the strategic contours, decision frameworks and headline projections you need to make better 2026 decisions while reserving the detailed sub-segment worksheets, regional deployment models and vendor-level financials for the full report. These granular elements are available to clients and subscribers through PW Consulting’s research portal and advisory services.
For procurement leads, safety directors and corporate strategists preparing budgets and roadmaps for 2026, the report supplies the operational templates and vendor due-diligence tools to move from pilot curiosity to enterprise-grade deployment. Contact PW Consulting to request the full report, tailored briefings, or a workshop that maps our findings directly into your 2026 business case.
For detailed analysis of this topic, please visit the official page: Industrial Smart Helmet Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com