

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 5.28% CAGR for Global Oil & Gas Storage and Transportation Market

Oil and Gas Storage and Transportation Market — Strategic Outlook for 2026
Executive summary
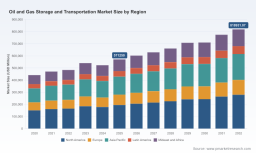
PW Consulting’s latest Oil and Gas Storage and Transportation Market report delivers a practical, decision-grade roadmap for corporate leaders, investors, and public-sector planners preparing for 2026 and beyond. Building on a six‑year historical baseline (2020–2025) and a detailed forecast horizon (2026–2032), the study quantifies a resilient market trajectory — with the global market valued at USD 571,250 Million in the base year 2025 and projected to expand to approximately USD 818,931 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.28% across the forecast period.
Oil And Gas Storage And Transportation Market
Why this matters for 2026 decision‑makers
- Macro uncertainty is colliding with structural change. Elevated global inventories, episodic draws and regional floating storage shifts mean operators must balance capital discipline with operational flexibility.
- Capital allocation decisions made in 2026 — whether to expand tank capacity, invest in pipeline conversions, or accelerate carbon‑transport projects — will determine competitive positioning for the next decade.
- Regulatory trajectories and infrastructure repurposing opportunities (from hydrocarbons to CO2 transport) create distinct, time‑sensitive windows for new revenue streams but require different commercial models and partner ecosystems.
Market trajectory and what the numbers reveal
The report’s top‑line market sizing shows a recovery and re‑acceleration following the recent cyclical volatility. With the total market at USD 571,250 Million in 2025 and a forecast to reach roughly USD 818,931 Million by 2032 (CAGR 5.28%), the near‑term implication for 2026 is clear: the sector is large and growing at a pace that supports both organic infrastructure optimization and selective growth investment. Importantly, market concentration remains modest — the top three players account for less than one‑fifth of the market and the top five for roughly one‑quarter — signaling meaningful scope for regional champions, specialized operators, and new entrants to capture value.
Oil And Gas Storage And Transportation Market
Key dynamics shaping 2026 strategies
- Inventory volatility and strategic reserves: Global observed oil stocks reached multi‑year highs in early 2026, while subsequent inventory draws and government exchanges of strategic barrels have underscored the role of storage as a macro‑stabilization tool. Operators must design capacity and commercial contracts that can pivot between market optimization and crisis‑response roles.
- Energy transition overlap: Existing transport and storage infrastructure is a viable foundation for carbon transport and storage build‑outs. Federal plans targeting tens of millions of tonnes of CO2 transport annually create an adjacent market that infrastructure owners can address with modest retrofits and new service lines.
- Pipeline and offshore project rollouts: New long‑distance pipeline projects coming online around 2026 create altered flow patterns; companies positioned along these corridors will experience changes in throughput economics and must adjust commercial terms accordingly.
- Regulatory pressure on demand: Projections that transportation sector energy use could decline materially by mid‑century under strict emissions standards add a strategic imperative to diversify away from pure volume dependence toward higher‑value services and lower‑carbon offerings.
Strategic plays for 2026 — what winners will do
- Optimize portfolio flexibility: Prioritize assets and contracts that enable fast toggling between spot commercial optimisation and long‑duration reserve or strategic services. Structure a blend of term and indexed contracts and embed optionality clauses tied to inventory or crisis triggers.
- Targeted capex and retrofit pathways: Instead of broad capacity builds, favor selective upgrades that support multiproduct handling (crude, refined products, gas/LNG), digital telemetry, and CO2 compatibility. Use modular expansions and third‑party engineering contracts to control lead times and capital intensity.
- Commercial partnerships and market access: Form alliances with trading houses, national oil companies, and industrial CO2 emitters. Joint ventures can secure feedstock/freight while sharing downside in volatile commodity cycles.
- Digitize operations and commercial analytics: Deploy real‑time utilization dashboards, predictive maintenance, and dynamic tariff engines to squeeze margin from existing assets and reduce unplanned downtime.
- ESG and decarbonization as revenue safeguards: Invest in methane emission controls, low‑carbon fuel handling protocols, and credible disclosure frameworks to preserve access to capital and meet rising shipper and insurer expectations.
Competitive landscape — strategic profiles and implications
The report assesses major global and regional players to highlight where competitive advantages will be sustained or eroded in 2026. Key strategic takeaways include:
Oil And Gas Storage And Transportation Market
- Royal Vopak N.V. — Market leadership in independent tank storage gives Vopak an advantage in terminal optimization and product diversification. Their global terminal footprint makes them a natural partner for traders seeking storage flexibility and for companies testing CO2 and chemical storage use cases.
- Kinder Morgan, Enbridge, TC Energy — These pipeline‑centric operators benefit from integrated throughput economics. Their core strategic choice is whether to monetize tariff upside via capacity markets or pivot parts of their networks to serve new low‑carbon freight (CO2, hydrogen), requiring regulatory engagement and repurposing CapEx.
- Enterprise Products Partners, Energy Transfer, Buckeye — Highly integrated networks along key coastal and inland corridors offer optionality across crude, NGLs and refined products. Their playbook centers on capturing value across the value chain (storage, fractionation, export) and offering bundled logistics solutions.
- Saudi Aramco, ADNOC, CNPC — National champions control strategic storage and export nodes, giving them leverage in global supply stability and strategic reserve policy. International partners and private operators must engage these players through sovereign‑grade JV structures or service contracts.
- Oiltanking, VTTI — Independent terminal operators remain well positioned to serve diversified customers, offering agility on commercial terms and the ability to act as neutral storage hubs in contested or redirecting trade flows.
Recent developments that sharpen 2026 decisions
- Governmental strategic movements — contract awards and emergency exchanges of strategic barrels in 2026 have raised the premium on storage capacity suitable for government use and contingency operations. Companies that can meet governmental standards and acceptance criteria will capture non‑market revenues.
- Large upstream and midstream contract awards — substantial project awards for field development and pipeline expansions (including large gas field projects and NGL fractionation facilities) are driving demand for associated storage and export infrastructure.
- Project pipelines and offshore links — new cross‑border trunklines entering service alter trade lanes and terminal throughput profiles; owners of terminals near these corridors should re‑test their tariffs and connectivity strategies.
What PW Consulting’s report delivers — practical contents
The report is structured for immediate operational use by C‑suite leaders and investment committees. It includes:
- Top‑line market sizing and scenario forecasts (2026–2032) with sensitivity testing across demand, price, and policy levers;
- Commercial playbooks: contract structures, tariff design options, and contingency clauses tailored for storage and pipeline operators;
- Investment prioritization matrices linking asset type, time‑to‑market, and expected return under three macro scenarios;
- Competitive benchmarking of leading operators, including capability maps, strategic options, and likely moves through 2028;
- Regulatory and geopolitical heatmaps identifying high‑risk corridors and policy opportunities for CO2 and low‑carbon fuels transport;
- Operational toolkits: terminal utilization templates, digital maturity assessments, and maintenance commonality guides;
- Proprietary M&A shortlist and valuation ranges (confidential appendices) to accelerate deal screening and diligence.
How to use the intelligence in 2026 — a practical 90‑day plan
- 30 days: Run an asset triage — classify terminals and lines as defend, transform, or divest using the report’s prioritization matrix.
- 60 days: Secure optionality — renegotiate a subset of contracts to include crisis‑use and indexation provisions; pilot digital telemetry improvements on high‑value tanks or pipeline sections.
- 90 days: Launch at least one strategic partnership — either a joint venture with a national player, a service agreement with an independent terminal, or an agreement with an industrial CO2 emitter to pilot transport solutions.
Conclusion and next steps
2026 will be a pivotal year for the oil and gas storage and transportation sector: the market is substantial and growing, but value will accrue to organizations that manage optionality, monetize operational flexibility, and proactively engage with the decarbonization landscape. PW Consulting’s report synthesizes the quantitative outlook, competitive dynamics, and executable playbooks you need to convert uncertainty into competitive advantage.
To access the full study — including our proprietary terminal mapping, scenario models, and confidential M&A shortlist — visit the official report page and secure the comprehensive intelligence that will inform your 2026 capital and commercial decisions.
For detailed analysis of this topic, please visit the official page: Oil And Gas Storage And Transportation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com