

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hazardous Chemical Warehousing & Logistics Market Poised to Reach USD 361.5 Billion by 2032, Advancing at a 6.12% CAGR

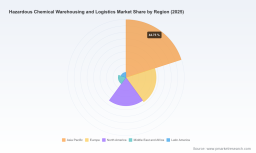
Hazardous Chemical Warehousing and Logistics: A 2026 Strategic Playbook for Risk, Compliance, and Growth
Executive snapshot
PW Consulting’s latest market study on Hazardous Chemical Warehousing and Logistics frames a rapidly maturing sector where regulatory shifts, technology adoption, and sustainability mandates converge to reshape capital allocation and partner strategies in 2026. The global market stood at approximately USD 238.5 billion in our 2025 base year and is forecast to expand to roughly USD 361.5 billion by 2032, reflecting a compound annual growth rate of 6.12% over the 2026–2032 forecast window. These headline dynamics belie a fragmented competitive structure and a value chain moving from commoditized handling toward integrated, compliance-driven solutions—making 2026 a pivotal year for boardroom decisions.
Hazardous Chemical Warehousing And Logistics Market
Why this report matters for 2026 decisions
-
Regulatory inflection points: Multiple international rules implemented or updated as of 2026 (including the most recent editions of air, sea, and road dangerous goods codes and imminent US harmonization proposals) are creating both compliance costs and commercial opportunities. Our report maps the practical implications of these changes on routing, packaging, and storage protocols across modal networks.
Hazardous Chemical Warehousing And Logistics Market -
Capital allocation under uncertainty: With physical infrastructure and specialized storage assets commanding higher capex, executives must choose between organic capacity build, strategic partnerships, or M&A. The report provides scenario-based CAPEX guidance and decision metrics calibrated to different growth and compliance outcomes.
Hazardous Chemical Warehousing And Logistics Market -
Fragmentation and consolidation playbook: Market concentration remains low among top players, a structural reality that favors both regional specialists and global integrators. We unpack the strategic choices for entrants and incumbents—where to compete, when to consolidate, and how to structure alliance economics.
-
Technology and operational resilience: Advances in real-time tracking, digital twins for tank inventory, and safety analytics are no longer optional. Our study quantifies the operational levers that translate technology spend into lower incident rates, faster regulatory reporting, and improved asset utilization.
What’s in the study: practical, transaction-ready content
-
Robust market sizing and forward scenarios – base year 2025 with detailed forecasts through 2032, incorporating macro drivers, modal shifts, and regulatory shock scenarios.
-
Risk and compliance playbooks – step-by-step checklists for meeting updates to international codes and domestic rules, including tailored action items for labelling, training, tank inspection regimes, and emergency response upgrades.
-
Network and capacity analytics – decision frameworks for warehouse location optimization, modal mix rebalancing, and surge capacity management under different demand curves.
-
Capital and operating models – TCO templates that convert storage typologies and handling profiles into multi-year cashflow, depreciation, and working-capital impacts to support CAPEX and lease-versus-buy choices.
-
M&A and partnership playbooks – criteria matrices for target screening, due-diligence checklists tailored for hazardous goods assets, and integration risk maps focused on insurance, environmental liabilities, and regulatory continuity.
-
Commercial tools – partner selection scorecards, RFP templates for hazardous-warehousing services, and contract clauses to allocate liability and ensure compliance continuity under changing regulation.
Competitive landscape: strengths, gaps, and strategic moves
The sector combines global logistics integrators, regional specialists, and chemical-focused service providers. Major international logistics companies provide end-to-end chemical logistics capabilities—specialized hazmat facilities, multimodal options, and compliance tooling—while dedicated chemical logisticians excel in niche services such as intermodal tank container operations and sample fulfillment. The market exhibits low top-tier concentration (CR3 and CR5 metrics indicate significant room for competitive maneuver), which intensifies price and service differentiation pressures.
-
DHL Supply Chain – Known for comprehensive hazmat facility networks and real-time tracking solutions that ease regulatory reporting and incident traceability. A preferred partner for clients prioritizing integrated supply chain visibility.
-
DB Schenker – Strong in European road and rail ADR-compliant operations, with deep experience in tank container and multimodal transfer protocols—particularly relevant for cross-border chemical corridors.
-
Kuehne + Nagel – Offers a sustainability-forward chemical logistics suite, integrating tank storage with broader supply chain sustainability commitments and trade-compliance advisory services.
-
DSV, CEVA, and Rhenus – Competitive in specialized hazardous warehousing and regional distribution networks, focusing on safety protocols and localized regulatory expertise.
-
Bertschi, Hoyer, and other tank-focused specialists – Provide high-value intermodal and bulk-liquid competencies that are critical where tank integrity, heating, or inerting services are required.
-
US-based specialists (C.H. Robinson, Odyssey, Rinchem, Univar Solutions, Brenntag, etc.) – These firms combine freight technology or chemical distribution expertise with hazardous-warehousing services to offer end-to-end value propositions for complex customers.
Notably, recent strategic moves underscore forward momentum: an acquisition expanding a sample-fulfillment network, launches of rail ISO tank liquid logistics verticals, the certification of hydrogen-capable ADR trucks in Europe, new chemical carrier vessels, and real-time tracking technologies introduced by major forwarders. Each of these developments signals where investment and competitive intensity will concentrate in 2026.
Regulatory and standards environment: what changes in 2026 mean for operators
-
Air, sea, and road updates effective in 2026 impose immediate operational impacts—from classification and documentation to labelling and packaging. Operators must triage compliance costs and adjust routing protocols and carrier contracts.
-
US harmonization proposals aim to align domestic hazardous materials rules with international practices, which will affect shipping names, packing groups, and permissible quantities. Comments and stakeholder engagement in early 2026 will shape final outcomes.
-
Workplace safety standards (including updated hazard communication rules) raise training and labeling obligations, with knock-on effects for inventory systems, SDS management, and contractor certification.
Our report translates these changes into operational task lists, cost impact ranges, and a compliance roadmap so decision-makers know what to remediate now, what to monitor, and what to treat as contingent exposure.
Strategic imperatives for 2026
-
Prioritize compliance-forward investments: Capex should be targeted to mitigate the highest regulatory and safety risks first—specialized containment, upgraded fire suppression, and audited handling protocols—rather than blanket capacity expansion.
-
Adopt differentiated service models: Move beyond basic storage to offer bundled compliance, traceability, and emergency-response commitments that command premium pricing and stickier customer relationships.
-
Use technology as a risk reducer: Invest in real-time monitoring, incident analytics, and digital documentation to reduce insurance premiums and accelerate regulatory reporting.
-
Prepare for modal rebalancing: Expect modal shifts driven by fuel constraints, emissions policies, and routing restrictions. Evaluate intermodal options and tank container strategies as alternatives to single-mode dependence.
-
Design M&A and alliance plays with a liability-first lens: Acquire or partner where regulatory expertise and documented safety records lower integration risk more than scale alone.
How PW Consulting’s analysis supports action
This report is structured to move executives from insight to action. Beyond headline forecasts, it provides transaction-grade diligence materials, scenario-tested investment cases, and an operational checklist keyed to 2026 rule changes. Whether you are a logistics executive reconfiguring your network, a chemical manufacturer outsourcing hazardous-storage tasks, or a private equity house assessing platform buys, the study delivers the models, metrics, and playbooks to make defensible decisions this year.
Call to action
We designed this release as a strategic trailer: it highlights the evidence base, competitive dynamics, and regulatory inflection points that matter in 2026, while preserving the detailed segmental and regional data that drive deal-level choices. To access the full dataset, detailed segment forecasts, and the practitioner toolkits (including RFP templates, TCO models, and compliance checklists), please visit the PW Consulting report page. Use our analysis to convert regulatory disruption into competitive advantage and to prioritize investments that de-risk growth in the hazardous chemical warehousing and logistics space.
For detailed analysis of this topic, please visit the official page: Hazardous Chemical Warehousing And Logistics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com