

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts 6.1% CAGR, Fueling Strong Growth in the Low Voltage Motor Control Center Market Through 2032

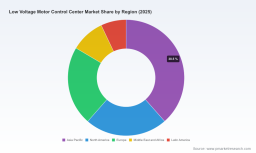
Low Voltage Motor Control Center Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s latest market study on the Low Voltage Motor Control Center (LV MCC) market provides a forward-looking intelligence package tailored for executive teams making capital, procurement, and product-strategy decisions in 2026. The market has shown steady expansion — from USD 4,210.5 Million in 2020 to USD 5,735.66 Million in 2025 — and, under the base-case projection in our report, is expected to reach USD 8,681.44 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.1% across the 2026–2032 forecast window. This preview highlights the report’s strategic value while intentionally withholding detailed sub-segment data to encourage stakeholders to consult the full analysis for transaction-grade intelligence.
Low Voltage Motor Control Center Market
Why 2026 Is a Pivotal Decision Point
Several converging forces make 2026 a decision inflection for owners, OEMs, EPCs, and investors exposed to LV MCCs. Regulatory tightening on workplace safety and international switchgear standards has elevated design requirements (notably around IEC 61439 compliance and arc-resistant features). Simultaneously, industrial decarbonization and energy-efficiency mandates are accelerating demand for intelligent motor control centers that integrate variable frequency drives (VFDs), energy monitoring and predictive analytics.
Low Voltage Motor Control Center Market
At the same time, supply-side dynamics — including elevated steel prices compared to pre-2020 levels and episodic material volatility — are reshaping procurement windows, lead-time expectations, and life-cycle cost calculations. The combined effect is a market that is structurally growing and re-composing: more value will accrue to solutions that blend safety, modularity, and digital services rather than to commoditized hardware alone.
Low Voltage Motor Control Center Market
What the Report Delivers: Operational Insights for Executives
- Robust market sizing and forward-looking forecasting across the 2026–2032 horizon, with scenario variations to stress-test investment cases under different adoption and price trajectories.
- Actionable vendor benchmarking and capability maps that evaluate product architectures (conventional vs intelligent), safety features (arc-resistant designs, optical arc detection), digital integration (IoT, predictive maintenance), and aftermarket service models.
- Procurement and TCO playbooks including sample lifecycle cost models, retrofit vs replace matrices, and sourcing strategies to mitigate raw-material-driven cost risk.
- Go-to-market and product roadmaps for OEMs and system integrators, identifying modularity levers, integration points for VFDs and energy management, and templates for compliance and certification programs.
- M&A and partnership screening tools built around predefined value-creation triggers: geographic reach, digital capability, aftermarket coverage, and customization/remanufacturing competence.
- Fieldable case studies and deployment checklists that reduce execution risk for retrofit pilots, greenfield installations, and integrated automation projects.
Note: the report contains granular segmentation by region, product type, and end-use application with transaction-grade models. This preview purposefully omits detailed split data; full access provides the sub-segment tables and interactive models decision teams require.
Competitive Landscape: Strategic Footprints and Differentiation
The LV MCC market remains moderately concentrated: the top three global players control a meaningful share of installed capacity, and the top five expand that position substantially. This structure fosters competition on product breadth, digital integration, and safety certification rather than on price alone.
- Technology & Digital Leaders — Global electrification and automation names are privileging connectivity and analytics. Vendors with mature IoT platforms, established motor management suites, and open integration pathways are positioned to capture higher-value deals where predictive maintenance and energy optimization are mandated.
- Safety & Compliance Differentiators — Manufacturers that emphasize arc mitigation, maintenance-mode design, zone-selective interlocking, and compliance with the latest IEC frameworks are winning contracts in high-risk industries and regions with strict insurance and regulatory oversight.
- Customization and Remanufacturing Specialists — Regional fabricators and remanufacturers that offer UL-approved retrofits and tailored solutions remain critical for utilities, brownfield industrial sites, and owners seeking life-extension at controlled capex.
Representative companies illustrate these archetypes and their strategic choices:
- ABB Ltd. — Focuses on safety-forward LV MCC solutions with integrated monitoring and plug-and-play starters to serve heavy industry and utilities.
- Schneider Electric SE — Emphasizes modular, arc-resistant architectures with deep connectivity via its EcoStruxure ecosystem aimed at predictive maintenance and energy efficiency.
- Eaton Corporation — Positions safety and reliability at the core, pairing arc-resistant options with VFD integration for industrial power distribution.
- Siemens AG and Rockwell Automation — Leverage IoT and motor-management capabilities as differentiators; Rockwell’s recent FLEXLINE product introductions underline the race for real-time insight at the MCC level.
- WEG, Mitsubishi Electric, General Electric and large regional players — Compete on global manufacturing scale, localized service footprints and tailored product formats for compact or containerized applications.
- Powell, Tesco Controls, RESA Power — Carve value in custom assemblies, remanufacturing and UL-compliant field services, attractive for organizations with legacy fleets.
Recent market activity underscores these dynamics: product launches that emphasize modularity and data (for example, a FLEXLINE 3500 launch showcased at Hannover Messe) and major suppliers presenting energy-transition frameworks at 2026 industry shows signal that vendors are commercializing integrated, energy-focused offerings.
Practical Playbook for 2026 Decision-Makers
Executives can translate market intelligence into a pragmatic sequence of actions that align technology adoption, procurement rhythm and risk management:
- Prioritize intelligent MCCs in new builds where energy mandates, uptime value, or remote operations justify higher initial capex. Quantify payback using energy- and maintenance-savings scenarios from the report’s TCO modules.
- Adopt a staged retrofit strategy for existing fleets: pilot intelligent bus sections, instrument VFD integration points, and roll out predictive-maintenance sensors in high-failure or high-energy-consuming circuits first.
- Lock in procurement windows and hedges to mitigate steel-price and component lead-time volatility; the report includes vendor-specific lead-time benchmarks and suggested contractual terms.
- Request vendor scorecards during RFPs emphasizing digital APIs, arc-mitigation design, modularity and aftermarket SLAs — the full benchmarking matrix in the report can be adapted to RFP templates.
- Build aftermarket revenue and service continuity through bundled monitoring, spare parts programs and certified remanufacturing partnerships to extend asset life and reduce unplanned downtime.
- Use scenario-based capital planning — incorporate sensitivity runs for raw material cost swings, regulatory tightening and adoption curves to stress-test investment timelines and internal rates of return.
Risk & Sensitivity Considerations
Key risk vectors we evaluate in the report include raw-material cost volatility (steel is a material driver), regulatory shift risk (e.g., faster-than-expected adoption of arc-resistance mandates), supply-chain concentration for key components, and cybersecurity exposure as MCCs become networked. Each risk is mapped to mitigation levers and an estimated financial buffer that executives should incorporate into 2026 budgets.
Closing: Strategic Value for 2026 and Beyond
For organizations deciding where to allocate capex and which vendors to partner with in 2026, the right mix of intelligence is simple: combine forward-looking market sizing, scenario stress tests, vendor deep-dives and operational playbooks. PW Consulting’s LV MCC report synthesizes these elements into a single decision-ready product that helps executives prioritize investments that maximize uptime, improve safety compliance, and accelerate energy-efficiency gains.
This preview is designed to demonstrate the analytical depth available in the full study while protecting the granular sub-segmentation that underpins transactional decisions. For the complete dataset — including regional and end-user breakdowns, interactive models, vendor scorecards and procurement templates — please consult the PW Consulting report landing page or contact our commercial team for enterprise access and a tailored briefing.
For detailed analysis of this topic, please visit the official page: Low Voltage Motor Control Center Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com