

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ballistic Protection Market Poised to Reach USD 23,819.54 Million by 2032, Expanding at a 6.35% CAGR (2026–2032)

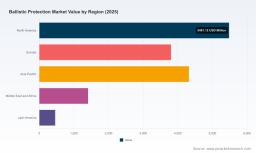
Ballistic Protection Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
As geopolitical tensions, asymmetric threats, and law-enforcement modernization continue to drive demand for survivability solutions, the ballistic protection market is entering a phase of sustained, technology-led expansion. PW Consulting’s latest market study — covering the historical period 2020–2025 and providing a detailed 2026–2032 forecast — synthesizes primary supplier intelligence, materials economics, regulatory shifts, and procurement behavior into a pragmatic playbook for executives making decisions in 2026.
Ballistic Protection Market
Executive snapshot
-
Market scale and trajectory: Our base-year assessment positions the global ballistic protection market at roughly USD 15.5 billion in 2025, with a projected expansion to nearly USD 23.8 billion by 2032. The forecasted compound annual growth rate for the 2026–2032 window is 6.35%.
Ballistic Protection Market -
Market structure: The sector exhibits moderate concentration — the top three firms account for a meaningful share of market revenue, and the top five consolidate a clear majority — indicating that competitive dynamics are driven by a mix of incumbent scale and pockets of specialist innovation.
Ballistic Protection Market -
Near-term drivers: Updated certification standards (notably the NIJ 0101.07 transition and related NATO guidance) and material substitution trends (accelerating uptake of UHMWPE and advanced unidirectional laminates) are catalyzing upgrade cycles across defense and civil protection procurement programs.
Why this report matters for 2026 decision-making
-
Stop guessing; start prioritizing — 2026 will be the year to convert program-level intent into procurement and R&D budgets. Our model quantifies demand windows and replacement cycles that align with new NIJ and STANAG test requirements, enabling CFOs and business unit leaders to time capital deployment and inventories.
-
Material risk is strategy — raw material cost trajectories and substitution tradeoffs (e.g., aramid vs. UHMWPE) will determine margin outcomes for manufacturers and OEMs. The report delivers sensitivity matrices showing how +/- X% feedstock moves translate to margin compression or gain under multiple pricing scenarios.
-
Competitive posture calibrator — whether you are an OEM, a materials supplier, or a systems integrator, our vendor scorecards and capability maps let you benchmark technological depth, certification readiness, and aftermarket support capacity to inform partnership or M&A decisions.
Actionable strategic implications for 2026
-
Materials and R&D
Invest selectively in UHMWPE and advanced unidirectional laminate partnerships. Industry evidence shows UHMWPE continues to displace heavier aramid solutions in weight-sensitive platforms. But aramid supply cost volatility remains a near-term risk — hedging supplier relationships and co-investing in alternative fiber processing or recycling pathways can be a defensive moat.
-
Production and supply chain
Prioritize dual-sourcing for critical feedstocks and modularize production to shorten lead times. Recent capacity expansions in North America suggest on-shoring incentives will persist; companies should evaluate capacity uplift options (tooling, automation, lean flow) in 2026 to capture restructuring contracts and fast-turn government orders.
-
Commercial & procurement strategy
Embed certification roadmaps into product development cycles. The NIJ 0101.07 transition creates a commercially actionable window: bidders who can demonstrate certification-readiness alongside human-factor designs (including gender-fit solutions) will displace legacy incumbents in many tenders.
-
M&A, alliances and capex
The market’s concentration profile indicates attractive roll-up opportunities in specialized niches — ultra-light plates, helmet systems, and vehicle applique armor. Use a three-tier acquisition filter (technology fit, certification footprint, aftermarket sustainment potential) to prioritize targets in 2026.
-
Pricing and margin management
Implement dynamic pricing linked to raw-material indices and certification-related value-add. Given feedstock cost pressures in late 2025, forward priced contracts and value-based pricing for certified, lighter-weight solutions will preserve margins during demand upcycles.
-
Aftermarket & sustainment
Warranty and lifecycle support will be decisive differentiators for defense procurement. Design aftermarket bundles (inspection, re-certification, spares) that convert one-off sales into recurring revenue streams — particularly in vehicle and heavy-platform segments.
Competitive landscape — who matters and why
The competitive map of ballistics is a hybrid of global defense primes, specialist materials suppliers, and focused tactical-equipment firms. PW Consulting’s qualitative benchmarking highlights several archetypes:
-
Integrated defense primes (e.g., BAE Systems plc, Rheinmetall AG) — strengths in platform-level integration and armored vehicle programs; positioned to capture large defense modernization budgets and systems-of-systems contracts.
-
Material innovators (e.g., DuPont de Nemours, Honeywell, Teijin, Avient/Dyneema) — supply advanced fibers and composite solutions that define performance envelopes; partnering with these suppliers accelerates lightweighting without repeating fundamental materials R&D.
-
Specialist PPE and tactical suppliers (e.g., Point Blank Enterprises, Avon Protection, Safariland) — deep channel access to law enforcement and first responder markets, with rapid product-cycle agility for NIJ certification updates and ergonomic design changes.
-
Regional systems integrators and manufacturers (e.g., MKU Limited, NP Aerospace, Morgan Advanced Materials) — provide localized manufacturing, cost-competitive offerings, and niche composite expertise attractive to regional procurement authorities.
-
New entrants and scale-ups — recent product launches and capacity investments (e.g., ultra-light helmets, hard ballistic unidirectional materials, and domestic capacity expansion) signal continued disruption. Strategic buyers should monitor these entrants for bolt-on opportunities and defensive partnerships.
Recent industry moves to note: product launches introducing ultra-lightweight combat helmets and hard unidirectional materials that claim substantial weight reductions; capacity investments aimed at shortening domestic supply chains; and targeted contracts for Indo-Pacific operations — all of which confirm that both incremental and radical innovation are being commercialized now.
Regulation, standards and procurement pulse
The NIJ 0101.07 update and revisions to NATO STANAG testing protocols have two practical consequences for 2026 planning:
-
Certification-driven demand: Procurers will accelerate fleet upgrades and replacement programs to meet updated protection and anthropometric (including women’s armor) requirements. Firms that pre-plan certification pathways gain first-mover contract advantage.
-
Design-for-certification: Product roadmaps must incorporate test-validated human factors and add-on modularity to shorten pass-fail iterations — a development discipline that rewards firms with established ballistic testing partnerships or in-house labs.
Report contents — what you get (and what we deliberately omit here)
PW Consulting’s full market report is designed as an operational resource, not just a high-level read. Key components include:
-
A bottom-up revenue forecast model with scenario toggles for material pricing, defense procurement pacing, and certification-led replacement cycles.
-
Vendor scorecards that measure certification breadth, manufacturing footprint, materials partnerships, and aftermarket capability.
-
Risk heatmaps covering raw-material exposure, supply-chain disruption probabilities, and regulatory compliance risk.
-
Commercial playbooks: bid-win strategies tailored to defense primes, law-enforcement contracts, and OEM channels.
-
M&A screening tools and a prioritized list of acquisition targets by strategic fit.
Consistent with our “trailer” approach, this press brief intentionally omits granular regional and application-level breakdowns, as well as specific segment revenue splits — insights we reserve for report subscribers and tailored client engagements to protect proprietary methodologies and incentivize direct data access.
For strategy teams: three immediate moves for 2026
-
Secure certification pipelines — allocate R&D and testing budget now to align products with NIJ 0101.07 and anticipated NATO test updates.
-
Negotiate material partnerships — lock multi-year supply agreements with UHMWPE and ceramic composite suppliers, including joint-development options to share upgrade costs and speed time-to-market.
-
Stress-test M&A targets — use our vendor scorecards to run a rapid due-diligence pass on niche innovators whose technologies can be integrated into broader systems offerings.
Next steps & how to access the full intelligence
PW Consulting’s Ballistic Protection Market report is available now. The full deliverable provides the quantitative datasets, supplier matrices, and executable playbooks referenced above — essential tools for executives planning procurement, product roadmaps, and M&A strategies in 2026. To request the report, a tailored executive briefing, or our interactive model for in-house scenario planning, visit the PW Consulting research portal or contact our industry team for immediate access.
In a market where certification timetables, materials innovation, and procurement cycles converge in 2026, being early to operationalize these signals will determine winners and laggards. Our report turns those signals into prioritized actions.
For detailed analysis of this topic, please visit the official page: Ballistic Protection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com