

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fluid Management System Market to Rise from USD 12,880 Million in Base Year 2025 to USD 20,267 Million by 2032 at a 6.69% CAGR — North America, Standalone Systems and Urology Drive Growth; Top 3 Hold 42.5%

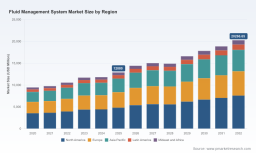
Fluid Management System Market 2026: Strategic Imperatives from PW Consulting
Executive summary
PW Consulting’s latest Fluid Management System Market report (base year 2025; historical coverage 2020–2025; forecast window 2026–2032) provides a forward-looking, operational playbook for executives preparing critical 2026 decisions. The market reached approximately USD 12.88 billion in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 6.69% over the forecast period, reaching roughly USD 20.27 billion by 2032. These macro dynamics underscore both the size of the opportunity and the urgency of clarifying strategic choices now—whether you are an OEM, a hospital procurement lead, an investor, or a distributor.
Fluid Management System Market
Why this report matters for 2026 decision-making
-
Timing: 2026 is a junction year. Near-term approvals and product launches are reshaping commercial windows; our 2026-oriented analysis isolates the decisions that will determine whether a player gains preferred-provider status or cedes ground.
Fluid Management System Market -
Actionability: Beyond forecasts, the report supplies executable assets—market-entry scorecards, procurement TCO templates, and a regulatory-watch matrix—that link hypotheses to capital allocation and go-to-market execution.
Fluid Management System Market -
Risk-informed growth: We quantify sensitivity to three critical risk vectors—regulatory cadence, polymer/raw-material availability, and shifting procedural volumes in minimally invasive surgery—enabling scenario planning tied to balance-sheet outcomes.
-
Competitive clarity: With concentration metrics showing a market where the top three and top five players account for a meaningful share of revenue, our analysis surfaces where scale matters and where specialist players can win through clinical differentiation or service models.
What’s inside: practical, operational deliverables
This is not a vanity deck. The report is built to change behavior and resource allocation in 2026. Key deliverables include:
-
Proprietary market model (2020–2032) with downloadable scenario tabs enabling clients to re-run forecasts under alternative CAGR and pricing assumptions.
-
Regulatory and approval tracker that maps recent clearances and pending applications to expected commercial impact windows—updated through Q1–Q2 2026.
-
Supply-chain heatmap focused on critical polymers, tubing and connector subcomponents, with mitigation strategies and cost-to-implement estimates.
-
Commercial playbooks for hospitals and OEMs: tender/negotiation scripts, bundled-services pricing templates, and KPI dashboards to measure adoption of integrated systems versus disposables.
-
Vendor scorecards and a proprietary M&A heatmap that identify highest-value targets by capability gap (e.g., digital fluid tracking, disposable assembly, renal hydration platforms).
-
Case studies illustrating successful transitions from product to solutions revenue models—complete with implementation milestones and expected ROI timetables.
Note: detailed segment-level revenues and regional/application splits are intentionally withheld from this release to preserve the publisher’s proprietary value; those granular tables and company-level revenue breakdowns are available exclusively in the full report.
Competitive landscape: mapping strategy to capability
The competitive field combines diversified medtech incumbents, procedure-specialist OEMs, and a growing presence of industrial players applying digital field capabilities to fluid handling. Select strategic observations:
-
Stryker Corporation: Continues to integrate optics and fluid control for urology and hysteroscopy. Its recent product activity reinforces a platform strategy—bundling reusable scopes with dedicated fluid management units to lock in recurring consumable sales and clinical workflows.
-
Boston Scientific Corporation: The March 2026 regulatory clearance for its Asurys system accelerates its ability to compete across multiple urologic endoscopic procedures. Clearances of this type shorten sales cycles with large integrated delivery networks that prefer cleared, single-vendor solutions.
-
Baxter, B. Braun, Medtronic and Fresenius: Each brings scale and clinical trust in adjacent spaces—critical when health systems seek single-source solutions for irrigation, suction, and renal fluid platforms. These firms are well-positioned to push bundled-service offers into procurement cycles.
-
Specialists (CONMED, Hologic, Karl Storz, Olympus, Smith & Nephew): Maintain competitive advantage through focused clinical lifecycles, high-sensitivity visualization integration, and partnerships with surgical centers of excellence.
-
Non-traditional entrants (Ecolab via Skytron, Graco): Demonstrate new go-to-market vectors—Ecolab through integrated healthcare environment services, Graco through digital field dispensing solutions (Pulse Mobile). These moves signal cross-industry commoditization pressure on low-margin accessory segments.
Strategic implication: the market reward to vertical integration and digital-enabled service models is rising. Our CR3 and CR5 concentration metrics indicate mid-level consolidation: scale delivers distribution and contracting leverage, but clinical differentiation and service-level agreements still create defensible niches.
Recent developments that change the playbook (Q1–Q2 2026)
-
Boston Scientific’s U.S. FDA 510(k) clearance (March 2026) expands the validated use-cases for a single system across multiple urologic procedures—altering procurement conversations and clinical evaluation timelines.
-
Stryker launched a flexible ureteroscope and complementary fluid management offering (February 2026), reinforcing the trend toward device-system bundling for procedure standardization.
-
Graco’s Pulse Mobile launch (March 2026) highlights a cross-sector opportunity: digitization of fluid inventory and tracking in field and hospital support functions is a rapidly adoptable efficiency play that incumbents can emulate or partner to incorporate.
-
Raw-material realities: specialized polymers and tubing components remain a constrained input for medical-grade fluid systems; procurement strategies and alternate-material R&D are now table-stake considerations.
Market dynamics and material risks
-
Growth driver: continued shift to minimally invasive procedures fuels demand for precision inflow/outflow control and visualization-integrated systems—both clinical and economic drivers point to higher adoption rates.
-
Risk: regulatory timelines and reimbursement uncertainty can compress near-term returns. Recent clearances change competitive dynamics quickly; those without timely filings will struggle to compete in bundled tenders.
-
Supply-chain vulnerability: dependency on specialized polymers increases cost and delivery volatility; early supplier diversification and design-for-manufacturability investments yield outsized risk reduction.
-
Commercial pressure: growing adoption of disposables and service contracts creates margin mix shifts that must be modeled explicitly in 2026 budgets.
Concrete strategic recommendations for 2026
-
Prioritize regulatory filings that unlock multi-procedure claims. One cross-procedure clearance can reprice the commercial opportunity and accelerate contracting wins.
-
Invest selectively in digital capabilities (fluid tracking, remote monitoring) to create service revenue and defensibility—partner where software development timelines are misaligned with clinical cycles.
-
Hedge polymer exposure by qualifying multiple suppliers and accelerating alternate-material validation programs—allocate near-term capex to minimize medium-term supply shocks.
-
Shift sales incentives toward bundled solutions and outcome-based pilots: buyers increasingly reward measurable OR throughput improvements and lower TCO.
-
Use M&A to fill capability gaps—target small, clinically validated firms that offer disposables, software, or single-procedure dominance rather than broad, overlapping portfolios.
-
For hospitals and IDNs: run procurement pilots that capture clinical, operational, and environmental KPIs to differentiate capital allocation across competing OEMs.
How PW Consulting supports your 2026 agenda
Our Fluid Management System Market report is a practical toolset: the downloadable financial model lets you stress-test acquisition targets and procurement scenarios; the vendor scorecards and M&A heatmap reveal where to deploy limited investment capital to unlock outsized clinical and commercial returns; the supply-chain playbook provides implementation steps and estimated timelines for de-risking material constraints.
To preserve the competitive integrity of the analysis, we have intentionally limited disclosure in this release. The full report contains detailed regional and application splits, company-level revenue estimates, and the raw model files needed to integrate our projections into your enterprise planning processes.
Next steps
For executives preparing budgets, M&A pipelines, or clinical adoption plans in 2026: request a briefing with our senior analysts to see tailored scenario outputs and to obtain the full dataset and executable templates. PW Consulting’s advisory team will walk you through how the forecast, regulatory calendar, and supplier actions translate into concrete capital and commercial decisions for the year ahead.
For detailed analysis of this topic, please visit the official page: Fluid Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com