

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Mechanical Dust Collector Market Set to Expand at a 4.8% CAGR

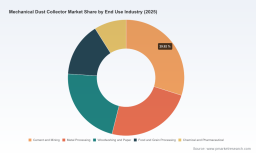
Mechanical Dust Collector Market: Strategic Imperatives for 2026 — PW Consulting Insights
As companies prepare capital expenditure plans and operational upgrades for 2026, the Mechanical Dust Collector market presents a mix of steady growth, concentrated competitive dynamics, and heightened regulatory pressure that will reshape supplier selection, technology adoption, and aftermarket strategies. PW Consulting’s new market study — grounded in a 2020–2025 historical review and projecting through 2032 — distills these dynamics into an actionable playbook for industrial operators, OEMs, and investors.
Mechanical Dust Collector Market
Market snapshot: trajectory and what it means for decision-makers
Our analysis positions the mechanical dust collector market at approximately USD 648.2 Million in the base year (2025), with a forecast that reflects a compound annual growth rate (CAGR) of 4.8% over the 2026–2032 horizon. By 2032 the marketplace is expected to approach the USD 900 Million threshold. The growth profile is characterized by incremental replacement cycles, regulatory-driven retrofit programs, and selective greenfield demand tied to heavy industries such as cement, metal processing, and food handling. These macro figures are a valuable north star for budgeting but mask important tactical choices that will determine winners at the plant level.
Mechanical Dust Collector Market
Why this report matters for 2026 planning
- Capital prioritization: With steady but not explosive growth, 2026 will reward disciplined CapEx — prioritizing compliance upgrades and efficiency retrofit projects with demonstrable payback horizons.
- Regulatory acceleration: Near-term regulatory thresholds (notably metal-processing emission standards) mean many operators must accelerate upgrades or risk non-compliance penalties and production interruptions.
- Supply-chain & cost pressure: Fabrication input volatility is compressing supplier margins and forcing negotiation on lead-times and standardized designs.
- Aftermarket & services: As systems mature, aftermarket revenue (filters, service, monitoring) will be an increasingly strategic differentiator for OEMs and a lever for operators to control lifecycle costs.
Core market dynamics shaping 2026 decisions
Our research synthesizes regulatory, raw material, labor, and safety vectors into a cohesive scenario set that operators must consider when building their 2026 investment roadmap.
Mechanical Dust Collector Market
- Regulatory compliance is now a gating factor: Recent federal standards require near-total particulate control in specific metal-processing applications, pushing many operators to specify equipment with 99.9% capture efficiency or to add supplementary treatment steps. For 2026, compliance-driven retrofits will be a primary demand source.
- Combustible dust safety drives upgrade cycles: Directives on explosion-proof collection and associated systems have generated pockets of accelerated upgrade demand — our modeling suggests these mandates are responsible for a material uplift in retrofit activity, creating windows for multi-site rollouts.
- Input-cost compression and lead-time risk: Fabrication materials experienced meaningful price increases in recent quarters, while skilled maintenance labor rates have risen materially as well. These factors raise both CapEx and ongoing Opex profiles, shortening the payback period needed to justify new deployments.
- Service & digitalization as profit centers: Remote monitoring, predictive filter-change scheduling, and service contracts are emerging as high-margin businesses for best-in-class suppliers. Operators that embed lifecycle metrics into procurement specifications realize lower total cost of ownership over five- to seven-year horizons.
What the PW Consulting report delivers — practical, decision-ready outputs
This study is built for executives, plant managers, and procurement leads who must translate market signals into 2026 actions. Key operational deliverables include:
- Scenario-based demand forecasts tied to regulatory adoption timelines and maintenance cycles.
- CapEx/Opex models that quantify trade-offs between retrofit vs. replacement, including sensitivity to steel-price and labor-cost shocks.
- Procurement scorecards and technical specifications templates for vendors, aligned to performance thresholds and explosion-proof requirements.
- Aftermarket and service-play frameworks that calculate lifecycle economics for filters, cleaning systems, and digital monitoring.
- Supplier risk heatmaps and a due-diligence checklist for M&A or strategic partnership evaluation.
- Case studies and ROI calculators to justify multi-site upgrade programs to corporate finance.
We intentionally present these outputs in operational format — not as abstract statements — so that procurement cycles scheduled in early 2026 can be aligned with capital appropriation windows and compliance deadlines.
Competitive landscape: how leading vendors are positioning for 2026
The mechanical dust collection industry remains moderately fragmented; the top three suppliers do not dominate the market, leaving room for differentiated service models and niche specialization. Our competitive analysis highlights the strategic postures of leading suppliers and what they signal for buyers in 2026.
- Donaldson Company, Inc. (Bloomington, MN) — A long-standing leader in industrial filtration, Donaldson continues to steward the Torit line with iterative upgrades. Recent trade-show activity highlighted enhanced filter media targeted at metal fabrication — an explicit play for compliance and efficiency-conscious customers.
- Camfil APC (Jonesboro, AR) — Camfil’s launch of a higher-efficiency cartridge series underscores a strategy focused on fine-dust applications and premium aftermarket capture through improved filter lifetimes and energy performance.
- Nederman (Helsingborg, Sweden) — Nederman is reinforcing energy-efficiency narratives with cyclone and pulse-jet systems designed to lower operational energy draw, appealing to industrial users with aggressive sustainability targets.
- RoboVent (Sterling Heights, MI) — Specialized high-efficiency particulate solutions position RoboVent well in automotive and aerospace segments where tight emissions and cleanliness specs drive premium pricing.
- Wheelabrator / Archetype (Pittsburgh, PA) — Focused on surface prep and blasting operations, their reverse-pulse systems continue to win in heavy-duty applications that demand robustness and uptime.
- Ceco Environmental / Peerless (Cincinnati, OH) — Their emphasis on high-temperature fabric filters and power-generation-grade systems is a differentiator for industrial clients with elevated thermal streams.
- Schust Engineering (Holland, MI) — A custom-design player that is frequently selected where application-specific cartridges or housings are required, especially in food and chemical processing.
- Aget Manufacturing (Jordan, MN) — A strong presence in agricultural and woodworking channels, where cost-effective, reliable designs and aftermarket availability matter most.
Recent corporate moves — trade-show showcases and product launches during 2025 — indicate that suppliers are prioritizing efficiency improvements, filtration media innovation, and energy reduction. For procurement teams, supplier selection in 2026 will hinge on three capabilities: product performance vs. regulatory thresholds, service coverage (including predictive maintenance), and supply-chain resilience.
Risks, hidden costs, and mitigation paths
Beyond headline compliance and CapEx, operators should be mindful of several underappreciated risk vectors:
- Material-price pass-through: Steel-price volatility can materially alter project economics between specification and delivery. Contractual clauses for price locks or hedging should be part of procurement playbooks.
- Labor-driven service variability: Rising maintenance labor rates mean in-house servicing may no longer be the lowest-cost path; structured service agreements or performance-based contracts can provide cost certainty.
- Integration & controls: As dust collectors are increasingly specified with monitoring and safety interlocks, integration complexity with plant control systems can create installation delays unless accounted for in project timelines.
- Regulatory bifurcation: Diverging regional enforcement intensity can produce stranded compliance investments if firms over-specify for the long tail rather than prioritize targeted, high-impact sites.
A concise playbook for 2026 decision-makers
- Prioritize compliance-critical sites: Map facilities against regulatory exposure and schedule 2026 budgets to close the top percentile of non-compliance gaps first.
- Bundle procurement & service: Negotiate multi-year service + parts contracts at the point of equipment purchase to lock lifecycle economics and reduce downtime risk.
- Stress-test CapEx models: Incorporate steel-price and labor-rate sensitivities into all business cases and include escalation contingencies in supplier agreements.
- Leverage modularity: Favor modular solutions that allow phased upgrades and future-proofing for stricter emissions or digital monitoring add-ons.
- Use third-party verification: Require independent performance testing and commissioning protocols to validate vendor claims on efficiency and energy use.
Accessing the full analysis
PW Consulting’s Mechanical Dust Collector Market report contains the granular regional and application segmentation, vendor benchmarking tables, detailed financial models, and downloadable ROI calculators that procurement, engineering, and finance teams need to finalize 2026 plans. This article intentionally highlights the strategic contours and operational implications — the full dataset and executable templates are available through our report portal for teams that require the underlying numbers and bespoke scenario modeling.
For organizations that must make deployment decisions in early 2026, the combination of regulatory deadlines, input-cost pressure, and the maturing aftermarket opportunity means that the next 12 months are decisive. PW Consulting’s study is designed to move beyond high-level forecasts and provide the pragmatic tools to convert market insight into executable programs.
For detailed analysis of this topic, please visit the official page: Mechanical Dust Collector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com