

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: One‑Stop Enterprise Collaboration Market Set for 12.48% CAGR, Surging to USD 179 Billion by 2032

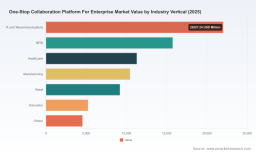
One Stop Collaboration Platform For Enterprise Market — Strategic Preview for 2026 Decision Makers
PW Consulting’s newest market intelligence release, "One Stop Collaboration Platform For Enterprise Market," equips senior executives, procurement leaders, and product strategists with the directional clarity needed for 2026. Built on a base year of 2025 with a historical window covering 2020–2025 and a forward-looking forecast through 2032, the report maps a high-growth landscape. The global market reached approximately USD 78,500 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 12.48%, reaching roughly USD 179,000 Million by 2032. These headline metrics frame a rapidly maturing category where consolidation, AI-driven differentiation, and regulatory pressure will determine winners and losers.
One Stop Collaboration Platform For Enterprise Market
Why this report matters to decisions in 2026
2026 is the juncture at which strategic choices made by enterprises—platform standardization, AI governance, procurement terms, and data residency—will materially affect total cost of ownership, time-to-value, and organizational agility for the remainder of the decade. PW Consulting’s report translates macro momentum into practical decision levers. Rather than presenting raw fragmentary figures, the research synthesizes demand signals, vendor behaviors, and regulatory developments into a decision framework executives can operationalize immediately.
One Stop Collaboration Platform For Enterprise Market
What the report contains — practical, executable content
- Executive synthesis: concise strategic takeaways for boards, CIOs, and heads of collaboration/transformation programs, focused on near-term priorities and long-term optionality.
- Market sizing & methodology: transparent modeling assumptions, sensitivity testing, and scenario paths that reconcile historical adoption with technology inflection points.
- Vendor scorecards and competitive archetypes: qualitative and quantitative assessments of leading platform providers, their go-to-market motions, product strengths, and integration risk profiles.
- Deployment playbooks: step-by-step plans for cloud-first, hybrid, and selective on-premise rollouts — including staging, pilot metrics, change-management checkpoints, and success KPIs.
- Procurement and contracting toolkit: negotiation templates, escape clauses, exit-cost modeling, and consumption-based pricing traps to avoid.
- Compliance & privacy readiness matrix: checklists aligned to evolving U.S. state privacy frameworks, California’s enhanced mandates effective in 2026, and GDPR-equivalent enforcement expectations.
- AI governance and data strategy: a catalogue of controls for safe AI use, human-in-the-loop patterns, model auditing, and vendor assurance clauses.
- Integration blueprints and interoperability tests: reference architectures for identity, directory sync, data pipelines, and unified communications bridging.
- Use-case templates & ROI calculators: role-based adoption scenarios, measurable productivity levers, and conservative financial models for executive sign-off.
- M&A and partnership playbook: due diligence checklists and scorecards for assessing acquisition targets or strategic alliances in a concentrated vendor landscape.
Market dynamics shaping 2026 strategies
Several converging forces are reshaping the one-stop collaboration category. First, cloud economics and infrastructure availability continue to underpin rapid adoption: public cloud spending remains a central enabler of platform scalability and resilience. Second, AI is moving from augmentation to embedded workflow intelligence — not merely speech-to-text but context-aware summarization, automated follow-ups, and orchestrated cross-application actions. Third, hybrid work has normalized requirements for “meeting equity” and room intelligence, pushing hardware and software integration into board-level procurement conversations.
One Stop Collaboration Platform For Enterprise Market
At the same time, regulatory and privacy headwinds are becoming non-trivial strategic constraints. California’s expanded privacy requirements effective January 1, 2026, broader state-level privacy laws, and continuing enforcement of GDPR-like frameworks demand that platform selection incorporate not only feature fit but robust data governance, contractual safeguards for cross-border transfers, and technical controls for automated decision-making transparency.
Competitive landscape — positioning and strategic signaling
The category currently shows meaningful concentration at the top: the three largest vendors account for a substantial share of the market, and the top five intensify that concentration further. This structure creates distinct strategic realities for buyers and challengers alike. Incumbents with integrated productivity suites and native identity ecosystems can deliver rapid enterprise rollouts and deep app integrations, while smaller, specialized players compete on customization, verticalization, and lighter-weight total cost.
- Platform incumbents with broad suites are scaling AI inside native ecosystems to extend enterprise lock-in and reduce integration friction. Recent rollouts that embed advanced assistant capabilities and post-meeting intelligence exemplify this trend.
- Open, tool-agnostic players emphasize extensibility and replaceability, positioning themselves as the “swiss army knife” for organizations unwilling to commit to single-vendor productivity stacks.
- Hybrid specialty vendors and those emphasizing security and compliance are carving niches among regulated industries where data localization, auditability, and bespoke controls are non-negotiable.
Recent vendor moves reinforce these trajectories: major vendors continued to expand AI-capabilities within collaboration suites in late 2025 and early 2026; productivity and project-management platforms introduced AI agents and templating to accelerate time-to-value; and room-system vendors showcased integrations designed for hybrid meeting intelligence. These developments indicate that product differentiation will increasingly be delivered through AI-enabled workflows and ecosystem depth rather than standalone features alone.
Strategic imperatives for 2026 — where to focus
- Prioritize composability over single-vendor absolutism. Build for hybrid integration: prefer platforms that expose robust APIs, standard identity federation, and clear data export paths to avoid lock-in.
- Enforce privacy-by-design and contractual controls. Update vendor contracts to reflect new opt-out and assessment requirements, and require proof points for data minimization and cross-border transfer safeguards.
- Treat AI as an operational risk as well as a productivity lever. Mandate explainability clauses, versioned model audits, and human oversight for any workflow that generates decisions affecting employees or customers.
- Reassess hybrid meeting equity investments. Allocate budget not just for software licenses but for room intelligence, endpoint consistency, and network QoS to sustain user experience at scale.
- Refine procurement KPIs around consumption and elasticity. Negotiate pricing models that align vendor incentives with actual enterprise usage patterns and include clear exit-cost metrics.
- Embed security and compliance into migration roadmaps. Prioritize phased pilots in controlled data domains before broad deployment across regulated units.
What to look for in vendor selection — signal checklist
- Demonstrable enterprise deployments with measurable adoption curves and retention metrics, not just marquee logos.
- Evidence of mature integration capabilities: identity federation, enterprise directory sync, SIEM integrations, and data portability mechanisms.
- Concrete AI governance frameworks, including human escalation paths, model metadata, and incident response playbooks.
- Transparent pricing and well-defined SLAs covering uptime, data residency, and support responsiveness across global operations.
- Compliance-ready artifacts: audits, certifications, and contractual language matching the regulatory regimes relevant to your operations.
How PW Consulting’s intelligence accelerates your 2026 roadmap
The report is designed as both a strategic compass and an operational toolkit. Senior leaders will value the scenario-based sizing and concentration analysis for portfolio decisions; procurement and IT leaders will use the vendor scorecards, RFP clause bank, and TCO models to negotiate and govern active contracts; product and platform teams will find the integration blueprints and AI safety templates useful for implementation. Importantly, while the report reveals market-scale trajectories and competitor archetypes to inform directional choices, granular segment-level data, full vendor scorecard matrices, and downloadable templates are reserved for subscribers and report purchasers — a deliberate design to protect research value and channel readers toward the source for full operational assets.
Next steps — immediate actions for executives
- Commission a 90-day pilot using the report’s deployment playbook to validate assumptions around adoption and ROI in one business unit.
- Run a privacy and AI-risk gap assessment against the report’s compliance matrix to identify contractual and technical remediation needs ahead of regulatory deadlines.
- Apply the procurement toolkit to upcoming renewal negotiations to capture favorable commercial terms and clear exit paths.
- Map your integration dependency tree and ask shortlisted vendors to demonstrate exportable data and API-level access during procurement reviews.
PW Consulting’s "One Stop Collaboration Platform For Enterprise Market" provides the directional insights and practical tools necessary to make defensible 2026 decisions in a fast-evolving category. For access to the full dataset, detailed vendor scorecards, downloadable RFP templates, and the segment-level intelligence that underpins our conclusions, visit the PW Consulting report portal and request the complete study.
For detailed analysis of this topic, please visit the official page: One Stop Collaboration Platform For Enterprise Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com