

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Environmentally Friendly Carbonization Furnace Market to Surge at 10.25% CAGR, Reaching USD 548.05 Million by 2032

Environmentally Friendly Carbonization Furnace Market — Strategic Outlook 2026: A PW Consulting Preview
PW Consulting is pleased to present a strategic preview from our forthcoming market research report on the Environmentally Friendly Carbonization Furnace market. This briefing distills the analysis our clients will rely on when making capital allocation, technology procurement, and M&A decisions in 2026. Designed as a "trailer," it demonstrates the depth of our methodology, highlights the forces that will shape near-term opportunities, and outlines actionable responses — while reserving the full granular segmentation and proprietary scoring behind the paywall to guide execution-level planning.
Environmentally Friendly Carbonization Furnace Market
Market Trajectory — Numbers that Drive Decisions
The market for low-emission carbonization furnaces has moved from a niche sustainability play into an investable industrial segment. Our consolidated market model shows a clear upswing: the global market rose steadily through 2020–2025 and is forecast to sustain double‑digit expansion, driven by tightening emissions policy, rising demand for biochar and biocarbon products, and accelerating industrialization of enclosed, low-emission furnace technologies. For planning purposes, our forecast period (2026–2032) is projected to expand at a compound annual growth rate (CAGR) of approximately 10.25%, reflecting both organic demand growth and technology-driven yield improvements.
Environmentally Friendly Carbonization Furnace Market
For corporate strategists, two takeaways from the topline trajectory are immediate: first, the window for locking in competitively priced equipment and feedstock contracts is finite — early movers capture volume growth with lower marginal installation costs. Second, the sustained growth rate justifies dedicating a portion of 2026 strategic budgets to pilot-to-commercial transitions, including demonstration partnerships and performance‑guaranteed procurement structures.
Environmentally Friendly Carbonization Furnace Market
Key Dynamics Shaping 2026 Decisions
- Regulatory acceleration: Environmental regimes in the EU and North America are prioritizing reduced pollutant emissions and lifecycle carbon accounting for thermal biomass processing. Adoption of enclosed, low-emission furnace designs that enable verifiable carbon sequestration and emissions reporting will be a procurement prerequisite for large buyers and offtake partners.
- Feedstock availability and logistics: Agricultural and forestry residues remain the dominant feedstocks. Abundant supply in certain regions supports localized processing hubs, but feedstock quality variability increases the value of modular preprocessing and flexible furnace designs that can handle mixed biomasses without sacrificing product consistency.
- Application-driven demand: While soil amendment and water treatment applications continue to expand, new demand pockets — including industrial biocarbon as a metallurgical substitute and engineered solutions for PFAS destruction — are emerging. Equipment specifications that deliver tight thermal control and product uniformity will capture premium applications.
- Technology maturation and automation: Advances in control systems, process automation, and thermal recovery are yielding higher throughput and lower operational emissions. Buyers should evaluate both design pedigree and embedded control systems as part of vendor selection.
What the PW Consulting Report Delivers — Operationally Relevant, Decision‑Ready Inputs
Our full report is structured to move executives from strategic intent to operational execution. Core deliverables include:
- Comprehensive market-sizing and demand scenarios across 2026–2032 with sensitivity analyses that quantify the impacts of feedstock price swings, carbon credit value, and regulatory tightening.
- Vendor benchmarking and technology scorecards: techno‑economic comparisons, automation maturity assessment, and standard performance guarantees to guide RFPs and procurement negotiations.
- CapEx/Opex models and total cost of ownership templates that incorporate preprocessing, emissions control, energy recovery, and decommissioning liabilities — designed to be dropped into each client’s financial model.
- Implementation playbooks for pilot-to-scale transitions: site selection checklists, constructability risk matrices, commissioning sequences, and O&M staffing models.
- Regulatory compliance roadmap with jurisdiction‑specific milestones and an emissions reporting template aligned with prevailing EU and North American standards.
- Partnering and M&A decision frameworks to evaluate strategic acquisitions, offtake agreements, and joint ventures — including a shortlist of acquisition archetypes likely to unlock immediate scale or technology advantage.
- Use-case deep dives (soil amendment, charcoal, industrial biocarbon, PFAS mitigation) that align furnace specifications to product performance metrics and offtake market expectations.
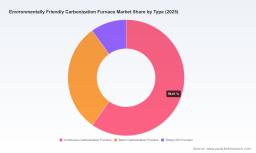
Note: The report purposefully withholds detailed regional and application-level percentage breakdowns in this preview; those segment-level analytics and downloadable vendor scorecards are accessible through the full report portal.
Competitive Landscape — Who Matters and Why
The market remains moderately fragmented, with concentration metrics indicating room for both specialist challengers and acquisitive platform plays — our market concentration analysis places the three-largest players at under one-third of total share and the top five under half. That mix creates an environment where technological differentiation, service models, and tailored financing can rapidly shift competitive position.
- GreenPower LTD (Europe; facilities in Ukraine, Indonesia, South Korea — https://greenpower.equipment): GreenPower remains notable for its patented batch and continuous platform families. Its recent May 2026 product evolution — the rebranding and technical upgrade to the BIO-CARBON continuous system with the ACS 2026 automation suite — signals an emphasis on thermal-control precision and repeatable product quality. For buyers targeting high-consistency biochar or biocarbon outputs, GreenPower’s control package merits close evaluation.
- CHAR Technologies Ltd. (Toronto, Canada — https://www.chartechnologies.com): CHAR’s acquisition of Elkem’s biocarbon assets and the associated offtake agreements (closed April 2026) are tactical moves toward vertical integration and scale. Coupled with their commercial-scale pilot work for PFAS destruction, CHAR is positioning to serve both environmental remediation and high-value industrial biocarbon markets. Strategic investors seeking asset-backed growth should consider partners with integrated feedstock-to-offtake models like CHAR.
- Beston Group Co., Ltd. (Zhengzhou, China — https://www.bestongroup.com): Beston’s demonstrated continuous-operation technical milestone (120 hours continuous in 2024) reflects operational maturity in varied feedstocks. Beston remains a reliable supplier for organizations prioritizing tested throughput and global deployment experience.
- Wilson Biochar, LLC (USA — https://wilsonbiochar.com): Wilson’s on-site Ring of Fire kilns continue to serve decentralized production and community-scale projects where mobility and on-farm application matter more than industrial throughput. Their model suits distributed agriculture and regenerative agriculture programs.
- Chinese OEMs (Zhengzhou Shuliy, Tianjin Mikim, Zhengzhou Belong): These manufacturers offer a spectrum of continuous and batch designs with competitive pricing and rapid delivery potential. Buyers must balance capital cost savings against service footprint, control-system sophistication, and compliance documentation for high-regulation markets.
For procurement teams in 2026, vendor selection should be driven by three criteria: (1) control-system capability for product specification, (2) local service and spare parts ecosystem, and (3) verifiable emissions compliance documentation. Recent vendor moves — product automation upgrades and asset acquisitions — provide clues to which suppliers are building long-term platform value versus those competing primarily on price.
Actionable Recommendations for 2026 Decision-Makers
- Prioritize pilots with embedded KPIs: Execute at least one pilot in 2026 that includes supplier performance guarantees (product yield, emissions limit, energy recovery). Use the pilot to set procurement specs for scale projects.
- Lock in feedstock logistics: Secure multi-year feedstock supply or aggregation agreements in target regions. Invest in flexible preprocessing to reduce feedstock variability risks.
- Evaluate acquisition targets for vertical integration: Look for facilities or technologies that provide immediate offtake linkage or permit-driven processing quotas — these accelerate scale and stabilize margin capture.
- Embed emissions reporting from procurement: Make supplier-provided lifecycle and stack-emission data a mandatory element of RFPs to avoid retrofit costs and compliance delays.
- Design financing around performance: Consider availability-pay structures or lease-to-own with availability SLAs to preserve cash while de-risking plant ramp-up.
How to Use This Preview — Next Steps
This overview communicates the strategic contours that will influence capital allocation and partnership choices across 2026. Executives who need to translate these insights into procurement specifications, investment memoranda, or M&A target lists should consult the full PW Consulting report for:
- Detailed regional and application segmentation (including downloadable tables and interactive scenarios).
- Vendor scorecards and red/green procurement checklists ready to be embedded into RFPs.
- Financial models and sensitivity workbooks tailored to different feedstock and regulatory scenarios.
Access to the full report will provide the granular segmentation, competitive scoring, and downloadable tools required to execute with confidence. For bespoke support — including vendor due diligence, pilot design, or acquisition screening — PW Consulting’s industry practice is available for retained advisory engagements.
PW Consulting’s research makes one central proposition clear: the Environmentally Friendly Carbonization Furnace market is no longer an experimental niche — it is a scaling industrial market where timing, technology selection, and regulatory alignment will determine winners. Use the next 12 months to validate suppliers under live conditions, secure feedstock economics, and lock in compliance-positive designs. Those actions will convert favorable market growth into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Environmentally Friendly Carbonization Furnace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com