

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Maskless Lithography Systems for Semiconductor Packaging to Expand at 11.48% CAGR, Reaching USD 1,817.45 Million by 2032

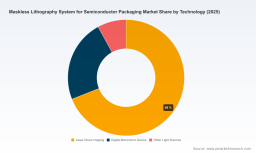
Maskless Lithography System For Semiconductor Packaging Market: Strategic Outlook for 2026 Decision-Makers
As semiconductor packaging evolves from a cost-driven commodity into a strategic differentiator for performance, power and integration density, maskless lithography is moving from “interesting alternative” to a must-evaluate technology for OEMs, OSATs, IDMs and equipment investors. PW Consulting’s latest market research — anchored on a 2025 base year and a 2026–2032 forecast horizon — finds the global maskless lithography systems market has entered a sustained growth phase, expanding from early commercial deployments into broader high-volume use cases. At the macro level, the market reached an advanced baseline in 2025 and is forecast to grow at an 11.48% CAGR through the 2026–2032 period, delivering material upside for organizations that align product roadmaps, capital plans and partnerships to the new packaging paradigms.
Maskless Lithography System For Semiconductor Packaging Market
Why 2026 is a Pivot Year
-
Acceleration of heterogeneous integration and chiplet architectures. The push to scale AI/HPC compute and to combine dissimilar process nodes is increasing demand for advanced packaging methods — often requiring flexible, stitch‑free patterning on large substrates and rapid iteration cycles that photomask-driven flows struggle to support.
Maskless Lithography System For Semiconductor Packaging Market -
Operational constraints at scale. Die shift, substrate warpage and on-panel alignment challenges are redefining lithography requirements at the back end. Maskless systems that incorporate real‑time die‑shift compensation, warpage correction and high-resolution direct-write optics reduce integration risk and speed time‑to‑qualified-production.
Maskless Lithography System For Semiconductor Packaging Market -
Technology and sustainability dynamics. Solid‑state light sources and spatial light modulators (SLMs) lower routine maintenance and remove photomask inventories, improving both total cost of ownership and the environmental footprint of lithography operations.
-
Vendor momentum and productization. Leading equipment suppliers have moved from prototype demonstrations to order-taking and trade-show rollouts of HVM-capable platforms, signaling mainstream readiness and making 2026 the logical year for capacity pilots and vendor selection.
How This Report Supports 2026 Decision-Making
Corporate leaders need more than forecasts — they need executable playbooks. Our report is designed as a decision‑centric toolkit that distills market dynamics into operational choices. Key deliverables include:
-
Macro market sizing and growth scenarios that quantify opportunity windows and sensitivity to adoption catalysts.
-
Adoption roadmaps by manufacturing model (in‑house vs. outsourced vs. shared fab), showing when maskless makes economic sense for pilot, mid‑volume and high‑volume runs.
-
Total Cost of Ownership (TCO) and return‑on‑investment (ROI) models for maskless vs mask‑based flows, including an equipment lifecycle cost framework and throughput escalation paths.
-
Use‑case playbooks that map technology choices to packaging formats (wafer‑level, panel‑level, 2.5D/3D integration), qualification milestones and expected yield impact.
-
Vendor benchmarking and procurement checklists that translate technical specs into procurement scorecards and acceptance test plans.
-
Go‑to‑market and partnerships blueprint for equipment makers, tool integrators and service providers — covering channel models, service offerings, and co‑investment structures.
-
Risk matrices covering supply‑chain geopolitics, export controls, component sourcing (SLMs, solid‑state lasers), and mitigation options like multi‑sourcing and localized service footprints.
We intentionally surface strategic insights and operational tools in this release while reserving the granular segment tables and regional/application breakdowns for the full report. That design helps executives focus on decisions rather than chasing fragmentary numbers in a public brief.
Competitive Landscape — Who Matters in 2026
The maskless lithography vendor ecosystem is heterogeneous: a mix of specialized EU/Japanese optics builders, large systems houses expanding into direct-write technologies, and regional entrants focusing on price‑performance tradeoffs. Market concentration is already meaningful: the top three vendors control a majority share of reported deployments, and the top five consolidate an even larger portion of commercial activity — a structure that rewards early qualification and supplier partnerships.
-
Heidelberg Instruments (Germany) : Strong in mid‑to‑high volume wafer‑level packaging with a product family that emphasizes rapid design customization, die shift compensation and micron‑class resolution. Their positioning is operationally focused on reducing photomask dependency while enabling high‑mix production.
-
EV Group (EVG, Austria) : A leader in maskless exposure platforms engineered for high throughput and stitch‑free full‑wafer patterning. EVG’s emphasis on heterogeneous integration and probe‑card applications, coupled with hybrid bonding expertise, positions it as a center‑of‑gravity for chiplet and 3D packaging workflows.
-
Nikon (Japan) : Transitioning projection expertise into maskless digital lithography with SLM‑based systems that target large advanced‑packaging substrates. Nikon’s recent commercialization steps are notable for achieving sub‑micron L/S performance in a production‑oriented form factor.
-
SCREEN Holdings and SÜSS MicroTec (Japan & Germany) : Both bring deep know‑how in laser direct imaging and projection lithography tailored to substrate and panel handling. Their strengths are in throughput scaling and tool robustness for telecom and IoT infrastructure volumes.
-
In‑Vision, Applied Materials (with partners), and emerging regional players : In‑Vision’s digital light engines and Applied Materials’ collaborations on Digital Lithography Technology point to a trend of ecosystem plays — combining optics, motion systems and materials engineering. Local suppliers in China and elsewhere are closing technical gaps quickly, particularly for regional OSAT demand.
Recent vendor milestones underscore an industry in transition: leading suppliers moved from demonstrations to commercial availability and trade‑show ramp-ups over the 2025–2026 period, indicating a shift from lab validation to factory adoption. For procurement teams, vendor roadmaps, service commitments and ecosystem compatibility (metrology, patterning software, post‑process integration) are as important as nominal resolution numbers.
Strategic Recommendations — Priorities for 2026
-
Initiate time‑boxed pilots now: Run application‑specific pilots that include warpage/die‑shift stress tests, throughput ramp simulations and metrology integration. Successful pilots will shorten procurement cycles in 2027.
-
Score vendors on operational fit, not just specs: Emphasize service SLAs, software/toolchain openness, retrofit options and local support capabilities when selecting vendors for qualification.
-
Design procurement for optionality: Consider mixed fleets (maskless + mask‑based) during the transition to preserve yield stability while capturing flexibility benefits.
-
Invest in metrology and process controls: The value of maskless systems is unlocked with closed‑loop alignment, inline metrology and advanced compensation algorithms. Budget for these enablers in the qualification phase.
-
Integrate geopolitical and supply‑chain scenarios into capital plans: Given export dynamics and concentrated IP around key SLM and optics components, plan for diversified sourcing and service partnerships across regions.
-
Pursue ecosystem partnerships: For tool vendors and integrators, co‑development agreements with materials and metrology suppliers accelerate qualification and create defensible customer lock‑in.
What Leaders Will Do Differently in 2026
Executives who convert the maskless opportunity into competitive advantage will do three things differently: (1) they will treat advanced packaging lithography as a systems integration problem rather than a point tool decision; (2) they will align R&D and manufacturing KPIs around time‑to‑qualified‑production, not only throughput; and (3) they will use staged procurement tied to validated yield milestones to manage CAPEX risk while capturing the first‑mover benefits of design flexibility and faster NPI cycles.
About This Release and How to Use the Full Report
This briefing highlights the strategic choices and vendor dynamics that matter for 2026. The complete PW Consulting research package contains the full datasets, scenario modeling, supplier scorecards, procurement templates, and detailed segment economics that underpin these recommendations. To preserve the report’s tactical value for paying subscribers and to support confidential procurement processes, granular regional and application split tables are available only in the full deliverable.
Why PW Consulting
PW Consulting combines senior strategy advisory, semiconductor manufacturing domain expertise, and hands‑on equipment qualification experience. Our clients use these reports not just to justify capex, but to structure procurement, negotiate service contracts, and design manufacturing trials that convert experimental tech into sustained production advantage.
For executives preparing 2026 budgets and 2027 capacity plans: maskless lithography is no longer optional. It is a design and manufacturing lever. The full PW Consulting report provides the actionable detail that separates opportunistic pilots from strategic adoption — please contact our industry team to access the complete research and the proprietary data packages that support supplier selection and deployment planning.
For detailed analysis of this topic, please visit the official page: Maskless Lithography System For Semiconductor Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com