

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Angiography Contrast Media Market to Reach USD 3,248.18 Million by 2032, Expanding at a 5.82% CAGR

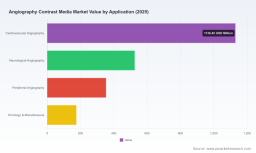
Angiography Contrast Media Market: Strategic Insights for 2026 Decisions — PW Consulting Preview
PW Consulting’s latest market study on the Angiography Contrast Media Market (base year 2025; forecast 2026–2032) delivers a focused strategic blueprint for executive teams, corporate development groups, and healthcare investors preparing for near-term action. This preview highlights the report’s analytical backbone — including the forecast trajectory and macro dynamics — while preserving the proprietary granular segmentation that drives transactional decisions. The full report is required to unlock detailed subsegment breakdowns, regional allocation scenarios, and vendor-level share tables.
Angiography Contrast Media Market
Executive summary: why this matters in 2026
The global angiography contrast media market is positioned for steady recovery and growth as procedural volumes normalize, imaging platform upgrades accelerate, and regulatory clarity on agent safety improves. Our model — grounded in five years of historical observation (2020–2025) and forward projections through 2032 — shows mid-single-digit CAGR expansion (5.82% CAGR over the forecast window) with a total market size that moves from a base in 2025 to an expanded opportunity by the end of 2032. For 2026 specifically, the market is forecast to resume expansion following the 2024–2025 volatility, creating a timely window for strategic moves across product, access, and partner ecosystems.
Angiography Contrast Media Market
What the report delivers (practically)
- Actionable demand forecasting: scenario-based models incorporating procedure-mix shifts, post-pandemic recovery curves, and capital refresh cycles for CT and angiography suites.
- Go-to-market playbooks: customer segmentation, hospitals vs. outpatient imaging center scorecards, tender and distributor strategies, and channel economics optimized for 2026 procurement dynamics.
- Regulatory and reimbursement trackers: rolling updates on FDA clearances, ACR guidance, and 2026 CPT/CMS changes — mapped to product risk profiles and billing levers.
- Pricing and margin benchmarks: manufacturer and private-label mix scenarios, contract negotiation templates, and sensitivity analyses for raw-material and logistics stress.
- M&A and partnership heat maps: valuation ranges for targets, integration risk matrices, and buy-versus-build decision frameworks focused on contrast formulation, injectors, and contrast management systems.
- Supply chain resilience playbook: alternative sourcing, inventory optimization, and contingency planning for manufacturing disruptions and cold-chain logistics.
Market trajectory: the macro view
Key macro outputs from the study are clear and directionally decisive. The market showed year-on-year fluctuations through 2020–2025 driven by pandemic impacts and elective procedural rebounds. By 2026 the market is forecast to re-establish growth momentum, and by 2032 the cumulative expansion reflects technology-enabled uptake in image-guided interventions and incremental adoption in emerging care settings.
Angiography Contrast Media Market
These broad figures underpin three practical conclusions for 2026 decision-making: (1) capacity and supply investments should be prioritized for mid-term payoffs rather than short-term volume spikes; (2) product portfolios that emphasize safety, label clarity, and compatibility with injector platforms will capture disproportionate share; and (3) strategic partners in device contrast-injection ecosystems represent levered routes to accelerate clinical adoption without linear commercial spend growth.
Competitive landscape — what to watch
The market remains industry-consolidated, with the top manufacturers holding a substantial share of sold value and clinical mindshare. Market concentration metrics indicate a high level of consolidation among leading suppliers, making competitor moves materially impactful to pricing and access dynamics.
- GE HealthCare — A diversified portfolio player with strong iodinated contrast franchises and integrated imaging platforms. Their cross-sell opportunities into installed imaging bases and service contracts make them a critical partner or competitor in bundled supply negotiations.
- Bayer AG — A global comparator with robust product lines and recent regulatory wins enabling enhanced compatibility with major injection systems. Their regulatory success expands clinical use cases and can shift procurement preferences in favor of validated system-agent pairings.
- Bracco Imaging — A specialist in iodinated X-ray contrast agents with deep clinical relationships in cardiovascular imaging, delivering trusted formulations and clinician familiarity that dampen price elasticity in certain channels.
- Guerbet — Known for targeted contrast portfolios and lifecycle management of diagnostic agents; their focused R&D can accelerate niche innovations relevant to interventional radiology.
- Lantheus, ulrich, Taejoon, J.B. Chemicals, Sanochemia — Collectively representing manufacturers and systems providers across North America, Europe, and Asia. Their strategies range from product breadth and generics playbooks to contrast management systems and high-pressure injectors that alter total cost of ownership.
Competitive implications for 2026: expect increased platform-level competition (contrast + injector compatibility), selective vertical partnerships between contrast makers and imaging OEMs, and continued tendering sophistication by large hospital systems seeking bundled solutions.
Regulatory and reimbursement environment — implications for strategy
- Safety and labeling: Regulatory communications and professional society guidance continue to influence product preference (e.g., preferences for agents with more favorable renal-safety profiles in high-risk patients). Manufacturers should prioritize robust safety dossiers, post-market surveillance commitments, and targeted clinician education programs to preserve and grow market share.
- Reimbursement coding updates: CMS and CPT changes for diagnostic angiography in 2026 create both risk and opportunity. While core angiography pathways remain reimbursable, bundled coding and evolving outpatient payment models will force suppliers to present clear value propositions tied to procedural efficiency and reduced downstream costs.
- 510(k) and device compatibility approvals: Recent clearances tied to injector systems and platform-specific compatibility materially change procurement conversations. Suppliers that secure validated pairings will find differentiated access points into radiology and cardiology departments.
Strategic imperatives for 2026
Translate the market trajectory into executable priorities:
- Prioritize platform compatibility wins: Accelerate regulatory programs that validate compatibility between contrast agents and leading injector platforms. These are high-impact, relatively low-capex routes to procurement preference.
- Value-based contracting pilots: Align with large IDNs and imaging chains to pilot bundled contrast + service offerings tied to throughput metrics and adverse-event reduction targets.
- Selective capacity expansion: De-risk investments through tolling or contract manufacturing agreements, particularly where raw material or fill-finish bottlenecks persist.
- M&A focus areas: Small-to-mid sized targets with complementary formulation IP, regional manufacturing footprints, or contrast-management hardware/software capabilities are attractive to accelerate market access and margin improvement.
- Clinical differentiation: Invest in head-to-head or registry studies that demonstrate safety or workflow improvements versus incumbents — these studies are decisive in shifting hospital formulary decisions over 12–24 months.
Risk matrix and contingencies
- Regulatory shocks: New safety advisories or labeling changes can compress demand in affected patient cohorts; maintain flexible pricing levers and alternative product routing strategies.
- Reimbursement compression: Hospital and outpatient payment shifts favor efficient imaging delivery; prepare margin-protection tactics including SKU rationalization and service upsells.
- Supply chain disruption: Prioritize multi-sourcing, safety-stock modeling, and early-warning procurement indicators to prevent costly stockouts during peak procedural months.
How to use this preview and next steps
This release is a strategic “trailer”: it shares the market’s directional forecast and high-value implications while intentionally withholding the granular regional, application, and product-split matrices that power procurement models and M&A valuation. The complete PW Consulting Angiography Contrast Media Market report contains detailed subsegment revenue tables, regional allocation scenarios, buyer scorecards, supplier-level contract comparators, and downloadable financial models suitable for transaction diligence and three-way sensitivity analyses.
If you are a c-suite leader, corporate development executive, or private equity investor preparing 2026 budgets, the full report will provide:
- Segment-level revenue and unit forecasts with scenario toggles for volume, price, and mix.
- Vendor share tracking, CR3/CR5 trend analyses, and scenario-based share-shift models.
- Negotiation-ready supplier scorecards and model agreements for bundling contrast agents with injector systems and service contracts.
Final note — the strategic opportunity
The angiography contrast media market in 2026 represents a balance of resilience and transition. Established players retain strong positions, but technological interoperability, regulatory validation, and value-based contracting will create openings for fast-moving challengers and well-capitalized consolidators. PW Consulting’s full report equips decision-makers with the quantitative fidelity and qualitative playbooks needed to convert macro growth into boardroom wins. For access to the proprietary segmentation tables, vendor scorecards, and downloadable financial models that informed the recommendations in this preview, please consult the full market report.
For detailed analysis of this topic, please visit the official page: Angiography Contrast Media Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com