

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
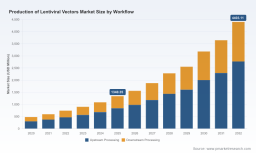
PW Consulting: Production of Lentiviral Vectors Market to Hit USD 4,403.11 Million by 2032 with 18.52% CAGR — Cell Therapy and Upstream Processing Lead 2025 Landscape (USD 1,340.35 Million)

Production of Lentiviral Vectors Market: Strategic Outlook for 2026 — PW Consulting Intelligence Brief
As cell and gene therapies move from clinical promise to commercial reality, the production of lentiviral vectors (LVVs) has emerged as a strategic choke point for developers, CDMOs and investors. PW Consulting’s new Production of Lentiviral Vectors Market report (base year 2025) synthesizes capacity, cost, regulatory and competitive dynamics into a practical playbook for decisions that must be made in 2026. This briefing highlights the report’s strategic value — presenting actionable insights while reserving detailed subsegment numbers for subscribers.
Production Of Lentiviral Vectors Market
Executive snapshot: growth, scale and what it means for 2026
- The market is on a steep growth trajectory: the industry-wide revenue baseline reached a material scale by 2025 and is forecast to expand robustly through the 2026–2032 period at an 18.52% compound annual growth rate (CAGR).
- This trajectory reflects the accelerating transition of advanced therapies (notably CAR‑T, gene-modification programs and in vivo gene therapies) into later clinical phases and initial commercial launches — creating urgent demand for GMP-compliant LVV capacity and industrialized manufacturing processes.
- For corporate decision-makers, the implication is simple: 2026 is the inflection year for capacity commitments, capital deployment and strategic partnerships. Decisions taken now will materially shape competitive position and supply security through the early commercialization window.
Market dynamics driving 2026 strategies
- Demand concentration and capacity stress: Rapid program progression and several late-stage readouts have compressed lead times for vector supply. While a number of global CDMOs and specialist players supply the market, the leading providers capture a meaningful share of capacity — a dynamic that magnifies the commercial value of every additional qualified manufacturing line.
- Raw material economics: GMP-grade plasmids remain a large and volatile component of production cost. Recent peer-reviewed analyses show plasmids account for a very significant portion of raw material spend in transient transfection workflows, which still predominate across the industry. This cost profile is driving two parallel responses: near-term hedging and secondary sourcing of plasmid supply, and mid-term investments in stable producer cell lines that can materially reduce plasmid dependence.
- Regulatory evolution: In 2026 regulators have signalled conditional flexibility to support innovation in cell and gene therapy manufacturing, particularly for early-phase trials. That said, analytical rigor remains non-negotiable: methods must be demonstrated fit-for-purpose at IND initiation and progressively qualified for later phases. The net effect is an opportunity window — accelerated entry is possible, but only with a clear, risk-controlled analytics and CMC plan.
- Workflow innovation: Upstream/transient transfection remains the industry’s workhorse, but a growing number of programs and CDMOs are piloting stable cell line approaches, perfusion-capable upstream platforms and single-use production suites to balance speed, yield and regulatory consistency.
Competitive landscape: how the leading players are shaping the market
The LVV ecosystem combines global life‑science CDMOs, specialized vector manufacturers and vertically integrated advanced‑therapy service providers. Several strategic moves in 2024–2026 illustrate two converging trends: capacity expansion within established CDMOs, and focused scale-up by specialized LVV providers.
Production Of Lentiviral Vectors Market
- Major CDMOs are consolidating integrated offerings. Large service providers with broad biologics portfolios have accelerated investments in gene‑therapy grade facilities and end‑to‑end capabilities (process development, GMP production, fill‑finish and analytics). These firms are attractive partners for sponsors seeking single‑vendor risk reduction and global supply architectures.
- Specialist vector CDMOs and independent manufacturers are differentiating through LVV depth: dedicated cleanrooms, LVV‑focused process toolsets and regulatory experience with CAR‑T and gene‑modified products. These vendors compete on speed-to-IND, platform repeatability and targeted service levels for clinical and early commercial volumes.
- Recent notable developments (high‑level): strategic commercial supply agreements, acquisitions of commercial‑scale vector sites, new large flagship facilities opening, and academic‑industry collaborations to extend GMP capacity for CAR‑T vectors. These moves materially reduce near-term capacity tightness in some corridors, while raising barriers to entry for new challengers who cannot match validated GMP infrastructure quickly.
What PW Consulting’s competitive analysis reveals
Our cross‑company assessment identifies four strategic archetypes and the tactical choices that define success in 2026:
Production Of Lentiviral Vectors Market
- Integrated global CDMOs (scale + breadth): Firms that combine large‑scale manufacturing footprints with process development expertise can lock in marquee programs and support multinational launches. Their challenge is operational agility — keeping specialized LVV yields and analytics as a centre of excellence amid broader biologics operations.
- Dedicated LVV specialists (depth + speed): Providers focused exclusively on lentiviral and retroviral production offer rapid qualification timelines and LVV‑specific best practices. Their growth path depends on replicating capacity while maintaining strict GMP quality without dilution of specialized talent.
- New entrants with greenfield capacity: Recent facility openings create incremental supply but require validated processes, regulatory approvals and client onboarding to convert theoretical capacity into commercial revenue. The first 12–18 months post‑qualification are commercially critical.
- Hybrid players (platform + partnerships): Organizations combining in‑house platform technologies (stable cell lines, process intensification) with external collaborations can de‑risk supply and accelerate scale. Their edge in 2026 will hinge on demonstrable cost advantages and validated comparability data.
What the report contains — practical intelligence for 2026 decisions
PW Consulting’s report is structured to be executable. It blends quantitative forecasting with operational assessments and strategy tools that executives can use immediately:
- High‑granularity market forecast (2026–2032) with scenario modelling that quantifies demand by clinical phase, scale (clinical vs commercial), and adoption curves under conservative, base and accelerated scenarios.
- Capacity and utilisation mapping across the major providers, with lead time estimates for qualification and scale‑out — enabling procurement and business‑development teams to model supplier risk and timing.
- Cost‑build frameworks for upstream and downstream workflows, highlighting the drivers of cost per dose at different scales and the sensitivity of economics to plasmid pricing, yield improvements, and process intensification.
- Regulatory and analytics playbook that translates recent FDA guidance and fit‑for‑purpose testing expectations into CMC checklists for IND and later‑phase submissions.
- Due‑diligence templates for M&A, site acquisition and partnership evaluations — including a checklist for operational readiness, technology transfer risk and commercial ramp timelines.
- Vendor scorecards and decision matrices based on technical fit, geographic footprint, scale readiness and regulatory track record — designed for rapid supplier short‑listing.
Strategic recommendations for 2026
- For sponsors with mid‑late stage programs: secure multi‑sourced capacity now. Execute contingent supply agreements or optioned capacity with at least one incumbent CDMO and one specialist LVV manufacturer to balance speed and redundancy.
- For CDMOs: invest selectively in LVV‑specific infrastructure (dedicated cleanrooms, analytics labs and plasmid supply partnerships) rather than generic biologics capacity. Demonstrable technical differentiation — validated stable production platforms or superior analytical packages — will earn pricing power.
- For investors and corporate development teams: prioritise assets that shorten time‑to‑first‑dose and reduce upstream plasmid dependency. Near‑term value creation will come from assets that have cleared GMP qualification and initial commercial supply agreements.
- For policymakers and regulatory stakeholders: balance accelerated access with methodical CMC requirements. Our modelling shows that flexible early‑phase controls can expand patient access, but only if paired with clear milestones for analytics qualification and comparability evidence before broad commercialisation.
Why this report is indispensable for 2026 planning
Decision‑makers face a constrained set of tactical levers: secure capacity, de‑risk raw materials, industrialise processes, and align regulatory strategy to program timelines. PW Consulting’s report translates market growth (double‑digit CAGR through the forecast horizon), supplier moves, regulatory shifts and cost structures into prioritised actions. It does so without academic abstraction — every chapter is mapped to a decision-maker question: should I commit capital, sign a supply agreement, pivot to stable lines, or partner with an integrated CDMO?
Next steps — obtain the full intelligence
This briefing intentionally omits the granular subsegment tables and supplier-level revenue splits that underpin our scenario models. Those datasets — including capacity-by-site dashboards, per-dose cost sensitivity matrices and supplier scorecards — are available exclusively in the full Production of Lentiviral Vectors Market report. For companies evaluating 2026 investments, partnerships or procurement strategies, the report is the most time‑efficient way to convert market signals into defensible commitments.
Contact PW Consulting to access the full report, the underlying datasets and a tailored briefing session that maps the findings to your portfolio or pipeline priorities for 2026.
For detailed analysis of this topic, please visit the official page: Production Of Lentiviral Vectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com