

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ready-to-Eat Broth Market Valued at USD 3,450.0 Million in 2025, Poised to Reach USD 4,586.0 Million by 2032 at a 4.15% CAGR

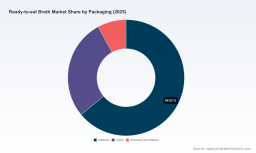
Ready To Eat Broth Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
Executive Snapshot
PW Consulting’s latest Ready To Eat Broth Market brief — the practical intelligence layer of our full market report — crystallizes why 2026 is a pivotal year for CPG leaders, private equity, and foodservice operators. The category has demonstrated steady resilience: global revenues rose from USD 2,810.2 million in 2020 to USD 3,450.0 million in 2025, and our forecast scenarios point to further expansion to roughly USD 4,586.0 million by 2032, representing a compound annual growth rate of 4.15% across the forecast window. For executives planning portfolios, product roadmaps, supply chains and retail strategies in 2026, these macro parameters define the playing field — but the competitive advantage lies in the tactical moves informed by the tactical, operational sections of our report.
Ready To Eat Broth Market
Why 2026 Matters: Convergence of Demand, Input Cost Signals and Regulation
-
Consumer demand is bifurcating between convenience-driven mainstream broths and value-added wellness plays (organic, bone-broth, functional flavors). This creates parallel growth lanes that require distinct go-to-market mechanics rather than a one-size-fits-all approach.
Ready To Eat Broth Market -
Input cost dynamics are increasingly product-specific. Expanding chicken supplies are expected to keep broiler pricing under downward pressure in early 2026, while beef wholesale prices are projected to rise — a factor that will compress margins on beef-based SKUs unless mitigated via sourcing or pricing strategies. Even modest poultry price upticks are sufficient to impact procurement strategies for high-volume players.
Ready To Eat Broth Market -
Regulatory headwinds — notably proposed FDA front-of-package nutrition labeling and ongoing Nutrition Facts requirements for serving sizes and nutrient declarations — will mechanically reshape product formulation and pack communication. Brands that preemptively invest in low-sodium reformulation, transparent front-of-pack positioning and nutrition-forward claims will avoid downstream promotional dislocations and trade friction.
Competitive Dynamics — What the Leaderboard Is Telling Us
The Ready To Eat Broth category sits at the intersection of large CPG incumbents, specialized premium operators, and agile natural-brand challengers. From a strategic standpoint, the competitive landscape can be summarized along capability vectors: scale & channel access, formulation & ingredient sourcing, premiumization & premium-margin execution, and speed-to-market for innovation.
-
Incumbent scale players (Household names with broad chilled/shelf-stable portfolios) bring distribution heft and co-packer leverage. Their advantages include shelf-space negotiation power with major retailers and the ability to absorb short-term input volatility through portfolio optimization. Expect continued platform extensions from these players into flavor variants and health-forward sub-brands as a tactic to defend shelf relevance.
-
Specialist premium operators (brands with clear provenance, organic positioning, or functional bone-broth credentials) are monetizing a willingness-to-pay among wellness consumers. Their playbook centers on ingredient story, direct-to-consumer economics, and B2B foodservice partnerships for margin stability.
-
Private-label and value-focused operators will continue leveraging cost advantage and pack optimization, especially in bulk and foodservice channels. Yet their success will hinge on meeting evolving labeling rules and consumer perception on health — an area where low-sodium and clean-label claims can complicate the value equation.
Recent Signals of Innovation and Market Activity
-
Product innovation continues to be a primary battleground: recent new launches include no-salt-added organic SKUs and flavor-line extensions that target beverage-style sipping broths and ethnic/spicy profiles. These introductions signal manufacturers’ efforts to capture both health-conscious consumers and those seeking novel taste experiences.
-
Companies are increasingly testing cross-channel models — leveraging e-commerce DTC to validate premium SKUs before wider distribution — lowering launch risk and sharpening merchandising briefs for retail buyers.
Operational Playbook: Eight Strategic Moves for 2026
For executives who must translate market potential into 2026 action, our brief synthesizes eight priority moves backed by scenario-tested analyses in the full report.
-
Prioritize SKU rationalization & margin mapping: Identify high-velocity SKUs that justify incremental marketing and low-velocity SKUs that should be consolidated or reformulated to reduce complexity and free merchandising dollars.
-
Formulate dual sourcing strategies for proteins: Hedge beef-exposed SKUs with alternate formulations or forward-contracting to blunt the projected beef-price pressure on margins.
-
Invest in low-sodium reformulation and pre-emptive label updates: This reduces trade risk from front-of-package labeling proposals and positions products favorably with health-driven retailers.
-
Layer premium DTC testing before national rollouts: Use direct channels to validate premium flavors and packaging formats, capturing consumer feedback and optimizing price elasticity before committing large shelf investments.
-
Accelerate carton and shelf-stable innovations: Packaging winners will be those that combine convenience, sustainability narratives and cost efficiency — critical within retailers’ sustainability scoring frameworks.
-
Deploy a tactical promotional calendar tied to seasonality and wellness moments: Broth demand shows seasonality and occasion-driven spikes; aligning promotions to those windows maximizes ROI on trade spend.
-
Run SKU-level profitability stress tests for private-label contracts: Foodservice and retail buyers will continue to pressure private-label costs; understanding break-evens prevents erosive contracts.
-
Build an M&A watchlist combining scale gaps and capability add-ons: Targets should be prioritized by channel access, ingredient supply integration, and unique IP (e.g., proprietary bone-broth processes or direct farmer relationships).
What the Full Report Contains (Practical, Executable Tools)
Our market brief is an executive-oriented distillation. The full PW Consulting Ready To Eat Broth Market report delivers operational intelligence and decision-grade assets, including:
-
Granular historical and forecast market models (by product type, pack format and region) with scenario toggles to test price shocks and regulatory impacts.
-
SKU prioritization matrices and retailer-ready merchandising playbooks to guide assortment and promotional planning.
-
Procurement stress-tests and cost-sensitivity dashboards linking protein price scenarios to SKU-level margins.
-
Regulatory readiness checklist aligned to the FDA’s proposed front-of-package labeling framework and updated Nutrition Facts requirements, with templated label language and reformulation pathways.
-
Competitive benchmarking and M&A screening models scoring acquisition targets on integration cost, revenue uplift potential and supply-chain synergies.
-
Commercial launch playbooks for premium and mass tiers — including DTC pilots, retailer negotiation scripts, and multi-channel pricing ladders.
How Executives Should Use This Intelligence in 2026
Decision-makers face a strategic choice: treat 2026 as a year to defend existing positions through cost and label management, or use it to accelerate share gains via innovation and disciplined distribution expansion. The economics of the category — steady market growth at a mid-single-digit CAGR and clear pockets of premium opportunity — mean that both routes can be profitable. However, the winning companies will be those who marry rigorous SKU economics and procurement hedging with purposeful brand differentiation on health and provenance.
Final Takeaway and Next Steps
PW Consulting’s Ready To Eat Broth Market brief gives leaders the evidence-based scaffolding to make those calls in 2026: where to invest, which risks to hedge, and how to structure M&A and commercial plays to protect margin and accelerate growth. This article surfaces the strategic contours and operational levers; the complete datasets, segment-level modeling and executable templates are reserved for the full report.
For firms that need to convert these insights into a 90-day action plan or a three-year portfolio strategy, our analysts are available to provide bespoke scenario runs, workshop facilitation, and an implementation roadmap. Access to the full intelligence package will enable you to move from market awareness to market advantage.
For detailed analysis of this topic, please visit the official page: Ready To Eat Broth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com