

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Silicone in Electric Vehicles Market Set to Skyrocket at a 21.5% CAGR Through 2032

Silicone in Electric Vehicles Market: Strategic Preview for 2026 — PW Consulting
Executive summary
As electric vehicle (EV) architectures accelerate in complexity, silicones have transitioned from niche auxiliary materials to mission-critical system components — governing thermal management, electrical insulation, sealing and structural resilience across batteries, power electronics, motors and charging infrastructure. PW Consulting’s new market intelligence places the global silicone-in-EV market on a steep growth trajectory: from a multi‑billion USD industry in the mid‑2020s to a substantially larger market by the end of the decade, underpinned by a robust compound annual growth rate through the forecast window. For OEMs, Tier‑1 suppliers, material producers and private investors planning 2026 capital allocation or product roadmaps, the report delivers the actionable intelligence required to convert rapid market expansion into durable competitive advantage.
Silicone In Electric Vehicles Market
Why 2026 is a pivotal year for silicone strategies
-
Regulatory inflection: Enforcement of advanced battery safety standards has elevated flame-retardant and durable materials to mandatory status for many markets. This regulatory push accelerates adoption cycles for silicone-based encapsulants and insulators that meet new safety thresholds.
Silicone In Electric Vehicles Market -
Demand pull from electrification: Rising global EV deployment — driven by consumer adoption and fleet electrification — is creating outsized demand for silicone thermal management and protective materials. This pull is concentrated where battery capacity and power density are increasing fastest, creating strategic sourcing pressure points.
Silicone In Electric Vehicles Market -
Supply-side volatility: Recent feedstock and pricing movements have meaningfully affected supplier margins and procurement plans. Materials cost fluctuations have created both near-term procurement risks and longer-term incentives for vertical integration or supply diversification.
-
Technology convergence: New inverter topologies, higher-density batteries and fast‑charging infrastructure are changing the functional requirements for silicone formulations (e.g., thermal conductivity, electrical stability, adhesion under thermal cycling), opening windows for differentiated product leadership.
What PW Consulting’s report delivers — practical intelligence for 2026 decisions
This is not a conceptual briefing. PW Consulting’s Silicone in EVs Market study is built for decision-makers who require both strategic context and transactional detail. The report includes:
-
Comprehensive market sizing and an audited forecast model covering 2026–2032 with an explicit growth trajectory and scenario sensitivity for key macro drivers. The base-year analysis also reflects historic dynamics (2020–2025) to surface durable trends versus transitory shocks.
-
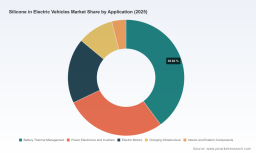
Segment-level analysis across product families (elastomers, gels, resins, fluids, adhesives/sealants) and application domains (battery thermal systems, power electronics, motors, charging infrastructure, vehicle interiors/exteriors). Note: the press summary intentionally omits detailed split tables; the full report includes downloadable segment tables and a modeling workbook.
-
Supply chain heat maps and supplier scorecards assessing technical capability, capacity, geographic footprint and dependence on critical feedstocks. These scorecards are calibrated to support procurement RFPs and supplier development programs.
-
Pricing and margin analysis tied to raw-material scenarios — including modeled impacts from polysiloxane feedstock movements and silicone rubber price variability — to guide hedging, contract length, and inventory strategies.
-
Competitive landscape: profiles and capability matrices for incumbent and emerging silicone suppliers, together with a quantified market concentration measure and M&A screening framework.
-
Technology & product roadmaps: evaluation of R&D pipelines, formulation trends, and validation protocols necessary for qualification with OEMs and Tier‑1s.
-
Go‑to‑market playbooks and partnership scenarios tailored to different buyer archetypes, from large OEMs to semiconductor‑grade inverter module manufacturers and fast‑charging network developers.
-
Case studies and procurement checklists — practical steps for integrating silicone priorities into supplier selection, testing regimens, and long‑lead component planning for 2026 program launches.
Competitive landscape — who matters and why
The silicone-in-EV value chain displays a mix of global chemical majors and specialized silicone houses. Market concentration suggests that a limited number of suppliers capture a meaningful share of the addressable market, creating both opportunity and competitive risk for buyers and investors.
-
Dow: A broadly diversified chemical platform with deep systems know‑how in encapsulants, thermal interface materials and sealants. Dow’s recent product showcases at international battery forums highlight a strategic emphasis on next‑generation battery encapsulation technologies and cross‑system solutions that integrate material performance with manufacturability.
-
Wacker Chemie: A leader in silicone gels and elastomers, focused on power electronics insulation and vibration‑damping solutions. Its launches indicate a push to translate formulation advantages into validated application packages for inverter and module manufacturers.
-
Momentive Performance Materials: Concentrated investments in thermal gap fillers and protective coatings, positioning the firm as a preferred supplier for inverter and high‑power modules where thermal paths and dielectric reliability are critical.
-
Shin‑Etsu Chemical: Longstanding expertise in silicone rubbers and fluids for seals, lubricants and motor systems. The company’s engineering support and global supply capability make it an important partner for volume vehicle platforms.
-
Elkem Silicones: Focuses on high‑performance silicones used in encapsulation and EMI shielding, offering differentiated formulations that address multi‑functional requirements in battery packs and powertrains.
-
KCC Corporation (Kumho Chemical): A regional and application-focused supplier with tailored solutions for thermal pads and encapsulants optimized for battery safety and heat dissipation.
Recent corporate moves — from trade show unveilings to targeted product launches — underscore suppliers’ dual strategies of product differentiation and OEM co-development. For 2026, buyers should anticipate intensified supplier engagement, as firms attempt to lock design wins and capacity commitments ahead of major EV program ramp-ups.
Market dynamics to watch in 2026
-
Raw-material and pricing pressure: 2025 saw notable upward movement in silicone rubber pricing and polysiloxane feedstock costs driven by demand and energy volatility. These dynamics will materially affect supplier margins and the economics of long‑tail contracts unless proactively managed.
-
Regulatory alignment: Battery safety regulations enacted in recent years are now operational in several major markets, effectively shortening qualification timelines for compliant materials and shifting buyer risk onto suppliers who can demonstrate certified flame-retardant performance.
-
End‑market pull: Rising EV sales volumes are translating into near‑term demand surges for thermal interface and encapsulation materials, particularly where higher energy density batteries and faster charging regimes are being deployed.
-
Consolidation & partnership: Given the investment required to scale high‑performance formulations and secure feedstock, expect continued collaborations, JV activity and selective M&A as pathways to market share capture and vertical resilience.
Actionable recommendations for 2026 planning
Based on scenario modeling and supplier due‑diligence, PW Consulting recommends the following priority actions for stakeholders making 2026 resource decisions:
-
Procurement: Move from spot buying to multi‑tier contracting for critical silicone families. Embed variable pricing clauses tied to validated feedstock indices and include capacity reservation for program launch windows.
-
R&D & Product Strategy: Prioritize compound development that simultaneously addresses flame retardancy, thermal conductivity and long‑term dielectric stability. Early co‑development with OEMs reduces qualification risk and shortens go‑to‑production timelines.
-
Supply security: Map and stress‑test the polysiloxane upstream chain. Consider strategic hedges, alternative chemistries and regional sourcing to mitigate energy‑driven cost shocks.
-
Commercial: For materials suppliers, tailor differentiated value propositions — including test data, certification support and logistics guarantees — to capture OEM design wins rather than competing solely on price.
-
M&A and partnerships: Screen targets that provide either feedstock integration, geographic manufacturing proximity to major OEM hubs, or proprietary formulations with proven EV qualifications.
-
Regulatory & compliance: Maintain an active regulatory monitoring function to ensure product portfolios meet evolving battery and vehicle safety standards; allocate budget to third‑party certification where required.
How PW Consulting validates its findings
The study synthesizes primary interviews with OEM engineers, Tier‑1 system integrators and materials R&D leads, combined with proprietary shipment and bill‑of‑materials tracing, supplier financial analysis and a bottom‑up build of capacity and qualification timelines. Our scenarios are stress‑tested across raw‑material price shocks, accelerated EV adoption paths and regulatory tightening to produce deterministic and probability‑weighted forecasts that inform capital planning and procurement strategies.
Next steps — where to get the full intelligence
This release is intended as a strategic preview. The full report contains the complete segmentation tables, an interactive forecast model (downloadable), supplier scorecards, supplier contact mapping and a 40‑page playbook for procurement and product teams preparing for 2026 program cycles. To obtain the full study, including the detailed segment economics and executable checklists, please visit PW Consulting’s report page and download the executive package. For bespoke briefings, scenario runs or supplier due‑diligence assignments aligned to your 2026 planning calendar, contact our Industrial Materials & Mobility practice.
PW Consulting — translating market complexity into practical decisions.
For detailed analysis of this topic, please visit the official page: Silicone In Electric Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com