

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Image Signal Processor and Vision Processor Market to Expand at a 9.16% CAGR During 2026–2032

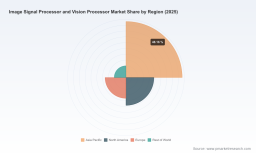
Image Signal Processor and Vision Processor Market: Strategic Imperatives for 2026 — PW Consulting Insights
As senior strategy advisors and lead industry analysts at PW Consulting, we present a focused briefing on our newly published Image Signal Processor (ISP) and Vision Processor Market research report. This executive preview frames the strategic value of the study for executive decisions in 2026 and explains why technology, supply‑chain and commercial leaders should re‑calibrate product roadmaps, procurement strategies, and partnership approaches now. The full report contains granular segmentation, vendor scorecards, and proprietary forecasts; this release purposefully surfaces high‑confidence implications while preserving detailed splits to drive readers to the full analysis.
Image Signal Processor And Vision Processor Market
Market at a Glance: Macro Trajectory and Competitive Structure
The ISP and vision processor market has transitioned from a midsized electronics component market into a core enabler of edge AI and system‑level differentiation. Our model — with 2025 as the base year — shows the market expanding at a compound annual growth rate (CAGR) of 9.16% over the forecast window. In absolute terms, the market moved from approximately USD 3,850 million in 2020 to USD 5,800 million in 2025, with our 2026 estimate at roughly USD 6,639 million and projections reaching just over USD 10,715 million by 2032 (USD Million basis).
Image Signal Processor And Vision Processor Market
Market concentration indicates meaningful scale advantages for leading vendors: the top three firms account for a substantial share of revenues and the top five capture a clear majority, consistent with a market where software ecosystems, IP portfolios, and manufacturing scale matter for design wins and long lead‑time components.
Image Signal Processor And Vision Processor Market
Why the Report Matters for 2026 Decisions
-
Timing product launches and architecture choices. Rapid improvements in ISP performance and the integration of on‑chip AI accelerators mean that platform selection today locks in capabilities for multiple product cycles. The report analyses technology roadmaps and cross‑vendor feature sets to help product teams choose architectures that balance near‑term cost with multi‑year differentiation.
-
Procurement and supply‑chain de‑risking. Semiconductor lead times shifted materially in early 2026 for certain IC families, and tariff and export‑control changes are introducing new layers of complexity for sourcing. Our supply‑chain scenario analysis and supplier risk matrix are designed to feed procurement playbooks and sourcing committees.
-
M&A and partnership targeting. With concentration concentrated at the top, mid‑market suppliers and IP players are attractive consolidation candidates. We provide a set of prioritized M&A targets, partnership archetypes, and valuation sensitivities grounded in vendor margins and addressable markets—critical for corporate development teams.
-
Regulatory and geopolitical contingency planning. New U.S. tariff measures and export control frameworks in early 2026 materially affect where and how high‑performance vision processors can be sold or manufactured. The report assesses these regulatory variables and provides playbooks for localization, licensing, and certification strategies.
What the Report Contains — Practical, Actionable Deliverables
-
Proprietary demand model and forecast (2026–2032) with sensitivity scenarios and upside/downside case studies.
-
Vendor landscape with qualitative and quantitative scorecards covering architecture (integrated ISPs vs. dedicated vision processors vs. sensor‑level ISPs), software ecosystems, go‑to‑market strength, customer concentration, roadmap alignment, and manufacturing risk.
-
Use‑case playbooks for priority end markets (consumer devices, automotive ADAS, security, industrial and medical robotics), focusing on system‑level tradeoffs, verification and validation, and certification timelines.
-
Supply‑chain heat maps and sourcing checklists that incorporate lead‑time projections, critical mineral exposure, and tariff/export risk overlays.
-
Commercial guidance: pricing dynamics, platform bundling strategies, and software monetization levers for semiconductor vendors and OEMs.
-
M&A and JV frameworks, including agenda templates for technology, IP, and customer‑base integration post‑transaction.
Competitive Landscape: Who to Watch and Why
The competitive set spans silicon vendors, image sensor makers, IP providers and system OEMs. Each player brings distinct strengths that shape their addressable opportunity and partnership appeal:
-
Ambarella Inc. (Santa Clara, CA) — Specializes in edge AI vision SoCs that integrate advanced ISPs with on‑chip AI accelerators. Its recent CV7 launch on a 4nm node demonstrates the strategic push toward multi‑stream 8K capabilities and high‑performance edge inference, aimed at security, automotive and robotics segments. Ambarella’s trajectory illustrates the advantage of combining high‑performance imaging pipelines with neural processing to capture premium design wins.
-
onsemi (Scottsdale, AZ) — Focused on dedicated ISP co‑processors for advanced CMOS sensors, with deep traction in automotive and industrial markets. The company’s revenue mix shows that automotive and industrial represent a substantial portion of ISP revenue for major suppliers, underscoring the importance of automotive certifications and long product life cycles.
-
Qualcomm Technologies (San Diego, CA) — Strong in integrated SoCs and vision intelligence platforms for consumer and IoT segments. Qualcomm’s ecosystem and channel reach make it a formidable partner for OEMs seeking rapid time‑to‑market with embedded AI vision functions.
-
NXP Semiconductors (Eindhoven, NL) — Offers processors with dual ISPs and an established automotive/industrial presence. NXP’s partner network and software stacks are key assets for system integrators building safety‑critical applications.
-
indie Semiconductor (Aliso Viejo, CA) — Targeted at automotive ADAS with vision processors that support multiple concurrent sensors at high aggregate throughput. Indie’s emphasis on low‑latency, multi‑sensor processing reflects the architectural requirements of surround‑view and driver monitoring systems.
-
OmniVision Technologies (Santa Clara, CA) — Produces companion ISP chips paired with sensors; valuable for OEMs seeking tightly integrated sensor‑plus‑ISP solutions for surround‑view and specialized video applications.
-
STMicroelectronics (Geneva, CH), Sony Semiconductor Solutions (Atsugi, JP), Texas Instruments (Dallas, TX), Chips&Media (Seoul, KR), Renesas Electronics (Tokyo, JP) — These firms cover a spectrum of strategies from sensor‑level intelligence to hardware ISP IP and MCU/MPU‑based vision platforms. Notably, IP vendors and sensor makers are accelerating software‑defined imaging approaches that can shift where value is captured in the stack.
Recent Technology and Industry Developments — Strategic Impacts
-
Full AI‑based ISP pipelines: The introduction of software‑defined, AI‑first ISPs enables real‑time video enhancement and reconfigurable imaging pipelines. This is a structural inflection for OEMs: software capability increasingly differentiates commodity silicon.
-
High‑performance edge SoCs: Advancements toward sub‑5nm process nodes with integrated neural accelerators enable multi‑stream 8K processing at the edge. These capabilities open new product categories but raise sourcing and IP challenges.
-
Geopolitical/regulatory shock vectors: New tariff measures and export‑control licensing regimes introduced in early 2026 alter the economics of cross‑border supply and may require firms to prioritize domestic manufacturing or to pursue exemptions and licensing pathways.
-
Supply pressure on lead times: Certain high‑performance IC families are experiencing extended lead times in the 30–42 week range in early 2026. This affects procurement cadence, buffer stocking, and qualification timelines.
Strategic Recommendations for 2026 — What Senior Leaders Should Do Now
-
Update product‑roadmap gating criteria to include software upgradability and neural acceleration headroom. Choose silicon that offers both current feature parity and future upgrade paths to support multi‑year hardware commitments.
-
Re‑negotiate sourcing and inventory policies to include risk premia for long‑lead devices and critical mineral exposure. Build multi‑sourcing strategies and qualify secondary suppliers earlier in development cycles.
-
Develop regulatory playbooks: map product SKUs against tariff and export‑control regimes and create alternative distribution and manufacturing footprints to preserve market access.
-
Invest in software differentiation: allocate roadmap resources to imaging and vision software that can be monetized and act as a margin buffer against silicon commoditization.
-
Pursue selective partnerships and M&A to acquire complementary IP (e.g., AI ISP pipelines, sensor integrations) and to accelerate time‑to‑market in safety‑critical automotive applications.
How PW Consulting Can Help
Our full Image Signal Processor and Vision Processor Market report contains the detailed regional and application splits, vendor scorecards, supply‑chain tables, and scenario workstreams that empower procurement, product, and corporate‑development teams to act in 2026. This preview has surfaced high‑confidence implications and recommended next steps; the complete study includes the underlying model (2026–2032), price and volume sensitivity analyses, and a prioritized action list tailored for OEMs, semiconductor vendors, and system integrators.
To preserve strategic advantage for our clients, this briefing intentionally omits segment‑level dollar splits and regional breakdowns that appear in the full document. For decision‑grade detail — including the vendor ranking matrix, M&A target list, and the downloadable financial model — please visit our report landing page or contact a PW Consulting advisor.
Final Thought
The ISP and vision processor space is moving from component market to systems‑level battleground. Executives who align silicon choices, software roadmaps, and supply‑chain strategies to the converging forces of AI integration, regulatory change, and industrial demand will convert near‑term complexity into durable advantage. Our report provides the map and operational toolset to make those choices with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Image Signal Processor And Vision Processor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com