

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: 4-Bromoanisole Market to Expand at a 4.52% CAGR, New Report Reveals

4-Bromoanisole Market Outlook 2026: A Strategic Playbook for Decision-Makers
As companies calibrate strategies for 2026 and beyond, granular intelligence on critical building blocks such as 4‑Bromoanisole is no longer optional. PW Consulting’s latest market research report synthesizes primary sourcing, regulatory developments, and commercial dynamics into an actionable playbook designed for procurement leaders, R&D chiefs, corporate development teams, and specialty-chemical investors. This article highlights the report’s strategic value — demonstrating the analytical depth you can expect — while intentionally withholding the full segmented datasets to encourage direct access to the complete study.
4 Bromoanisole Market
Market snapshot: steady growth with compound implications
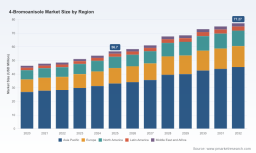
The 4‑Bromoanisole market has demonstrated resilient expansion through the early 2020s and enters 2026 from a position of measured momentum. Our base-year assessment (2025) places global market revenue at approximately USD 56.7 Million, with a compound annual growth rate projected at 4.52% through the 2026–2032 forecast horizon. By 2032, revenues are forecast to approach the high‑seventies million dollar range under our central scenario. This trajectory reflects a mix of steady demand in pharmaceutical intermediates, niche materials applications, and incremental uptakes in specialty syntheses.
4 Bromoanisole Market
While headline growth may appear modest, the market’s true strategic importance arises from supply concentration, feedstock sensitivity, and regulatory tightening — factors that can amplify price volatility and create asymmetric risks for exposed players.
4 Bromoanisole Market
Key dynamics shaping 2026 decisions
-
Supply‑side pressure and feedstock volatility — Recent disruptions in bromine supply and tighter availability of anisole derivatives have elevated upstream cost structures and shortened lead times. Even modest percentage changes in raw material pricing can materially affect margins for manufacturers and distributors given the commodity’s role as a core reagent.
-
Regulatory tightening — Chemical registration frameworks have begun to layer additional requirements around safety data for substances flagged under reproductive toxicity concerns. These compliance costs influence supplier qualification timelines, approvals for pharmaceutical APIs, and the pace at which new producers can enter regulated markets.
-
Channel segmentation and concentration — The supply landscape is bifurcated between lab‑pack, GMP‑oriented suppliers and bulk/custom synthesis players. Market concentration metrics indicate that a small group of suppliers captures a meaningful share of the market, creating both competitive opportunity for nimble entrants and supply risk for large consumers dependent on a narrow vendor base.
-
Trade policy and tariff stability — Current tariff structures for brominated anisoles remain a non‑trivial factor in cost modelling for cross‑border procurement. With tariffs and trade policy largely stable after recent reviews, buyers still face the legacy impact of these duties on landed cost calculations.
Strategic implications for 2026
For executives planning investments, sourcing strategies, or M&A activity in 2026, the following implications are critical:
-
Procurement must evolve from price-negotiation to risk orchestration. Tactics such as staged long‑term supply agreements with volume-flex clauses, dual‑sourcing for feedstocks, and indexed pricing models will be decisive in stabilizing input costs without surrendering upside on favorable market moves.
-
Vertical integration or strategic tolling arrangements are increasingly attractive for mid‑sized manufacturers whose margin sensitivity to feedstock swings is acute. Our scenario modelling shows selective IS/OT investments can shorten lead times and improve cost visibility, but require disciplined capex prioritization and feedstock hedging plans.
-
Regulatory readiness is a competitive differentiator. Companies that proactively invest in extended safety dossiers, robust analytical packages, and GMP documentation will accelerate pharmaceutical qualification cycles and access higher‑margin channels.
-
Portfolio managers should re‑examine product positioning. Given the market’s modest headline growth, the path to outperformance lies in specialization — higher‑purity grades, bespoke packaging and value‑added analytical support, or embedded services (e.g., building‑block libraries for drug discovery).
-
M&A and partnership opportunities center on capability gaps. Targets that provide capacity flexibility, GMP credentials, or localized supply in under‑served geographies will command premiums in 2026 transactions.
Competitive landscape: what the supplier map reveals
The market is serviced by a mix of global lab suppliers, specialty distributors, and custom synthesis houses. Our analysis profiles the commercial positioning and strategic vectors of the core suppliers active in this space:
-
Large laboratory suppliers (e.g., established life‑science brands) focus on lab‑grade supplies, small pack sizes, and fast delivery to R&D and pharmaceutical synthesis teams. Their strengths are brand trust, global logistics, and robust quality documentation; their challenge is competing on economics for larger industrial orders.
-
Specialty distributors and bulk providers serve industrial chemistry and fine chemical markets, offering broader packaging ranges and custom‑synthesis capabilities. They excel at operational flexibility and customer technical support but face margin pressure when upstream feedstock prices spike.
-
GMP‑focused manufacturers enable late‑stage pharmaceutical programs with the documentation and lot control required for regulatory filings. Their throughput is strategically valuable but constrained by higher compliance costs and longer qualification lead times.
PW Consulting’s proprietary concentration analysis shows that the top three suppliers control a significant share of the market, with the top five accounting for a majority. This degree of concentration creates both negotiation leverage for buyers with scale and exposure for organizations reliant on a limited supplier set.
Report deliverables: practical tools included
The full PW Consulting report goes beyond narrative to deliver a practical toolkit for 2026 decision-making. Key deliverables include:
-
Demand and revenue models with scenario elasticity: base, upside, and stress scenarios calibrated to input‑price shocks and regulatory outcomes.
-
Supplier scorecards and qualification templates that translate regulatory and analytical requirements into actionable vendor‑selection criteria.
-
Cost‑to‑serve and landed‑cost calculators that incorporate tariffs, freight, and feedstock pass‑through mechanics to model true procurement economics.
-
Regulatory impact maps and an RD/QA checklist for accelerating GMP qualification and reducing time‑to‑market for pharmaceutical intermediates.
-
Negotiation playbooks and contract language samples for long‑form supply agreements, including clauses to manage price escalation, force majeure, and quality disputes.
-
Target screening and M&A playbooks highlighting capability adjacencies, integration risks, and synergy realization timelines.
These outputs are engineered to be operational from day one: spreadsheet models with driver controls, templated supplier audits, and a prioritized implementation roadmap for the first 12 months.
How to use the intelligence in practice
-
Procurement teams: adopt the report’s risk matrix to reconfigure supplier tiers and implement hedging or indexation strategies aligned to your cost structure and contractual flexibility.
-
R&D leaders: leverage the GMP readiness checklist and supplier scorecards to streamline candidate qualification and reduce the typical regulatory friction that delays clinical timelines.
-
Corporate development: use the valuation cases and target shortlists to screen acquisitions that close strategic gaps in capacity, geographic presence, or regulatory credentials.
-
Operations: apply the landed‑cost calculators and scenario models to inform inventory policies, tolling partnerships, and make‑vs‑buy decisions under stress scenarios.
Why PW Consulting’s analysis matters for 2026
Two characteristics make this report indispensable for 2026 planning. First, it combines near‑term operational playbooks with mid‑cycle strategic scenarios; second, it integrates supply‑chain microphysics (feedstock pricing and capacity constraints) with regulatory and commercial realities (GMP timing and channel economics). Together, these perspectives enable leaders to convert market intelligence into defensible, executable strategies.
Our approach is intentionally pragmatic: rather than presenting static forecasts, we provide an adaptable toolkit that allows companies to stress‑test business plans across price shocks, supplier outages, and regulatory shifts — the exact permutations most likely to materialize in the coming 18–36 months.
Next steps and how to access the full study
This article outlines the strategic contours of the 4‑Bromoanisole market and previews the actionable outputs in our full study. To preserve the utility of the report as a commercial and operational asset, we have refrained from publishing detailed segmented tables, supplier share breakouts by region/application, and the full numerical scenario decks here. Those datasets and interactive models are included in the complete PW Consulting package.
For access to the full report — including the segment‑level demand model, supplier benchmarking spreadsheets, and the downloadable negotiation playbook — visit PW Consulting’s research portal or contact our industry team to arrange a briefing and license the report for your organization.
In a market where modest headline growth can mask concentrated supply risk and regulatory complexity, the right intelligence is the difference between vulnerability and strategic advantage. Our 4‑Bromoanisole market study is designed to help you capture that advantage in 2026.
For detailed analysis of this topic, please visit the official page: 4 Bromoanisole Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com