

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Fully Closed Ventilator Breathing Circuit Market to Reach USD 1.69 Billion by 2032 on a 5.22% CAGR

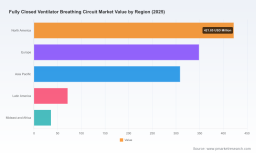
Fully Closed Ventilator Breathing Circuit Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
PW Consulting’s newest market research release on the Fully Closed Ventilator Breathing Circuit Market offers senior executives and investors an actionable blueprint for decision-making in 2026. Anchored on a robust base year (2025) and a detailed historical review (2020–2025), our forecast (2026–2032) models trajectory, disruption scenarios, and go-to-market playbooks aligned to a 5.22% compound annual growth rate (CAGR) during the forecast window. The market is projected to grow from an assessed 2025 value (USD Million denominated) to an estimated total in 2032 of USD 1,693.25 Million, with step-change increases already visible in the first year of the forecast.
Fully Closed Ventilator Breathing Circuit Market
Why this report matters for 2026 strategy
- Decision-ready sizing: We provide a transparent and reproducible market-sizing approach using demand drivers (clinical utilization, ventilator installed base, replacement cadence) and supply-side constraints (manufacturing capacity, regulatory clearances, raw materials) so leaders can stress-test capital allocation scenarios for 2026.
- Regulatory and reimbursement clarity: The study synthesizes the regulatory landscape (including 21 CFR classifications and ISO connector/performance expectations) and the nuanced reimbursement environment that affects procurement economics for hospital systems and home-care providers.
- Competitive playbooks: Beyond vendor lists, the report maps competitive advantage by technology, channel, and customer segment — essential for M&A due diligence, product roadmap prioritization, and targeted commercial investments.
- Operational levers for near-term impact: We prioritize interventions that deliver ROI inside 12–24 months, from SKU rationalization and sourcing hedges to clinical evidence generation strategies that accelerate adoption.
Market dynamics shaping vendor and buyer choices
The fully closed ventilator breathing circuit market is being re-shaped by several converging forces. Clinically, hospitals and integrated care networks are tightening infection-prevention bundles — closed system designs and closed-suction integrations are increasingly considered standard elements of ventilator-associated pneumonia (VAP) risk mitigation. Technologically, condensation management (heated wires, vapour-permeable membranes and targeted humidification) is a key differentiator that extends closed-system run times and reduces intervention rates.
Fully Closed Ventilator Breathing Circuit Market
On the economic front, purchasers face trade-offs between single-use disposables and reusable autoclavable systems: disposables lower cross-contamination risk and simplify logistics but raise unit economics and environmental cost concerns; reusable systems offer lifecycle savings but demand capital, sterilization workflows, and different reimbursement considerations. These dynamics are embedded in our scenario modeling, which quantifies the sensitivity of installed-cost payback to utilization and sterilization throughput assumptions.
Fully Closed Ventilator Breathing Circuit Market
Competitive landscape — who matters and why
- Fisher & Paykel Healthcare (Auckland, New Zealand): A technology leader with proprietary condensation-control designs (Evaqua family) and recent regulatory momentum — including 2025 FDA 510(k) clearances that broaden compatibility with non-invasive and single-limb configurations. Their approach emphasizes reducing circuit breaks and clinician handling, which has implications for total cost of care in the hospital setting.
- Armstrong Medical (UK): Differentiates with vapour-permeable heating technologies designed to keep circuits closed longer and minimize water-trap dependency — an advantage in high-acuity environments where reducing filter changes and line interruptions is mission-critical.
- OEM and systems integrators (Dräger, Medtronic, Hamilton, ICU Medical, Teleflex): These players leverage integration with ventilator platforms and anesthesia systems to lock-in consumable demand and to offer bundled procurement propositions to large hospital groups and health systems.
- Regional and specialized manufacturers (Plasti‑med, Unimax, GaleMed, Besdata, Cathwide, Besmed): These firms compete on cost, niche technology features (spiral heated-wire, closed-suction options), and flexibility for non-traditional channels (home care, ambulatory surgery centers). They are important acquisition or partnership targets for companies seeking scale or localized supply resilience.
Market concentration metrics indicate a moderately consolidated landscape: the top three companies account for a meaningful portion of industry revenue, and the top five expand that footprint further — creating a competitive dynamic where product differentiation, regulatory coverage, and channel partnerships determine share shifts.
Regulatory, reimbursement, and clinical considerations
- Classification and standards: Breathing circuits fall under established U.S. regulatory classifications and international connector/performance standards, with ongoing expectations for ISO-compliant interfaces and documented performance across clinical use cases.
- Reimbursement complexity: While procedural codes exist for breathing circuits, reimbursement dynamics — particularly where codes interact with larger ventilator servicing bundles — can blunt pricing power for standalone circuit products. We model reimbursement scenarios and propose contracting strategies that preserve margin without sacrificing adoption.
- Clinical evidence as a commercial accelerant: Closed-system efficacy claims increasingly require real-world evidence around reduced condensate-related interruptions, lower VAP incidence, and nursing-time savings. Payer and procurement committees are asking for economics that go beyond per-unit price.
Supply chain and manufacturing risk matrix
Our supply chain analysis highlights three vectors of operational risk: single-source components (heated wires, specific polymers), sterilization and logistics constraints for reusable SKUs, and regional manufacturing concentration that can create time-to-replenish challenges in crisis scenarios. The report includes mitigation templates — dual sourcing, strategic inventory buffers, and nearshore manufacturing playbooks — tailored to company size and market exposure.
Strategic recommendations for 2026
- Prioritize condenser-control innovation: For product teams, the fastest route to differentiation in 2026 is demonstrably superior condensation management that reduces circuit handling frequency and supports closed-suction workflows.
- Design channel-specific value propositions: Hospitals, ambulatory surgery centers, and home-care providers require distinct commercial models — from GPO-negotiated contracts and outcome-based pilots in hospitals to bundled disposables and education services for home therapy providers.
- Lock compatibility with ventilator OEMs: Strategic OEM integrations or co-development agreements reduce buyer friction and create recurring consumable streams; pursue interface clearances and interoperability documentation as a priority.
- Make sustainability a credible differentiator: Environmental impact is becoming a procurement consideration. Quantify lifecycle ecology and propose recycling or take-back schemes where feasible without eroding unit economics.
- Evidence-driven adoption programs: Fund focused clinical studies that quantify reductions in clinician interventions and VAP rates, and convert findings into procurement-ready ROI calculators for hospital capital committees.
- M&A and partnership targets: Seek tuck-ins that close gaps in closed-suction capability, humidification, or heating technologies; target suppliers that add route-to-market in under-penetrated geographies or that offer differentiated materials expertise.
What the full report contains (practical deliverables)
PW Consulting’s full market study delivers tactical, executable outputs designed for immediate use by product, commercial, and corporate development teams, including:
- Proprietary market sizing methodology and a reproducible demand model (2020–2032) with transparent assumptions;
- Segment-level scenario analyses and sensitivity testing for utilization, sterilization throughput, and price elasticity;
- Competitive scorecards and supplier risk heatmaps (technology, regulatory, capacity);
- Procurement and contracting playbooks, including sample bid language and clinical-evidence templates for value-based sourcing;
- Go-to-market roadmaps segmented by buyer persona (hospital ICU, perioperative services, home ventilation programs) and channel (distributors, OEM partnerships, direct GPO engagement);
- M&A target shortlists and valuation hygiene checks, prioritized by strategic fit and time-to-synergy; and
- Implementation checklists for Q1–Q4 2026 initiatives, with KPIs tied to adoption, margin expansion, and supply resilience.
How to use these insights in 2026 planning cycles
For CEOs and boards, the practical ask is simple: treat closed-circuit strategy as a cross-functional initiative — product engineering, regulatory affairs, procurement, and clinical affairs must execute against a single set of adoption metrics. For private equity and corporate development teams, the near-term opportunity lies in consolidating specialty suppliers and accelerating clinical validation to convert regional strengths into global commercial platforms. For hospital procurement leaders, the focus is on negotiating outcome-linked contracts that reward lower clinical intervention rates rather than simple per-unit price cuts.
Closing — why PW Consulting’s perspective matters
Our analysis combines granular market modeling (rooted in a 2025 base-year assessment) with qualitative insight from vendor technology positioning, regulatory trends, and hospital procurement behavior. The bottom line: the Fully Closed Ventilator Breathing Circuit Market is a growth market with clear levers for differentiation — technical (condensation control), commercial (OEM compatibility), and operational (supply resilience). How companies act in 2026 will determine whether they capture upside from steady CAGR-driven expansion or cede share to better-integrated competitors.
For organizations evaluating strategic options — from portfolio realignment and technology investment to targeted M&A — the full PW Consulting report contains the segmentation detail, pricing models, supplier scorecards, and scenario outputs needed to convert insight into executable plans. Access the complete intelligence and proprietary data sets through our research portal to unlock the detailed segmentation and forecasts that are intentionally omitted here to preserve the value of the full publication.
For detailed analysis of this topic, please visit the official page: Fully Closed Ventilator Breathing Circuit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com