

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Liquid Copper Fungicide Market to Surge to USD 480.77 Million by 2032, Growing at a 4.82% CAGR

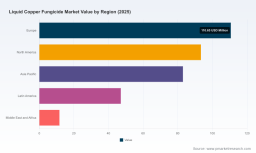
Liquid Copper Fungicide Market — Strategic Outlook for 2026 Decisions
PW Consulting’s latest market intelligence brief, "Liquid Copper Fungicide Market — Strategic Outlook (Base Year 2025, Forecast 2026–2032)", synthesizes commercial, regulatory and supply-chain forces that will determine competitive advantage through the coming investment cycle. The market is at an inflection point: from a 2025 baseline of USD 345.8 Million (base year) PW forecasts a steady expansion to roughly USD 480.8 Million by 2032 at a compound annual growth rate (CAGR) of 4.82% — a trajectory that rewards timely strategic repositioning but penalizes firms that underprice regulatory and raw-material risk.
Liquid Copper Fungicide Market
Why this report matters for 2026 corporate strategy
-
Decision-ready insights: The report translates macro forecasts into executable choices for portfolio managers, commercial leads, and M&A teams — showing where to defend, where to divest, and where to invest.
Liquid Copper Fungicide Market -
Regulatory-first planning: With tightening rules in key markets, regulatory compliance is no longer a back-office cost — it is a strategic lever. Our analysis equips legal and regulatory affairs teams to quantify regulatory exposure and to prioritize interventions.
Liquid Copper Fungicide Market -
Supply-chain resilience: The brief maps exposure to upstream copper markets, tariff risk and formulation-specific sourcing constraints so procurement and operations leaders can design hedges, alternative sourcing and formulation strategies.
-
Commercial playbooks: For sales and country managers, we provide segmented GTM options and channel strategies calibrated to evolving farmer practices and organic-market opportunities.
Market dynamics driving 2026 choices
-
Growth with constraints — steady expansion at moderate pace: The market’s mid-single-digit CAGR masks a bifurcated reality: demand growth from crop intensification and disease pressure on one hand, and tighter use restrictions and substitution pressure on the other. Management teams must balance volume-driven growth strategies with compliance-driven cost pressures.
-
Regulatory tightening in Europe: EU-level limits continue to shape product life cycles — notably the cap on cumulative copper applications, which constrains long-term on-farm usage patterns and accelerates farmer adoption of copper-reducing practices. In July 2025, France’s ANSES re-authorized a defined set of copper products under stricter worker-protection and environmental conditions and explicitly flagged several copper compounds as candidates for substitution. These developments materially affect registration risk and the commercial window for existing formulations.
-
Raw-material and trade risk: Upstream cost dynamics are pronounced. Copper feedstock prices and announced tariff risks (including a proposed U.S. tariff on refined copper announced in mid‑2025) increase the importance of input-cost management and localized sourcing strategies. For example, spot references show elevated copper sulphate pricing in 2025, which has direct P&L implications for liquid formulators that cannot pass through costs rapidly.
-
Supply-side concentration and distribution plays: Market concentration analysis shows a meaningful share of value captured by the largest suppliers and distributors. That concentration creates both acquisition targets (for players seeking scale) and bargaining challenges for buyers. Recent commercial transactions in Europe highlight that distribution control is a strategic priority.
Competitive landscape — what leading players are prioritizing
The competitive field combines global agrochemical majors, specialty formulators and regional specialists. Each archetype pursues a different route to defend or expand share:
-
Global crop protection giants (examples include Bayer, Corteva and FMC) leverage multi‑channel distribution, broad registrant portfolios and R&D budgets to refresh formulations and to integrate copper options into integrated disease-management bundles. FMC’s recent product introductions in target markets underscore innovation in copper hydroxychloride formulations.
-
Regional formulators and distributors (UPL, Nufarm, Sipcam-Oxon, Albaugh and others) focus on agility: rapid route-to-market for liquid formats, tactical acquisitions of distribution assets to increase footprint, and tailored service models for growers. The mid‑2024/2025 activity in European distribution illustrates this consolidation dynamic.
-
Organic and specialty providers (Certis, Nordox, Bonide and niche brands) pursue differentiated positioning with liquid formulations allowed in organic or home-garden channels — a strategic hedge as regulatory pressure on conventional copper use rises.
-
Smaller chemical producers and formulators continue to compete on cost and formulation expertise (including conversion of solid chemistries to liquid sprays), but they face strategic choices about partnering versus consolidating to maintain commercial scale.
Recent developments that change the strategic calculus
-
Regulatory: ANSES’s July 2025 authorization introduced stricter conditions of use and reinforced the classification of some copper compounds as candidates for substitution — a near-term operational constraint and a long-term innovation trigger.
-
M&A and distribution: Sipcam Oxon’s acquisition activity to expand European distribution capacity demonstrates the value of channel control in a market where regulatory friction increases the transaction cost of entering new territories.
-
Product innovation: Strategic product launches such as FMC’s copper hydroxychloride introduction in India exemplify how formulation enhancements and local regulatory strategy can create differentiated market access even amid tighter product-use regimes.
-
Macro trade exposure: Proposed tariff measures and volatile copper prices in 2025 materially raise the cost of goods for liquid formulations and increase the value of localized production and strategic raw material contracts.
Practical strategic levers for 2026 — recommended actions
-
Portfolio rebalancing: Reassess product portfolios to prioritize formulations with favorable regulatory outlooks and to accelerate development of copper-reducing alternatives. Use staged investments tied to regulatory milestones rather than blanket R&D pushes.
-
Supply-chain de‑risking: Secure multi-source supply agreements, increase local formulation capacity where tariffs or transportation pose risk, and consider strategic hedges for copper feedstocks. Small margin improvements on input sourcing can protect earnings in a 4–6% growth environment.
-
Regulatory engagement: Establish forward-looking regulatory roadmaps by geography. Prioritize registrations with robust worker-protection measures and environmental-risk mitigation packages that are increasingly demanded by authorities and large buyers.
-
Channel and go-to-market differentiation: For players targeting growers directly, invest in stewardship programs and application-optimization services that extend product life by lowering unit-use intensity. For distributors, pursue selective acquisitions to secure shelf space and logistical advantage.
-
M&A and partnerships: Target distribution assets and regional formulators that add regulatory licenses or localized production. Partnerships with biologicals and alternative-disease-control providers can create hybrid offerings that reduce copper dependency.
What PW Consulting’s full report delivers (high-level)
-
Comprehensive market model: Historical time series (2020–2025), base-year reconciliation (2025) and scenario-driven forecasts (2026–2032) in USD Million with drill-down capability for executive teams.
-
Regulatory and environmental tracker: A jurisdiction-by-jurisdiction digest of key thresholds, recent decisions and anticipated policy moves that materially affect product life cycles.
-
Supply-chain risk matrix: Input-cost sensitivity analysis, tariff exposure assessment and supplier concentration diagnostics to prioritize sourcing interventions.
-
Competitive playbooks: Profiles of leading firms, strategic moves observed in the field (product launches, distribution deals), and battleground maps for formulation and channel competition.
-
Commercial tools: Go-to-market playbooks tailored by channel (industrial, farm-input distributors, organic/home markets), pricing levers and promotional ROI benchmarks.
-
Executable deliverables: Interactive Excel models, scenario simulators, and a prioritized roadmap for short-term (12 months) and medium-term (36 months) decision pathways — designed for rapid integration into board and investor materials.
Methodology and scope
The analysis uses PW Consulting’s proprietary market-sizing methodology anchored to independent shipment and registration datasets, augmented with primary interviews across supply-chain actors and regulatory authorities. The base year is 2025, figures are expressed in USD Million, and the forecast horizon runs from 2026 through 2032. The report is intentionally structured to provide immediate, implementable outputs for commercial, regulatory, procurement and M&A teams.
Next steps — where to access deeper intelligence
PW Consulting’s release is purposefully framed as a strategic preview: it surfaces the insights and the implications but preserves the granular segmentation and proprietary financial models for subscribers and commissioned clients. If your 2026 planning cycle depends on confident assumptions about pricing sensitivity, regulatory scenario impacts, or target-screening for M&A, PW offers tailored briefings and data access packages to accelerate decision cycles.
Contact PW Consulting to schedule an executive briefing or to obtain the full market dataset, segment-level forecasts and the downloadable scenario models that power boardroom decisions in 2026.
For detailed analysis of this topic, please visit the official page: Liquid Copper Fungicide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com