

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Market Insights: Advanced Insulation Materials Poised to Grow at a 9.24% CAGR Through 2032

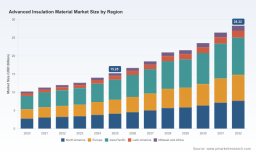
Advanced Insulation Material Market Research: Strategic Briefing for 2026 Decision Makers
Executive snapshot
The advanced insulation materials market has moved from niche engineering applications to a core element of corporate strategy across construction, energy, mobility, and industrial sectors. Our new PW Consulting Advanced Insulation Material Market Research (base year 2025) shows this market expanding from approximately USD 10.2 billion in 2020 to about USD 15.25 billion in 2025, and—under current technology, regulatory and macroeconomic trajectories—growing at a compound annual growth rate of roughly 9.24% through the 2026–2032 forecast window to exceed USD 28 billion by 2032. This briefing highlights the report’s strategic value for 2026 decision-making: where to prioritize R&D and capex, how to de‑risk procurement and logistics, and which go‑to‑market moves materially alter competitive position. In keeping with our “trailer” principle, we signal findings and implications while preserving the detailed segment-level tables and financials for report subscribers.
Advanced Insulation Material Market Research
Why this matters for 2026 planning
- Multi-sector demand convergence: Energy transition, building decarbonization, electrification of transport, and higher process-efficiency standards are converging to create sustained, multi-end-market demand for higher-performance insulation technologies. This creates both scale opportunities and engineering constraints for suppliers and OEMs.
- Investment timing is critical: With a mid-to-high single-digit CAGR and accelerating adoption curves in critical subsegments, companies that lock in scalable manufacturing, secure feedstock contracts, and move early on product certification will capture outsized margins by 2028–2030.
- Regulatory and trade dynamics are reshaping economics: Tighter product and environmental rules, plus evolving trade measures and freight cost volatility, are pushing production closer to end markets and increasing the value of vertically integrated or regionally diversified supply chains.
What the PW Consulting report delivers (practical, actionable content)
The report is built for commercial, operations, and corporate strategy teams who must convert market intelligence into executable plans in 2026. It is not a high-level summary: it contains models, templates and executable playbooks designed to be reused in board decks and procurement negotiations. Highlights include:
Advanced Insulation Material Market Research
- Robust market-sizing and validated topline forecasts (2020–2025 historical, 2026–2032 scenarios) with sensitivity analysis to feedstock cost, regulation, and trade policy shocks.
- Unit-cost build-ups and margin models for leading technology classes—enabling objective supplier benchmarking and break‑even analysis for in‑house manufacturing versus contract manufacturing.
- Regulatory and standards matrix across major markets with clear compliance checklists, time-to-certify estimates, and impact maps for product features (thermal conductivity, flammability, allowable blowing agents, etc.).
- Supply‑chain heatmaps and supplier scorecards, including transport-cost scenarios, bottleneck risk flags, and contingency sourcing pathways for key feedstocks and components.
- Competitive playbooks and diligence checklists for M&A, JV and licensing—complete with red-team questions, integration risk checklists and expected synergy ranges under conservative and aggressive scenarios.
- Go‑to‑market modules for OEM partnerships (e.g., mobility battery thermal management), specifying sample contract terms, performance KPIs and co‑development milestones.
- Interactive decision frameworks: priority matrices to guide capital allocation between capacity expansion, R&D, and commercial penetration by vertical.
Competitive landscape: strategic moves to watch
The market remains moderately concentrated: the leading three players collectively command a material share of demand while the top five increase that concentration further—leaving room for both niche innovators and strategic consolidators. Our competitive analysis synthesizes public filings, product launches, capacity investments and certification milestones to profile incumbent strengths and near‑term vulnerabilities.
Advanced Insulation Material Market Research
- BASF SE (Ludwigshafen): A global materials leader leveraging integrated chemical value chains to scale foam-based product lines. Recent capacity expansions at core sites reinforce BASF’s strategic aim to secure feedstock-to-product linkages; this approach helps blunt raw-material volatility but requires continued capex to defend margin.
- Dow Inc. (Midland): Focused on high-performance PIR foams and construction sealants, Dow combines product breadth with channel reach. Their showcase of next‑generation systems indicates a push to lock specification-level superiority into major projects and specification libraries—an important tactic for sustained share gains in construction and infrastructure programs.
- Saint‑Gobain (Courbevoie): A leading building-materials integrator, Saint‑Gobain’s sustainability certifications are now a commercial differentiator in public-works and green building procurement. This positions them well where product life-cycle credentials are weighted in bids.
- Rockwool & Knauf Insulation: Both maintain strong positions in mineral-wool and glass-wool systems, respectively; recent new-grade launches and acoustic-thermal integrated solutions highlight the role of product breadth in retaining specification authority in retrofits and facades.
- Aerogel specialists (Aspen Aerogels, Cabot): These players continue to commercialize high-value niche applications—from EV battery thermal management to translucent insulating panels—where performance trumps unit cost. Their development pace will define how quickly aerogels move from specialist to mainstream segments.
- Regional & system players (Armacell, Kingspan, Owens Corning): These firms compete on systems thinking: combining boards, elastomers and installability. Their strategic focus on installation efficiency and contractor channels reduces total installed cost, an increasingly important procurement lever.
Recent industry signals and implications for 2026
- Raw material inflation and feedstock scarcity have created near‑term input-cost pressure. For 2026 planning, treat feedstock exposure as a first‑order strategic risk: lock multi-year contracts where possible, model pass-through scenarios, and evaluate alternative chemistries where feasible.
- Regulatory tightening on acceptable blowing agents and performance thresholds is raising the bar for product development and certification lead times. Allocate budget and timeline to pre‑certification validation for product launches targeted at public and large commercial projects.
- Trade remedies and country‑level duties on certain imports have materially changed the calculus for low-cost sourcing from some origins. Expect near-term reshoring, nearshoring and contract manufacturing as firms seek to avoid tariff volatility.
- Shipping and logistics cost volatility is increasing landed cost unpredictability. Our scenario models show that for long‑leaded, freight‑sensitive products, local production or regional distribution hubs materially improve cost stability and service levels.
- Customer requirements are shifting from commodity cost to total installed cost and life‑cycle performance—creating an opening for higher‑margin products that demonstrably reduce energy use, maintenance or replacement frequency.
Strategic actions for 2026 (what winning companies will do)
- Hedge and diversify feedstock exposure: Use a mix of multi‑year contracts, financial hedges and strategic supplier partnerships. Evaluate capex to vertically integrate or co‑locate with key feedstock producers where economics support it.
- Prioritize regulation‑ready product roadmaps: Accelerate compliance pathways for the stricter environmental and construction standards coming into force; early certification buys specification advantage in public tenders.
- Invest in high-value niches while defending scale: Pursue selective R&D in aerogels, vacuum panels and phase-change composites for high-margin applications (EV thermal management, cryogenic, high-efficiency buildings) while protecting mass-market board and blanket volumes.
- Reconfigure supply footprint: Model the trade-offs of regional manufacturing nodes—including capex, time-to-market and tariff avoidance—to determine nearshoring thresholds for 2026–2028.
- Commercialize performance economics, not just materials: Package insulation as a life‑cycle cost play for customers (energy savings, maintenance deferral), and design KPls and contracts that crystallize those savings for buyer procurement teams.
- Use M&A and partnerships prudently: Given moderate market concentration, tuck‑ins can be accretive—especially for proprietary technologies that shorten certification timelines or open new verticals. Our M&A playbook quantifies likely multiple ranges and integration pitfalls.
How PW Consulting supports your 2026 roadmap
The full PW Consulting report provides the underlying datasets, regional supply‑chain maps, unit‑cost models and downloadable templates you need to run internal sensitivity workshops and update 2026 capital plans. Importantly, subscribers gain access to our interactive scenario tools so teams can stress‑test strategic options—e.g., the ROI of a new regional plant under different freight‑cost and tariff assumptions, or the margin impact of alternative blowing agents that meet the newest environmental restrictions.
Next steps
For leaders preparing 2026 budgets and strategic plans, the choice is straightforward: operate on legacy assumptions and accept rising volatility, or use targeted intelligence and operational playbooks to convert market growth into sustainable margin and specification leadership. Our Advanced Insulation Material Market Research is structured to move teams from insight to execution in weeks, not months.
To access the full dataset, segmentation tables, competitor scorecards and tailored scenario outputs, visit the PW Consulting report page. The full report contains the detailed segment-level figures and granular regional and application breakdowns that underpin the strategic recommendations summarized above.
For detailed analysis of this topic, please visit the official page: Advanced Insulation Material Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com