

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Lithium Battery Ethylene Carbonate Market to Surge to USD 1,568.24 Million by 2032 on a 13.15% CAGR

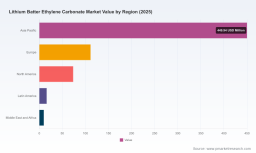
PW Consulting Releases Strategic Brief: Navigating the Rapid Rise of the Lithium Battery Ethylene Carbonate Market
PW Consulting today publishes an executive briefing accompanying our full market study, “Lithium Battery Ethylene Carbonate Market — Strategic Outlook 2026–2032,” offering decision-makers an actionable roadmap for capital allocation, supply-chain design, and technology strategy as ethylene carbonate (EC) becomes a central battleground for battery-materials competitiveness.
Lithium Batter Ethylene Carbonate Market
Why this report matters for 2026 decisions
Our analysis finds the global ethylene carbonate market expanding at a compound annual growth rate (CAGR) of 13.15% through the 2026–2032 forecast window. The market more than doubled in scale from the start of the decade and crossed an important threshold in our base year (2025), reflecting the convergence of accelerating electric vehicle (EV) deployments, growth in stationary energy storage, and ongoing demand in consumer electronics. By 2032, the market size is projected to exceed USD 1.5 billion (revenue unit: Million USD), creating both material upside for incumbents and strategic pressure for new entrants.
Lithium Batter Ethylene Carbonate Market
For 2026 corporate planning cycles, this trajectory is decisive: it signals a near-term window where investments in production capacity, quality upgrades to battery-grade EC, and upstream raw-material integration can materially alter a supplier’s competitive positioning. Conversely, firms that delay supply-chain commitments risk losing preferred-supplier status with OEMs and cell makers that are already locking long-term supply and qualification lanes.
Lithium Batter Ethylene Carbonate Market
What the briefing delivers — practical, transaction-grade intelligence
The PW Consulting report is designed as an operational decision-support toolkit. Highlights include:
- High-conviction market sizing and scenario forecasts (2026–2032) calibrated to recent plant announcements, capacity transfers, and observed demand pull from battery manufacturers.
- Supply-chain cost stacks and sensitivity analyses — showing which inputs drive margin volatility and where procurement teams should focus hedging and contract design.
- Regulatory and ESG overlays that quantify how low-emission synthesis routes and feedstock choices alter CAPEX/OPEX and supplier selection criteria.
- A supplier-playbook for battery manufacturers and chemical companies: qualification checklists, audit frameworks, and a staged-onboarding matrix for battery-grade EC supply relationships.
- Strategic options and investment roadmaps for incumbents and private-equity investors, including brownfield expansion, JV structures, and bolt-on M&A criteria.
- Scenario-based pricing models and recommended contracting instruments (indexation, floor/ceiling collars, and volume-flex clauses) tailored to both sellers and buyers.
- Commercial due-diligence dossiers and integration checklists for the top producers — enabling rapid appraisal of capabilities, geographic exposure, and technical readiness.
Key market dynamics shaping supplier economics
Three dynamics will dominate supplier economics through 2026 and beyond:
- Input-cost structure: A large majority of production cost for EC is driven by a single upstream intermediate; our synthesis of supplier cost models shows this intermediate typically represents well over half of variable costs. This concentration magnifies the impact of upstream shortages and price swings on EC margins and explains the premium for vertically integrated producers.
- Technology and product-grade differentiation: Battery-grade (>99.99% purity) EC commands differentiated qualification timelines and capital intensity. Manufacturers able to demonstrate repeatable high-purity output and robust QA/QC protocols will extract a scarcity premium from leading cell-makers during supplier selection.
- Regulatory and sustainability pressures: Nearly half of producers have already adopted or begun trials of lower-emission synthesis pathways that leverage alternative feedstocks. Such moves are reshaping CAPEX allocations and are increasingly table stakes for OEMs with aggressive Scope 3 targets.
Competitive landscape — who matters and why
The sector remains moderately concentrated: the top three suppliers control a substantial portion of market share, and the top five substantially increase that concentration. This market structure yields both opportunities and constraints for buyers and mid-sized suppliers. Large producers benefit from scale, supplier-customer stickiness, and the ability to finance capital-intensive upgrades to battery-grade capacity. At the same time, niche players with flexible production lines and proximity to cell-manufacturing clusters are winning fast-track qualifications with regional OEMs.
Our report includes deep profiles of the industry’s strategic players — capturing strategic footprints, recent capacity moves, and partnership signals. Notable dynamics include:
- Mitsubishi Chemical Group Corporation (Japan) — reinforcing global network optimization through new Southeast Asian capacity and recent asset transfers designed to align production with regional cell-manufacturing demand corridors.
- Huntsman International (United States) — expanding North American supply options with product grades tailored to EV electrolytes, sharpening its appeal to OEMs pursuing regionalized sourcing.
- Major Asian producers — including long-standing Taiwanese and Japanese specialty-chemical players, and large Chinese manufacturers — competing through vertical integration, proximity to battery clusters, and rapid scale-up capabilities.
- Specialty suppliers and high-purity niche manufacturers — focusing on rigorous quality controls and specialized logistics to serve battery makers with demanding qualification protocols.
Recent developments in the supply base—new facilities, capacity investments, and asset rearrangements—are accelerating the shift toward a two-tier market: a commoditized industrial grade segment and a premium battery-grade channel where qualification timelines and reliability matter most.
Supply risk, pricing signals and procurement implications
Procurement teams must recognize three actionable implications for 2026 contracting:
- Lock early, but structure flexibly: Given the growth trajectory and periodic raw-material volatility, multi-year take-or-pay constructs with embedded flexibility on volumes are prudent to balance security and cost efficiency.
- Prefer integrated suppliers where reliability is paramount: Suppliers with upstream integration can offer more stable cost pass-through and quicker response to feedstock disruptions. However, pure-play specialty providers can be attractive for premium-grade supply if backed by robust quality evidence.
- Embed ESG and regulatory resilience in SLAs: With an increasing share of manufacturers adopting low-emission synthesis, buyers should require transparency on production pathways, emissions accounting, and continuity plans to avoid reputational or compliance risk.
Technology trends and the innovation horizon
Research into electrolyte chemistries is actively evolving. Market participants are tracking developments in electrolyte formulations that reduce reliance on traditional carbonate solvents or use lean/EC-free blends aimed at mitigating high-temperature side reactions and improving thermal behavior. These technological shifts are neither immediate nor binary: early-mover battery developers may capture performance advantages, but widespread adoption will hinge on cost, manufacturability, and safety validation. For suppliers, the strategic question is whether to pursue incremental purity and cost improvements for current EC formulations or to diversify R&D toward next-generation solvents and additive packages.
How to use this briefing in your 2026 planning
Executives and strategy teams should use our study to:
- Inform CAPEX prioritization — allocate spend between expanding battery-grade capacity versus retrofitting existing lines for lower-emission synthesis.
- Design procurement strategies that balance security, cost, and ESG considerations — using our recommended contracting templates and scenario-tested pricing models.
- Screen M&A targets and JV partners using our commercial due-diligence framework that emphasizes production quality, feedstock exposure, and customer qualification pipelines.
- Prepare technology roadmaps that hedge between current EC-centric demand and potential shifts toward alternative electrolytes.
What we withhold — and why you’ll want the full dataset
Consistent with our “trailer” principle, this briefing surfaces the strategy-defining trends and the macro sizing (including aggregate market scale and a 13.15% CAGR), but it intentionally withholds the granular segment-by-region and application-level tables in order to protect the actionable intelligence that buyers, suppliers, and investors value most. The full report contains the detailed segmentation, regional demand curves, application-level demand projections, supplier-level capacity buildouts, and proprietary price models required to execute deals or capital projects in 2026.
For procurement directors, strategy leads, and investment teams that require transaction-grade inputs — including build/no-build decision triggers, payback sensitivity curves, and supplier risk heatmaps — the complete dataset and the appendices provide the necessary fidelity to operationalize a 2026 strategy.
Next steps and availability
PW Consulting’s full “Lithium Battery Ethylene Carbonate Market — Strategic Outlook 2026–2032” report is available now. Clients can commission tailored briefings, bespoke supplier analyses, and on-site workshops to translate the findings into a 90–180 day implementation plan. For firms evaluating immediate procurement or investment actions, our advisory teams are standing by to run a rapid alpha-assessment using client-specific inputs.
Contact PW Consulting to request the full report and to schedule a bespoke executive workshop that translates market trajectories into executable 2026 decisions.
For detailed analysis of this topic, please visit the official page: Lithium Batter Ethylene Carbonate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com