

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Industrial Sodium Nitrate Market Reaches USD 520 Million in 2025, Forecast to Grow at a 4.02% CAGR (2026–2032)

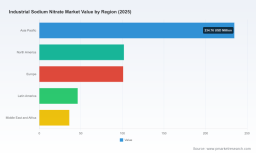
Industrial Sodium Nitrate Market — Strategic Briefing for 2026 Decision-Makers
By PW Consulting — Senior Strategy Advisor & Chief Industry Analyst
Industrial Sodium Nitrate Market
Executive summary
The industrial sodium nitrate market has transitioned from a niche industrial input to a strategically significant commodity for suppliers and end-users alike. Our latest market study (base year 2025) finds that the global market reached approximately USD 520.0 Million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 4.02% over the 2026–2032 period, reaching roughly USD 685 Million by 2032 under the central case. For corporate leaders planning investments, supply agreements, or M&A activity in 2026, this trajectory presents an imperative: act with precision, not haste. This briefing highlights the high-level strategic takeaways from our report and explains why the full dataset and granular segmentation are essential for any execution plan.
Industrial Sodium Nitrate Market
Why this market matters now
-
Built-in cross-sector exposure: Sodium nitrate serves diverse industrial applications — from glass manufacturing and metal treatment to explosives and emerging thermal energy storage — giving producers and suppliers a multi-demand buffer during cycling in any single end-market.
Industrial Sodium Nitrate Market -
Measured but steady growth: The market’s mid-single-digit CAGR signals a maturing commodity with predictable demand patterns, creating opportunities for operational optimization, targeted capacity additions, and price-risk management rather than speculative buildouts.
-
Concentration with room for disruption: Industry concentration is meaningful but not prohibitive. The competitive landscape includes global incumbents and nimble regional players, creating strategic openings for partnerships, asset acquisitions, or differentiated product/grade positioning.
Market trajectory and what the headline numbers conceal
The headline — USD 520.0 Million in 2025 and a ~4.02% CAGR to 2032 — masks a complex mix of regional demand cycles, grade-specific supply dynamics, and feedstock cost sensitivity. For example, year-on-year growth is not linear: pockets of accelerated demand driven by decarbonization projects or glass capacity additions can create localized tightness, while softness in construction or mining-related end-markets may depress volumes elsewhere.
Crucially, unit economics depend on feedstock exposure. Sodium nitrate production is fundamentally linked to nitric acid and soda ash (sodium carbonate) inputs; shifts in those markets directly influence producer margins and pricing strategies. Our full report models multiple feedstock-price scenarios and their impact on producer cash flows and breakeven thresholds — a must-have for procurement and finance teams contemplating long-term contracts or tolling arrangements in 2026.
Competitive landscape — who matters and why
The competitive field blends resource-origin players, large chemical majors, and regional producers. Key enterprises we profile include established global suppliers and several large-scale producers from resource-rich markets. These players differ by asset base (natural deposits vs. synthetic production), integration into nitrate value chains, geographic exposure, and strategic focus on purity grades and specialty formulations.
-
Resource-origin leaders: Firms extracting sodium nitrate from natural deposits have the advantage of feedstock cost asymmetry and large-scale, stable output. Their strategic play centers on sustaining low-cost positions while managing environmental and community impacts associated with extraction.
-
Integrated chemical majors: Large chemical producers deploy global distribution networks and multi-product portfolios, offering customers integrated solutions but facing higher structural costs. Their strategic priorities are margin protection, leveraging cross-selling opportunities, and deploying proprietary formulations for high-value applications.
-
Regional and specialty producers: These players compete on agility, local service, and customized grades. Their value proposition is proximity, speed-to-market, and the ability to supply specialized purity levels or packaging options to niche end-users.
Recent corporate moves underline these strategic differences. Notably, one Indian manufacturer announced a capacity expansion with a new facility launched in the Middle East in 2025, signaling an outward push to serve export markets and diversify supply footprints. Meanwhile, a leading producer from Chile reported production updates and ongoing capacity expansion projects with explicit commitments to reduce environmental impact — a directional signal that sustainability investments will be a competitive differentiator.
Supply, pricing dynamics, and procurement implications
Short-term price behavior is being driven by feedstock volatility, regional demand swings, and end-market softness or strength. Price-monitoring snapshots show European and North American price movements that diverged in early 2026, reflecting differing demand and feedstock conditions. Buyers and sellers must therefore adopt differentiated procurement strategies:
-
Hedged procurement for industrial users with thin margins: Longer bilateral contracts with index-linked clauses or tolling arrangements can stabilize variable input costs and secure supply continuity.
-
Flexible contracts for cyclical end-users: Shorter-term or spot-linked sourcing may be preferable where end-market exposure is high and price declines are expected.
-
Feedstock risk sharing: Joint sourcing or integrated supply agreements with feedstock suppliers (nitric acid, soda ash) can materially reduce margin volatility for manufacturing-focused players.
Regulatory and sustainability forces shaping investments
Regulatory scrutiny on nitrogen compounds’ environmental impacts—especially water quality and soil health considerations—means compliance will increasingly influence capital allocation. Producers will need to prioritize investments in cleaner technologies, effluent treatment, and monitoring systems to meet tightening standards and to retain market access in sensitive jurisdictions.
Furthermore, sustainability is becoming a procurement criterion: large industrial buyers are integrating supplier environmental performance into sourcing decisions. This opens two strategic avenues for producers in 2026: accelerate decarbonization and certifications to command premium contracting, or pursue cost leadership and efficiency gains where compliance is already achievable at scale.
Strategic playbook for 2026 — four prioritized moves
-
Refine exposure to grades and applications: Map revenue sensitivity by grade and end-use to prioritize investments in the grades that deliver the highest margin resilience. Our report provides the scenario matrices that translate shifts in application demand into revenue and margin outcomes.
-
Pursue targeted capacity or capability additions: Opt for modular expansions, tolling partnerships, or brownfield upgrades rather than greenfield mega-projects unless backed by long-term offtake agreements.
-
Lock in feedstock and logistic resilience: Negotiate strategic feedstock agreements and diversify logistics partners to mitigate shipping disruptions and regional supply shocks.
-
Embed sustainability as a commercial lever: Prioritize cost-effective emissions and effluent reductions that can be monetized through contract premiums or used to secure large industrial clients.
What the PW Consulting report delivers (practical contents)
We designed the report as a working toolkit for decision-makers. Key deliverables include:
-
Comprehensive market sizing and forecast models (2020–2032) with scenario stress tests for feedstock, regulatory, and demand shocks.
-
Competitive benchmarking templates and acquisition screening filters to assess strategic fit and value creation potential across the supplier universe.
-
Commercial playbooks for procurement, pricing, and customer segmentation — including contract archetypes and negotiation levers aligned to different risk appetites.
-
Capex prioritization matrices and ROI calculators tailored to greenfield vs. brownfield expansion choices.
-
Regulatory impact assessments and a practical guide for implementing lower-impact production routes and compliance investments.
Why you should act in 2026
With a stable mid-single-digit growth path and ongoing structural shifts in feedstock pricing, regulatory pressure, and customer procurement behavior, 2026 represents a decisive planning window. Organizations that develop robust, data-driven sourcing strategies and that align investment plans to the detailed scenario outputs in our report will secure advantaged positions — either as low-cost suppliers, differentiated specialty providers, or preferred strategic partners for large industrial buyers.
Accessing the full intelligence
This briefing intentionally highlights strategic insights while withholding granular segmentation matrices, region- and application-level breakouts, and proprietary company-level share analysis so that commercial users consult the full report for transaction-grade intelligence. The complete package contains the exact segmentation, price-elasticity curves, and supplier-level exposure analyses necessary to underwrite procurement contracts, capex projects, or M&A propositions in 2026.
Next steps
-
Procurement leaders: request the sensitivity module to stress-test contract terms against feedstock scenarios.
-
Corporate development teams: use our acquisition screening toolkit to identify targets that enhance either cost position or technology differentiation.
-
Operations and sustainability teams: adopt the regulatory impact playbook to prioritize compliance investments that unlock commercial value.
PW Consulting’s Industrial Sodium Nitrate Market report is structured to turn market intelligence into executable plans. For access to the full dataset, detailed segment analytics, and tailored consulting support for 2026 initiatives, visit our report page or contact the PW Consulting advisory team.
For detailed analysis of this topic, please visit the official page: Industrial Sodium Nitrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com