

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Uterotonic Agent Market to Surge at a 6.19% CAGR as Asia‑Pacific Emerges as the Growth Engine

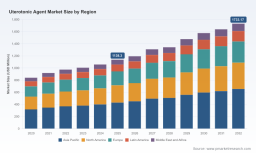
Uterotonic Agent Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
PW Consulting today releases an executive briefing summarizing the strategic value of our full Uterotonic Agent Market report (base year: 2025) for decision-makers preparing plans and capital allocations in 2026. The uterotonic market is returning to the strategic spotlight as global maternal-health priorities, supply-chain realities and product innovation converge. Our analysis — built on 2020–2025 historical trends and a 2026–2032 forecast horizon — quantifies that convergence and converts it into actionable priorities for manufacturers, procurers, investors and policy-makers.
Uterotonic Agent Market
Market snapshot: scale, growth and concentration
By our accounting (USD; revenue unit: Million), the global uterotonic market surpassed the one-billion-dollar threshold in the mid-2020s and recorded USD 1,138.3 Million in 2025. The market is set to expand at a compound annual growth rate (CAGR) of approximately 6.19% across the 2026–2032 forecast window, reflecting steady demand across both high- and middle-income markets and accelerating adoption in supply-challenged settings. Our concentration analysis indicates a moderately consolidated supplier landscape: the top-tier manufacturers represent a material share of procurement channels, while a broader cohort of generics and regionals compete on price and local availability.
Uterotonic Agent Market
These headline figures mask important structural dynamics — product-level substitution, quality vs. price tradeoffs, cold-chain dependence, and evolving procurement preferences — which are addressed throughout the full report. To preserve the value of the source intelligence and encourage direct engagement with our dataset, we deliberately avoid reproducing the core segmentation tables here; subscribers can access the full breakdown by region, drug type and application on the report landing page.
Uterotonic Agent Market
Why 2026 is a decision inflection point
- Procurement and quality are decoupling: Donor and national procurement programs are increasingly prioritizing quality-assured product lists and WHO prequalification status. Recent industry events — including a new oxytocin prequalification and expanded supplier lists published by global health actors — are already reshaping tender outcomes. Buyers who rely on legacy, lowest-price sourcing risk exposure to quality and reputational anomalies; our analysis models the fiscal and clinical cost of that risk across typical procurement portfolios.
- Heat-stable innovation changes the calculus: The emergence and licensing of heat-stable carbetocin have reframed cold-chain-dependent decisions in low-resource settings. Where cold-chain guarantees are weak, heat-stable alternatives materially reduce the logistics friction and loss rates that erode effective supply. For market entrants and incumbent suppliers, this creates differentiated commercial pathways and IP/licensing considerations that will decide market access in many public-sector tenders.
- Segmentation-driven growth pockets: Aggregate growth conceals pockets of faster adoption — driven by programmatic prioritization of postpartum hemorrhage (PPH) prevention, expansion of facility-based deliveries, and integration with maternal-newborn-child health (MNCH) initiatives. Our forecasting scenarios isolate these pockets and translate them into near-term revenue runways for product classes and geographies.
What the PW Consulting report delivers — practical, executable insight
Our full report is structured for operational use by commercial strategy teams, procurement agencies and investors. Key deliverables include:
- Clear market sizing and forward-looking scenarios (2026–2032) in USD Million, with sensitivity analyses tied to policy adoption rates and cold-chain improvement investments.
- Competitive positioning maps that combine WHO prequalification status, manufacturing footprint and therapeutic portfolios to identify realistic partner and threat lists for both innovators and generics.
- Procurement playbooks — tender-structuring templates and bid-evaluation scorecards that account for price, quality assurance, lead times and supply resilience.
- Go-to-market frameworks for heat-stable assets and for products that require cold-chain distribution, including pricing strategies, distributor selection, and donor engagement models.
- A regulatory and reimbursement tracker summarizing recent policy shifts and likely regulatory pathways for new formulations and biosimilar strategies.
- Risk matrices quantifying the operational and reputational exposure from product-quality failures, logistics breakdowns, and geopolitical sourcing risks.
Each toolkit component is accompanied by implementation templates and an annotated dataset. The report’s intelligence is intentionally practical: it prescribes “what to do next” as much as it explains “what happened.”
Competitive landscape: who matters and where to partner
The uterotonic market today is shaped by a mix of multinational originators, large generics manufacturers and regionally important producers. Leading originator and specialty players have differentiated portfolios — for example, firms with heat-stable carbetocin offerings are positioned to capture procurement budgets where cold chains are unreliable, while traditional oxytocin and misoprostol suppliers maintain strong presence across clinical indications and institutional channels.
- Large, diversified pharmaceuticals continue to leverage scale and brand trust to secure major institutional contracts and established distribution channels.
- WHO-prequalified generics manufacturers and regional producers play a decisive role in cost-sensitive tenders and in-country supply assurance; their presence is especially material in markets where local production or rapid-response distribution is prioritized.
- Collaborative mechanisms — licensing agreements, prequalification partnerships and pooled procurement initiatives — are accelerating access to heat-stable formulations and amplifying the reach of quality-assured suppliers. These arrangements shift the competitive dynamics by enabling new entrants to gain rapid footholds in public-sector programs.
PW Consulting’s full-length competitive profiles include strategic intent assessments, manufacturing capacity maps, patent and licensing statuses, and procurement win-loss analyses for each major player. For confidentiality and to preserve negotiation leverage for subscribing clients, those detailed segment-level scorecards are available only in the full report package.
Regulatory and supply-chain dynamics you must factor into 2026 planning
- Quality assurance is now a procurement variable: International agencies have strengthened quality filters: recent prequalification activity and supplier lists highlight a market that rewards verifiable quality. Buyers that do not embed quality metrics into tenders will find long-term costs rising through stock losses and clinical failures.
- Cold-chain fragility is a persistent constraint: Conventional oxytocin formulations require 2–8°C storage, which materially increases supply fragility in tropical and low-infrastructure environments. That fragility can translate into effective product loss even when physical inventory counts look healthy; our logistics loss models quantify this effect and offer mitigation strategies, including alternative formulations and local buffer stock policies.
- Policy adoption of heat-stable alternatives is uneven but accelerating: Inclusion of heat-stable formulations on essential medicines lists and targeted licensing agreements has shortened the timeline for procurement uptake in priority countries. The speed and scale of adoption will be central to supplier revenue forecasts and to donor funding decisions in 2026–2027.
Recommended actions by stakeholder type
- Manufacturers & innovators: Prioritize WHO prequalification workflows for target SKUs; develop differentiated commercial propositions that combine product attributes (e.g., heat stability) with service elements (cold-chain support, training, warranty supplies) to win tenders.
- Generic suppliers & regional producers: Invest selectively in visible quality-assurance credentials and pursue strategic partnerships with procurement consortia to overcome price-only competition.
- Procurement agencies & donors: Reconfigure tender evaluation criteria to reward quality-adjusted total cost of ownership rather than unit price; pilot inclusion of heat-stable carbetocin in contexts where logistics risks are high.
- Investors & private-equity: Look for consolidation opportunities among mid-sized generics with WHO-prequalified SKUs and resilient local distribution networks; apply a premium to targets with heat-stable portfolio components and proven tender track records.
How PW Consulting’s report informs 2026 strategy
Decision-makers need to translate macro-level growth into prioritized, executable initiatives. The report does this by combining quantitative forecasting (USD Million market sizing, CAGR and scenario outputs) with qualitative playbooks. Use cases include:
- Building a 2026 product launch plan that aligns inventory, registration and tender calendars with donor funding cycles;
- Modeling procurement outcomes under alternative quality-criteria regimes to justify rebalanced tender scoring systems;
- Stress-testing supply chains against cold-chain failure scenarios to size buffer inventories and local manufacturing investments;
- Constructing investment theses that quantify exit horizons under consolidation and vertical-integration scenarios.
Collectively, these applications make the report a high-leverage input for 2026 budgeting cycles and strategic reviews.
Conclusion — the strategic horizon
The uterotonic market presents a classic case where clinical need, product innovation and procurement policy intersect to create asymmetric opportunities for those prepared to act. With the market already past the billion-dollar mark and a mid-single-digit CAGR projecting continued expansion, 2026 will be the year in which procurement rules and product attributes (not just price) determine market leadership. PW Consulting’s report translates these trends into the concrete actions and decision-support tools that executives need to compete successfully in this evolving landscape.
For executives seeking the full dataset, segmentation tables, supplier scorecards, and the operational playbooks referenced above, please visit the PW Consulting report page to access the complete Uterotonic Agent Market report and subscriber resources.
For detailed analysis of this topic, please visit the official page: Uterotonic Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com