

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Defense Asset Management Software Market to Grow at 8.45% CAGR, Reaching USD 3.43 Billion by 2032

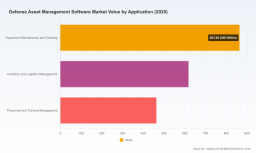
Defense Asset Management Software Market: Strategic Imperatives for 2026 Decision‑Makers
Executive summary
As defense organizations and their prime contractors face accelerating operational tempo and tighter sustainment budgets, the market for defense asset management software is entering a phase of consolidation and strategic opportunity. Our new PW Consulting market study, anchored on 2025 as the base year, projects steady expansion through the 2026–2032 forecast horizon at a compound annual growth rate (CAGR) of 8.45%. The global market crosses a new threshold in 2026 and continues to expand to multi‑billion dollar scale by 2032, a trajectory driven by cloud adoption, regulatory pressure, AI‑enabled sustainment, and an intensifying requirement for lifecycle visibility across increasingly complex platforms.
Defense Asset Management Software Market
Why this matters for 2026 decision cycles
Procurement calendars and modernization programs planned for FY26 should treat defense asset management software not as a tactical procurement item but as a strategic infrastructure investment. Decisions made this year will define integration patterns, security postures, and sustainment economies for a platform’s operational lifetime. Key reasons to reprioritize investment decisions in 2026 include:
Defense Asset Management Software Market
- Macro momentum: Market scale and growth validate vendor investment and ecosystem maturity—reducing early‑adopter risk while increasing options for modular, cloud‑native deployments.
- Regulatory inflection points: Policy initiatives (notably the DoD Software Modernization Implementation Plan FY25‑26, CMMC 2.0 asset management practices, and existing DLMS/DCMA guidance) create near‑term compliance milestones that affect procurement, contracting language, and operational requirements.
- Technology convergence: AI for predictive maintenance, digital twin frameworks, and improved data fusion in command centers are altering what “asset readiness” means and how quickly software can deliver measurable O&M savings.
Core strategic recommendations for 2026
Decision‑makers should adopt a short list of pragmatic actions to extract value from the market while managing program risk. These are prioritized for FY26 execution:
Defense Asset Management Software Market
- Adopt a layered procurement strategy: Combine a cloud‑native core for agility and enterprise licensing with hardened on‑prem or sovereign instances where security or latency constraints demand it. Structure contracts for modularity and upgradeability to avoid multi‑year lock‑in.
- Embed compliance and ATO planning in RFPs: Incorporate SaaS ATO pathways, FinOps metrics, and CMMC/DLMS conformance as pass/fail clauses to avoid expensive retrofits later in the program lifecycle.
- Prioritize data interoperability: Require canonical data models and open APIs in technical evaluation criteria. The ability to transform and ingest non‑standard legacy data will materially shorten time‑to‑value during migration phases.
- Invest in human capital and vendor‑agnostic integration skills: Specialized labor—cleared engineers, integrators, and sustainment SMEs—remains the largest operational cost driver. Build a blended team model of retained core expertise plus vetted systems integrators to scale implementations cost‑effectively.
- Define outcome‑based KPIs and TCO scenarios: Move beyond feature checklists to measure mission readiness, mean time to repair, inventory days of supply, and lifecycle sustainment cost per platform. Require vendors to present modeled scenarios that align to those KPIs.
Report highlights — what PW Consulting delivers
Our research is focused on tactical usability for program and procurement leads. The report is structured to support the 2026 decision window with the following practitioner‑grade deliverables:
- Market sizing and growth trajectory: A validated top‑line series covering 2020–2025 historicals and a 2026–2032 forecast that quantifies the investment runway and expected scaling dynamics.
- Vendor landscape and strategy playbooks: Comparative profiles of incumbent and emergent providers, strategic positioning maps, and acquisition readiness checklists tailored to defense buyers.
- Regulatory and compliance playbook: Practical interpretation of DoD software modernization directives, SaaS ATO processes, CMMC asset management expectations, DLMS transformation requirements, and DCMA license tracking implications.
- Integration and migration roadmaps: Phase‑gated implementation plans, data migration templates, interoperability test matrices, and sample contract language to preserve upgrade and portability rights.
- Value realization models: Scenario‑based TCO and ROI calculators that incorporate labor costs, licensing models, and projected maintenance savings for sample fleet and platform profiles.
- Case studies and lessons learned: Vendor and program case narratives that illustrate common pitfalls, mitigation strategies, and accelerate procurement timelines.
Competitive landscape — positioning and implications
The market exhibits moderate concentration, with top vendors accounting for a meaningful share of supplier revenue—enough to influence standards, but with room for specialist and niche providers to compete on features, integrations, and domain knowledge. Our assessment of leading firms highlights the strategic options available to defense buyers:
- Systems integrators and platform incumbents (e.g., IBM, Oracle, SAP): These firms offer mature enterprise suites with deep lifecycle and ERP integrations, and increasing AI and predictive maintenance capabilities. Their advantages are breadth, established DoD relationships, and end‑to‑end sustainment footprints; the trade‑offs include potentially higher integration effort and legacy architecture constraints unless deployed as cloud‑native modern instances.
- Defence‑specialist EAM vendors (e.g., IFS, Prometheus Group, AssetWorks, eQuip Software): Specialists deliver fit‑for‑purpose workflows for military logistics, inventory control, and fleet sustainment. They often provide faster time‑to‑value for specific domains but may require more significant integration work to achieve enterprise visibility.
- Aerospace and engineering platforms (e.g., Dassault Systèmes, Hexagon): These providers bring digital twin and model‑based systems engineering strengths, which are critical where engineering‑to‑sustainment digital continuity improves mission readiness and lowers lifecycle cost. Their solutions are compelling for platform modernization programs that prioritize design‑ops integration.
- Primes extending into software (e.g., Lockheed Martin, Northrop Grumman): Prime contractors are embedding asset management capabilities into broader sustainment offerings—often attractive for platform‑centric programs but requiring careful IP, data ownership, and vendor neutrality considerations.
- Regional and public sector focused vendors (e.g., CGI, Infor, Ramco Systems): These suppliers often provide strong compliance knowledge and service models tailored to government procurement cycles, with varying cloud‑native maturity.
For 2026 program decisions, the strategic imperative is to select vendor combinations that preserve options: leverage enterprise suites where breadth is required, engage specialists where depth of defense domain capability is mission‑critical, and insist on interoperability and contractual escape hatches to avoid future vendor lock‑in.
Technology and policy tailwinds
Several concurrent forces are reshaping buyer requirements and vendor roadmaps:
- Cloud and SaaS acceleration: DoD guidance on software modernization and SaaS ATO processes reduces friction for cloud deployments while imposing new security and architecture expectations. Buyers must reconcile the need for agility with sovereignty and accreditation timelines.
- AI and predictive maintenance: Vendors are rapidly embedding AI to predict failures, prioritize work orders, and optimize spare parts inventory. The quality of maintenance outcomes will depend heavily on data quality, label provenance, and integration with operational schedules.
- Standards and data governance: DLMS and DCMA requirements continue to mandate specific data capabilities—systems that can normalize legacy data and meet prescribed transaction formats will have a differential advantage during migration.
- FinOps and enterprise licensing: The DoD’s push for enterprise licensing and FinOps discipline means programs must quantify steady‑state software spend as part of any acquisition decision, not just initial license cost.
Practical procurement checklist for 2026
To operationalize strategy, teams should include the following minimum elements in RFPs and acquisition roadmaps:
- Clear ATO roadmap and vendor responsibilities for accreditation.
- Data model and API conformance criteria with sample data transformation tests.
- Outcome‑based KPIs tied to sustainment and readiness objectives, with penalties and incentives aligned to delivery.
- Labor and skills transition plan that accounts for cleared personnel and long‑term maintenance support.
- FinOps requirements for license transparency, metering, and cost allocation.
- Contractual provisions for portability, IP rights for derived data, and an exit strategy including data extraction services.
Conclusion — framing the 2026 decision
2026 represents a strategic inflection point: the market is mature enough to offer multiple credible options but still fluid enough that procurement shape and technical choices will materially affect the next decade of sustainment economics. PW Consulting’s Defense Asset Management Software Market study provides the data‑backed forecasts, vendor assessments, compliance playbooks, and implementation roadmaps required to make those high‑stakes choices with confidence.
Next steps
For program leads, prime contractors, and technology providers preparing 2026 budgets and RFPs, our report is designed as an actionable companion—offering scenario models, negotiation playbooks, and vendor shortlists tailored to defense contexts. To access the full analysis, vendor matrices, and the detailed annexes (including model inputs and methodology), please visit the PW Consulting report download page.
For detailed analysis of this topic, please visit the official page: Defense Asset Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com